


Oil prices are sitting above US$100 a barrel, and that keeps energy costs high for Australian households and businesses. Reliable dividend income suddenly looks more attractive when cash returns on offer from selected shares can help offset rising bills. This article breaks down three high yielding Australian dividend stocks from a quality focused screen that looks for payouts above 3% that appear well covered, growing and relatively steady.
The three stocks covered below are only a sample, with the full screen surfacing 37 more high yielding dividend payers with similarly interesting stories that are not included here.
To see the wider opportunity set and pressure test your own ideas, head into the Dividend Powerhouses (3%+ Yield) screener to identify, filter and analyze the dividend payers that best fit your income goals.
Objective (ASX:OCL)
Objective Corporation plugs directly into the Dividend Powerhouses theme because its information governance tools, such as Objective Nexus and related compliance products, cater to regulated customers that tend to produce recurring cash flows and support well covered, stable dividends from its A$134.7 million software revenue base. With a market cap near A$556 million, it remains a mid cap income candidate anchored in mission critical software.
Objective Corporation is a software specialist focused on information governance, content management and secure collaboration, generating A$134.7 million from its Software & Programming operations. These tools, including Objective Nexus, serve highly regulated clients that often favour consistent cash flows and dependable dividends. The company has a market value of about A$556 million.
Objective’s dividend profile leans on this “essential plumbing” role in government workflows, so the reliability of those cash flows, and what could shake them, matters a great deal.
"When a regulator issues a licence, when a council approves a development application, when a department publishes policy, Objective's software is probably running underneath."
The key question is how one unresolved customer concentration risk could ripple through dividend cover, pricing power and future growth expectations.
That concentration question is the crux, and the full narrative for Objective breaks down how Objective could keep dividends flowing if one key customer relationship stalled or suddenly accelerated.

Vita Life Sciences (ASX:VLS)
Vita Life Sciences manufactures and sells branded vitamins and dietary supplements under Herbs of Gold, VitaHealth and VitaScience, a classic recurring cash flow business that fits the Dividend Powerhouses theme. It generates about A$43 million in Australia and A$46 million in Malaysia and Singapore, with A$6 million from China and Vietnam, and has a market cap near A$150 million.
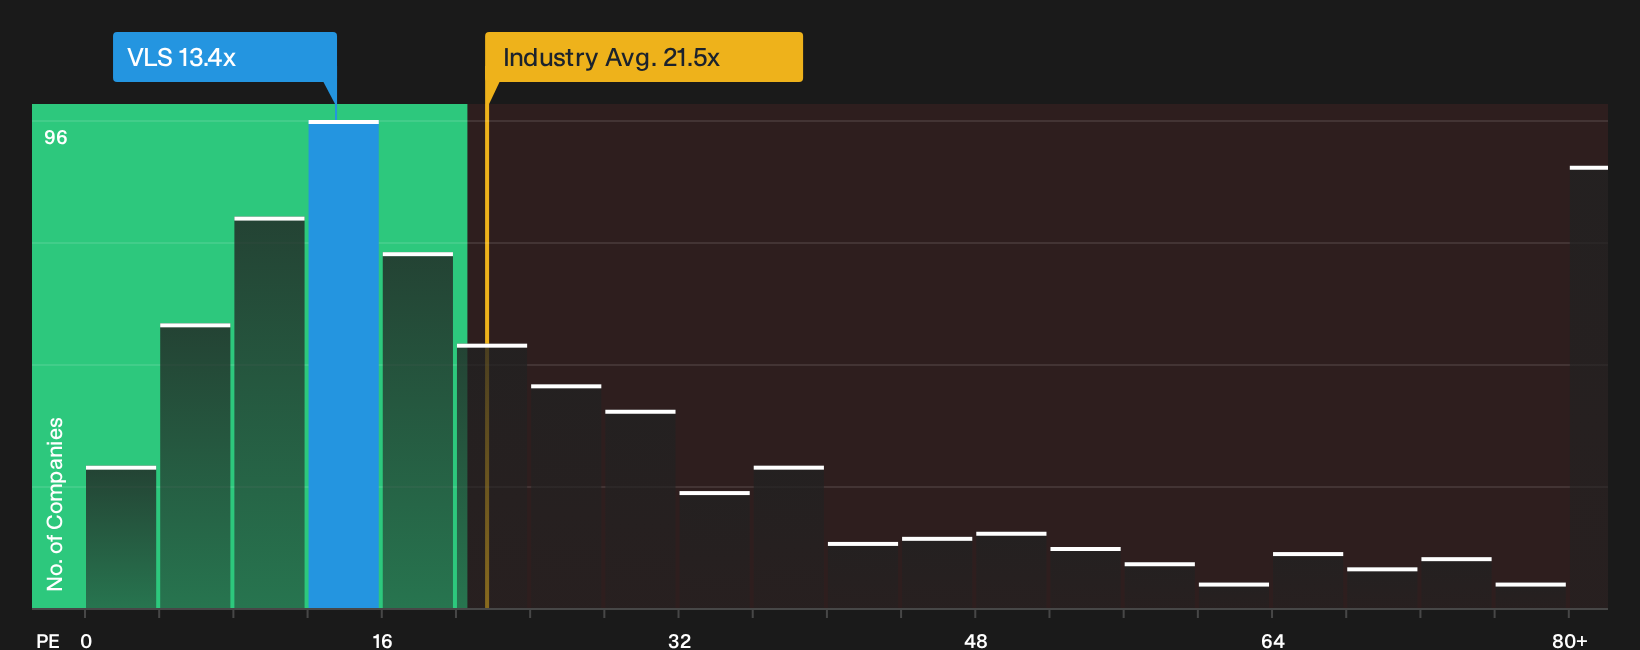
Vita Life Sciences offers a 5.05% yield backed by recurring supplement sales, a P/E of 13.4x and recent earnings growth, which together indicate a potential fit for investors who prioritise well covered, income focused dividends, depending on how one quiet shift in insider behavior plays out.
That insider shift is the real hinge, and the 3 key rewards and 1 important warning sign shows whether Vita Life Sciences’ income story is quietly strengthening or starting to fray.
Fiducian Group (ASX:FID)
Fiducian Group runs an integrated wealth platform built around funds management and income generating managed portfolios, which feed directly into the 3%+ dividend theme. It earned A$37 million from Funds Management, A$34 million from Financial Planning, A$24 million from Platform Administration, and has a market cap near A$269 million.
For income focused investors, Fiducian Group is interesting because its funds and managed portfolios produce recurring fee streams that can underpin a higher yield. At the same time, recent earnings pressure and regulatory noise raise questions about how durable that payout really is.
"Bad press is a problem for any company, and bad press involving misleading statements and compliance failures even more so."
The real test for Fiducian Group is what happens to that fee backed dividend appeal if one emerging pressure on trust and inflows intensifies.
If that pressure on trust keeps building, the full narrative for Fiducian Group shows whether Fiducian Group’s dividend story is quietly stalling or is set to reaccelerate.

Curious About What You Might Be Missing Next
Fresh ideas do not wait. Momentum shifts, early breakouts form and under the radar for now opportunities get caught fast. Scan these themed lists before the crowd and consider your next move carefully.
- Identify potential turnaround plays with stronger balance sheets by running your filters through the list of solid balance sheet and fundamentals (12 results). Review a curated view before others catch on.
- Explore long term infrastructure themes by checking the curated 44 power grid technology and infrastructure stocks while these stories may still be flying under the radar.
- Follow fast moving automation leaders by screening the curated 87 robotics and automation stocks before interest changes and some of the most notable candidates move off your radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com