


Why Delek US Holdings Is Back On Investors’ Radar
Delek US Holdings (DK) has just issued and completed a US$400 million offering of senior unsecured zero coupon convertible notes due November 1, 2031, a funding move that directly feeds into the equity story.
The new paper carries attached guarantees, is callable and is issued under Rule 144A, which means it targets qualified institutional buyers while still leaving a clear path for future equity conversion.
For anyone tracking Delek US Holdings stock, the decision to raise capital in this format puts attention on future leverage, liquidity headroom and how management might allocate this fresh funding across refining and logistics operations.
Recent trading in Delek US Holdings has been strong, with the latest share price at US$75.67 and a 7 day share price return of 10.10%, building on a 90 day gain of 35.00% and a 1 year total shareholder return of 145.37%. This suggests momentum has been building as investors reassess risk and potential following moves such as the new convertible issuance.
Compare Delek US Holdings’ latest funding move with other refiners and energy players showing strong momentum by scanning our hand picked 27 high quality undervalued stocks in the same space.
Delek US Holdings now has fresh zero coupon convertible funding in place and a sharply higher share price. The real tension is whether that stronger platform is already fully reflected in the valuation.
Most Popular Narrative: 1% Overvalued
At a last close of $75.67 against a widely followed fair value estimate of $75, the prevailing view on Delek US Holdings is that the stock is priced slightly above that narrative assessment, which raises questions about how much of the current optimism is already embedded in the share price.
Delek's sustained operational improvements driven by its enterprise optimization program (EOP), which targets structural changes in refinery operations, procurement, and product sales, are expected to deliver $130 to $170 million of annualized cash flow enhancements, with much of the benefit expected to flow through to net margins and free cash flow starting in the second half of 2025.
See why 11 investors see Delek US Holdings as 1% overvalued.
Result: Fair Value of $75 (OVERVALUED)
Still, Delek US Holdings leans heavily on traditional refining and carries meaningful debt, so adverse regulation or weaker fuel demand could quickly challenge today’s optimistic narrative.
Find out about the key risks to this Delek US Holdings narrative.
Another View On Delek US Holdings’ Valuation
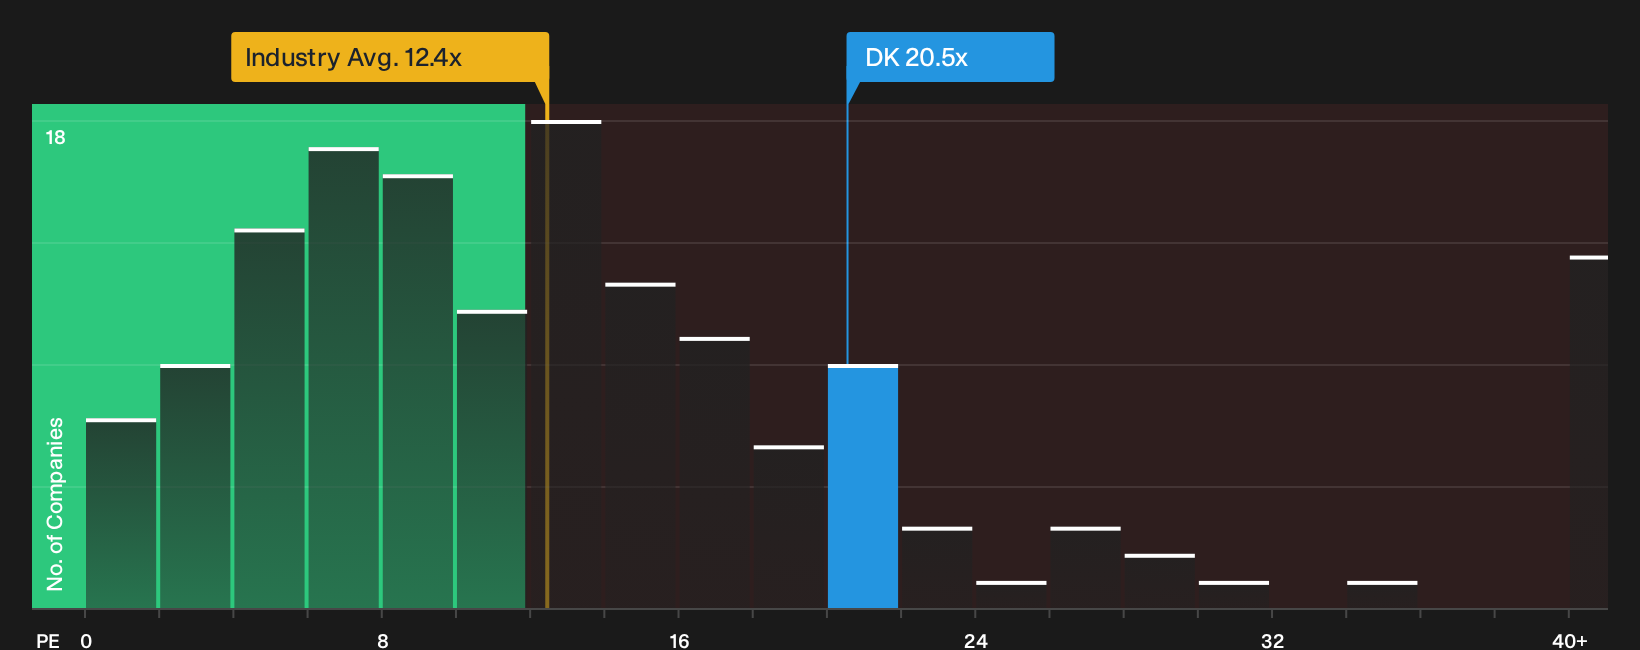
On simple earnings terms, Delek US Holdings screens differently. The stock trades on a P/E of 20.5x, which is cheaper than close peers on 27x, yet far richer than the US Oil and Gas industry on 12.4x and well above a fair ratio of 7.6x. That gap points to meaningful valuation risk if sentiment cools.
For a closer look at how this earnings multiple compares with peers and the fair ratio that the market could move toward, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the mixed signals on Delek US Holdings leave you undecided, move quickly, review the data yourself, and pressure test both sides of the story with 1 key reward and 3 important warning signs
Looking For More Investment Ideas Beyond Delek US Holdings?
Do not stop your research with Delek US Holdings. Cast a wider net with targeted stock ideas so you are not relying on a single story.
- Target potential mispricing by scanning a curated pool of companies that screen as high quality yet possibly overlooked using the 27 high quality undervalued stocks.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (25 results) that can help you focus on businesses with financial strength when conditions get tougher.
- Hunt for tomorrow's potential standouts by checking a set of 19 high quality undiscovered gems before they attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com