


Konica Minolta (TSE:4902) has been removed from the Nikkei 225 Index, a development that can affect index-tracking fund flows and reshape how some investors view the stock within Japan’s broader equity market.
At a share price of ¥652.0, Konica Minolta has seen a 12.03% 90-day share price return, yet remains down 5.59% on a year-to-date share price basis. Its 21.88% 1-year total shareholder return hints that momentum has shifted recently, with the Nikkei 225 removal now testing how durable that sentiment really is.
Compare how Konica Minolta's index exit stacks up against other potential rebound stories by scanning our hand picked list of 75 high quality undiscovered gems across global markets.
Konica Minolta has already put up a strong 1-year total return, yet the index removal and large implied discount to intrinsic value pull in the opposite direction. Is most of the upside already cashed in, or not yet priced?
Preferred P/E of 9.9x for Konica Minolta: Is it justified?
On valuation, Konica Minolta trades on a P/E of 9.9x, which screens as inexpensive next to both its own fair P/E estimate and peer group levels at a last close of ¥652.0.
P/E compares what you pay today for each unit of current earnings, so a lower ratio can mean either the market is cautious on future profit trends or that investors are not assigning much credit for the existing earnings base.
For Konica Minolta, the current P/E of 9.9x is well below the estimated fair P/E of 15.4x. This gap suggests the share price is not fully reflecting its earnings profile. It also trades at a clear discount to the JP Tech industry average P/E of 12.3x and the peer average of 16.7x. This implies the market is pricing the stock more conservatively than both the broader sector and closer comparables, while the fair P/E points to a level the valuation could shift toward if sentiment improves.
Explore the SWS fair ratio for Konica Minolta.
Result: Price-to-Earnings of 9.9x (UNDERVALUED)
Still, the Nikkei 225 removal, along with only modest annual revenue and net income growth, both leave room for sentiment on Konica Minolta to cool quickly.
Find out about the key risks to this Konica Minolta narrative.
Another view on Konica Minolta’s value
The SWS DCF model points in the same direction as the earnings multiple, with Konica Minolta at ¥652 trading at a very large discount to an estimated future cash flow value of ¥1,165.75. If both methods lean the same way, it may be worth considering how much mispricing you are comfortable assuming.
Look into how the SWS DCF model arrives at its fair value.
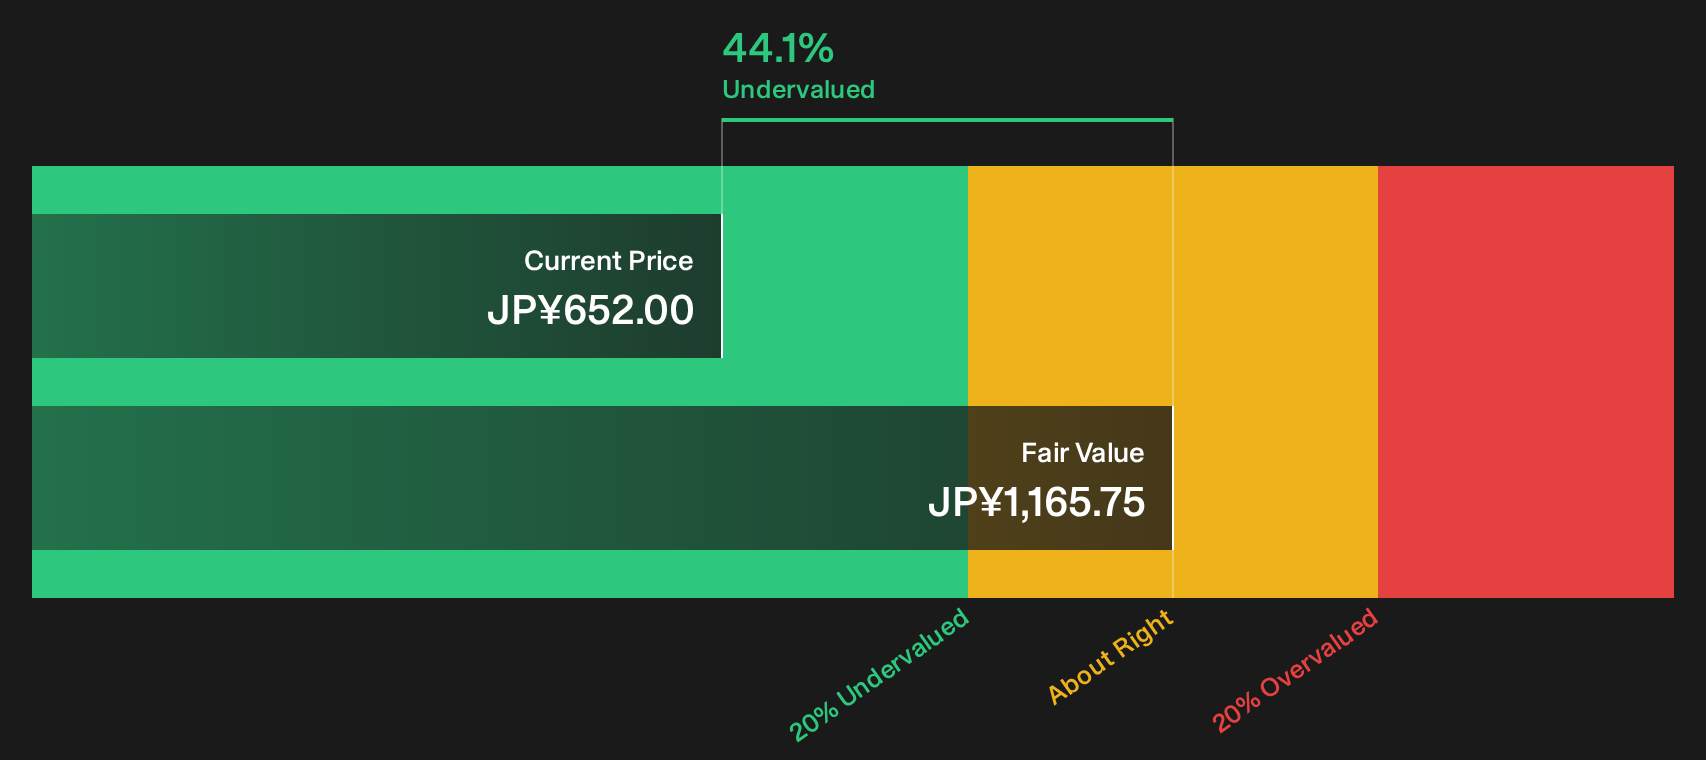
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Konica Minolta for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Konica Minolta can feel confusing, so move quickly, review the underlying data, and decide where you land on those 4 key rewards and 2 important warning signs
Want more ideas beyond Konica Minolta?
If Konica Minolta has you thinking harder about where to put fresh capital next, use that momentum and scan a few focused stock shortlists while the opportunity set is still wide.
- Target potential mispricing by reviewing companies that screen as high quality yet undervalued using the 14 high quality undervalued stocks.
- Prioritise resilience by checking businesses that carry strong balance sheets and fundamentals in the list of solid balance sheet and fundamentals (23 results).
- Spot opportunities others might overlook by assessing lesser known candidates with solid financials through the 75 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com