


As the Asian markets navigate a complex landscape marked by evolving economic policies and fluctuating investor sentiment, growth companies with substantial insider ownership have garnered significant attention. In such an environment, these businesses often stand out due to the alignment of interests between insiders and shareholders, potentially offering stability and confidence amid broader market uncertainties.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 74.9% |
| Shanghai Skychem Technology (SHSE:688603) | 31.8% | 67.7% |
| SEERS (KOSDAQ:A458870) | 33.8% | 37.8% |
| L&C BIOLTD (KOSDAQ:A290650) | 20.9% | 163% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| JHT DesignLtd (SHSE:603061) | 23.1% | 48.6% |
| HUMAN MADE (TSE:456A) | 29.1% | 28.7% |
| Guangdong Shenling Environmental Systems (SZSE:301018) | 36.7% | 65.4% |
| Great Microwave Technology (SHSE:688270) | 21.1% | 95.2% |
| Fulin Precision (SZSE:300432) | 10.8% | 66.5% |
We're going to check out a few of the best picks from our screener tool.
Beijing 51World Digital Twin Technology (SEHK:6651)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Beijing 51World Digital Twin Technology Co., Ltd. operates in the digital twin technology sector and has a market capitalization of approximately HK$23.22 billion.
Operations: The company's revenue primarily comes from its CAD/CAM Software segment, which generated CN¥417.61 million.
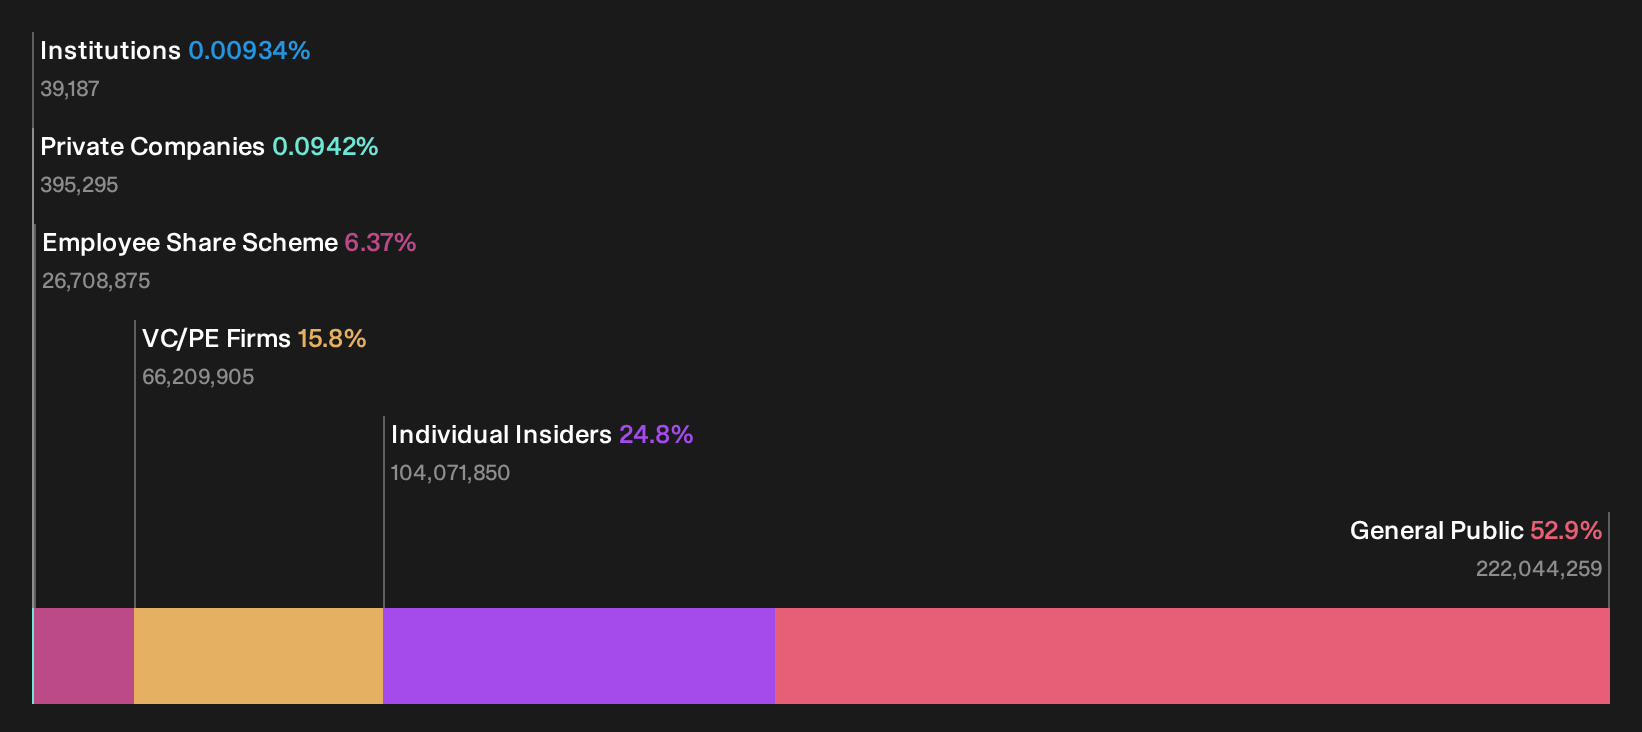
Insider Ownership: 24.8%
Beijing 51World Digital Twin Technology is experiencing significant revenue growth, with forecasts predicting a 68.9% annual increase, outpacing the Hong Kong market's average. Despite current unprofitability, earnings are expected to grow substantially by 110.55% annually, turning profitable within three years. Recent product launches like AperData and AperOne aim to enhance embodied AI applications across various industries. The company's strategic partnerships and ambitious roadmap position it well for future expansion despite high share price volatility and no recent insider trading activity noted.
- Unlock comprehensive insights into our analysis of Beijing 51World Digital Twin Technology stock in this growth report.
- In light of our recent valuation report, it seems possible that Beijing 51World Digital Twin Technology is trading beyond its estimated value.
Ninebot (SHSE:689009)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Ninebot Limited is involved in the R&D, production, sale, and servicing of short-distance transportation and robot products both in China and internationally, with a market cap of CN¥27.30 billion.
Operations: Ninebot Limited's revenue is primarily derived from its activities in short-distance transportation and robot products across domestic and international markets.
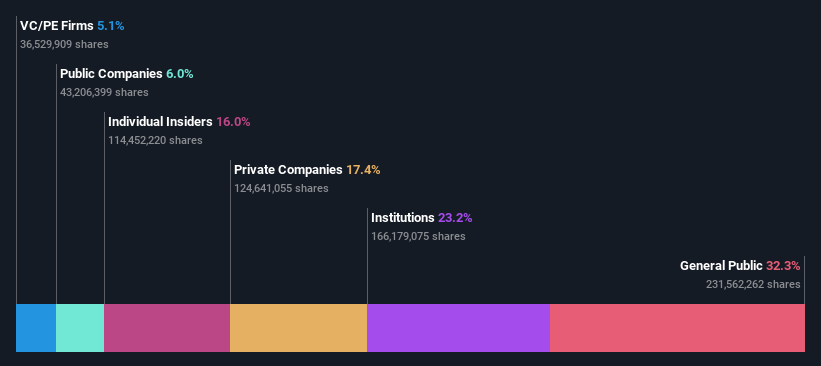
Insider Ownership: 13.1%
Ninebot Limited's revenue for H1 2026 increased to CNY 14.36 billion, though net income declined to CNY 1.01 billion. Despite slower revenue growth forecasts of 19.6% annually, earnings are expected to grow significantly at over 30% per year, surpassing the Chinese market average. The stock trades significantly below its estimated fair value, with analysts predicting a substantial price increase of over 50%. No recent insider trading activity was reported in the past three months.
- Click here and access our complete growth analysis report to understand the dynamics of Ninebot.
- Insights from our recent valuation report point to the potential undervaluation of Ninebot shares in the market.
Scientech (TWSE:3583)
Simply Wall St Growth Rating: ★★★★★★
Overview: Scientech Corporation focuses on the R&D, production, sale, and maintenance of process equipment for the semiconductor, LCD, LED, and solar power industries with a market cap of NT$63.71 billion.
Operations: The company's revenue is primarily derived from its brokerage segment, which generated NT$6.22 billion, and its manufacturing segment, contributing NT$5.62 billion.
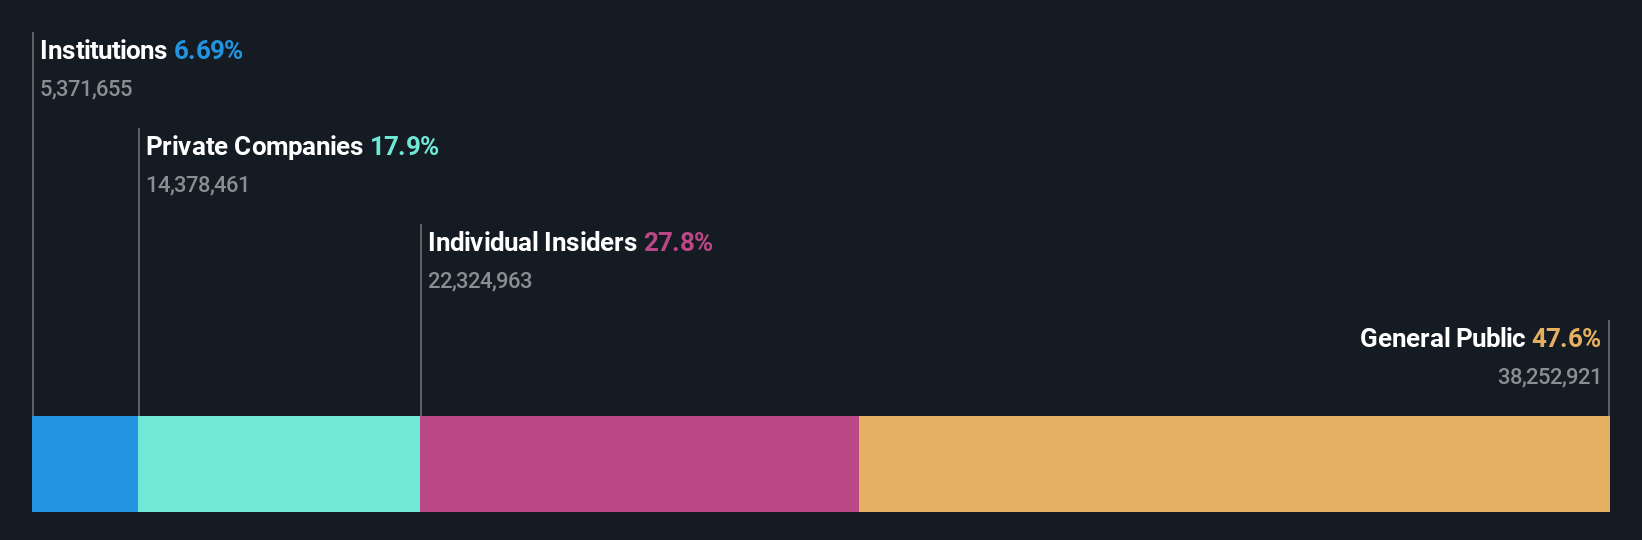
Insider Ownership: 19.5%
Scientech's earnings surged by 39.5% last year, with forecasts suggesting significant annual profit growth of 37.31%, outpacing the TW market average. Revenue is expected to grow at 22.4% per year, surpassing market rates. Despite recent volatility in share price, analyst consensus indicates a potential stock price rise of 57%. Recent earnings reports show strong performance with net income rising to TWD 406.05 million for Q2 and TWD 739.01 million for H1 2026, reflecting robust operational momentum without notable insider trading activity recently.
- Dive into the specifics of Scientech here with our thorough growth forecast report.
- The analysis detailed in our Scientech valuation report hints at an inflated share price compared to its estimated value.
Turning Ideas Into Actions
- Gain an insight into the universe of 494 Fast Growing Asian Companies With High Insider Ownership by clicking here.
- Interested In Other Possibilities? AI is about to change healthcare. These 126 stocks are working on everything from early diagnostics to drug discovery. The best part - they are all under $10b in market cap - there's still time to get in early.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com