


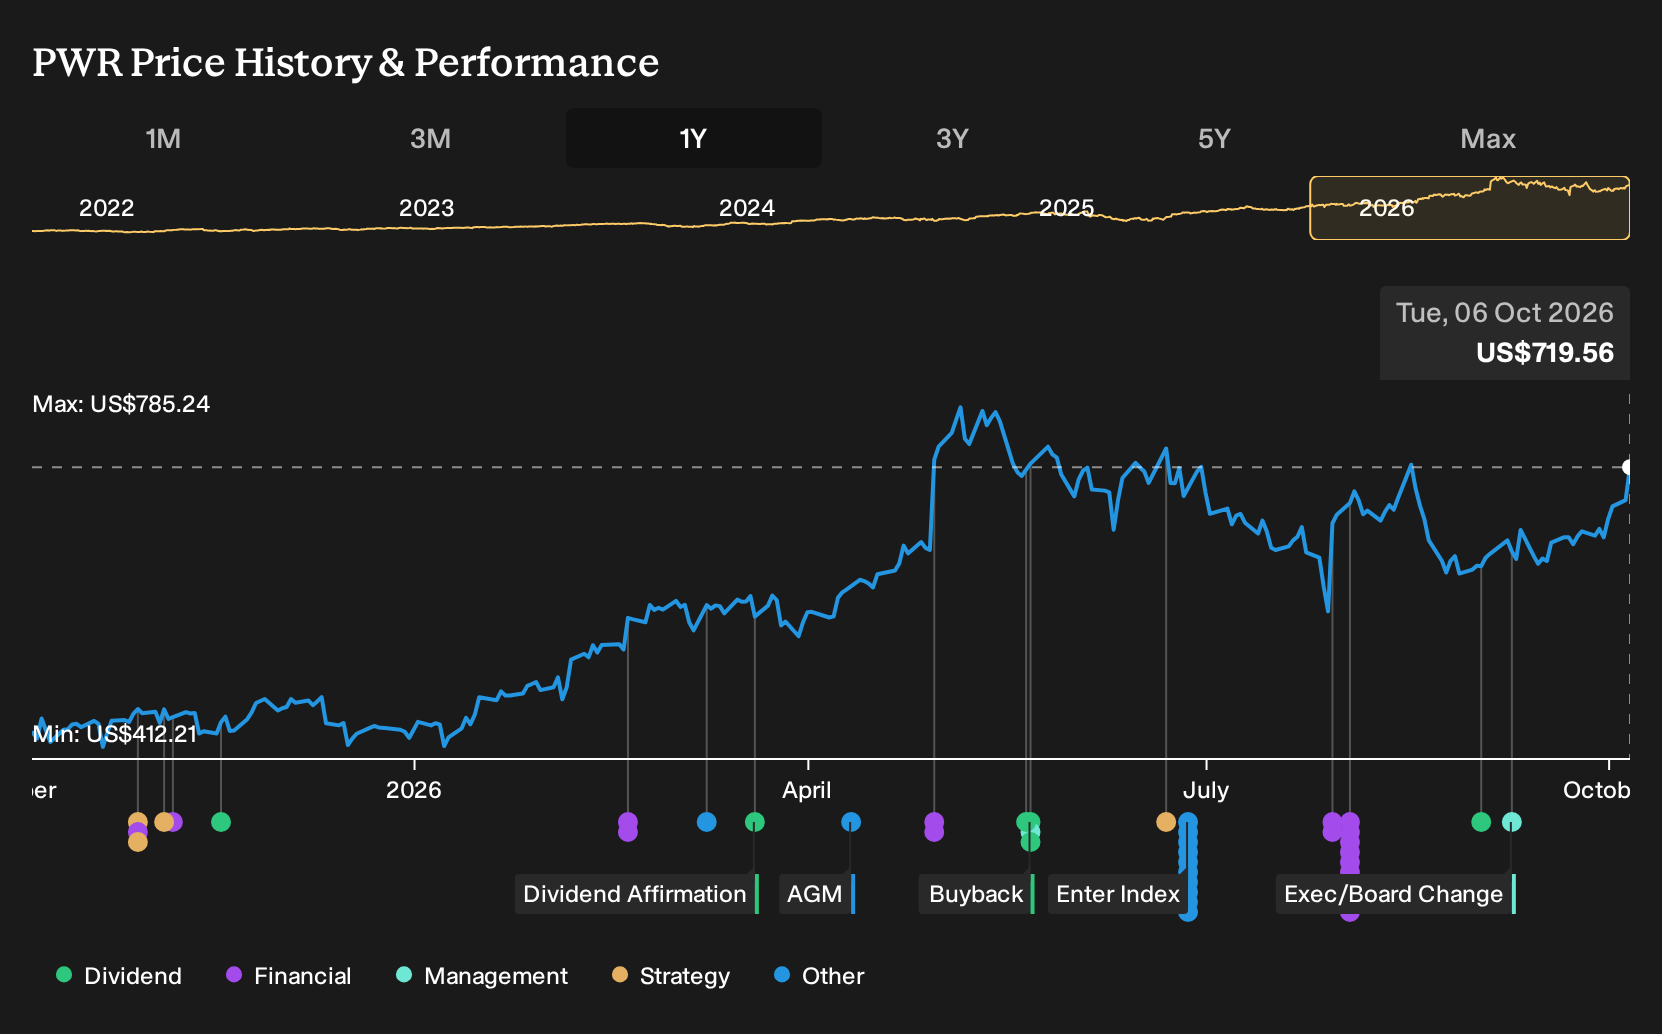
- Jim Cramer recently called Quanta Services a "terrific" industrial stock that appears to have finished declining, bringing fresh attention to the contractor’s role in large scale power and utility projects.
- The commentary highlights Quanta Services underlying exposure to grid modernization, high voltage work and large load power build outs tied to data centers and renewables.
- This article examines how Quanta Services investment narrative is shaped by this endorsement of its high voltage and grid focused platform.
Quanta Services Investment Narrative Recap
To own Quanta Services, you need to believe its grid, data center and high voltage work can be executed at scale without eroding margins. The near term story leans on converting a roughly US$53b backlog and elevated 2026 guidance into consistent free cash flow while integrating acquisitions and expanding manufacturing capacity.
The biggest swing factor over the next stretch is whether AI driven data center and large load projects ramp as expected and stay on schedule. The key risk sits on the other side of that optimism. High expectations, a rich P/E and guidance that has already been raised leave little room for execution slip ups.
There have not been fresh operational announcements tied directly to Jim Cramer’s comments, so the more important reference point remains Quanta Services updated 2026 outlook. Management now guides to US$39.3b to US$39.7b of revenue, US$4.1b to US$4.2b of adjusted EBITDA and US$2.0b to US$2.5b of free cash flow.
Those figures frame both the opportunity and the risk around the endorsement. Positive media attention may keep focus on the grid and data center story, but the real test is delivery against that higher bar, including contributions from acquisitions and large capital projects, while managing debt levels and any policy related drag in renewables work.
Quanta Services' narrative projects US$54.6b revenue and US$2.7b earnings by 2029. This projection assumes 18.4% yearly revenue growth and would require earnings to roughly double from about US$1.3b today to reach that 2029 consensus level.
Uncover why Quanta Services' fair value indicates a 7% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on Quanta Services leans heavily on margin pressure rather than growth. The most cautious analysts, who were pencilling in about US$50.9b of 2029 revenue and US$2.5b of earnings before Jim Cramer’s comments, see limited room for error. That is a much more pessimistic story. Use this gap to test your own assumptions and watch how these narratives may shift as the grid upgrade theme and media attention evolve.
Explore 5 other Quanta Services fair value estimates, including one that suggests as much as 33% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Quanta Services research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Quanta Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Quanta Services' overall financial health at a glance.
Looking For More Investment Ideas Beyond Quanta Services?
Once you have a view on Quanta Services, it can help to compare that with a few other opportunities that fit your preferred style, whether you care most about value, resilience or income.
- If you want potential value on your side, scan a curated set of high quality candidates using our 27 high quality undervalued stocks.
- For a focus on financial strength and staying power, compare Quanta Services with our list of solid balance sheet and fundamentals (25 results) to see which businesses match your risk profile.
- If reliable income is your priority, weigh Quanta Services against companies in our 8 dividend fortresses to spot yield opportunities that fit your goals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com