


Vishay Intertechnology (VSH) has been busy. A flurry of recent launches in 650 V superjunction MOSFET power modules and automotive grade resistors is drawing fresh attention to how this stock fits into industrial and renewable energy spending.
All this product activity comes alongside a sharp move in Vishay Intertechnology’s share price, with a 7 day share price return of 16.57% and a 30 day share price return of 18.99% pushing the stock to US$37.84, even though the 90 day share price return is down 10.31%. Over longer periods the picture is stronger, with a 1 year total shareholder return of 150.59% and a 5 year total shareholder return of 118.39%, suggesting momentum has been building rather than fading.
Scan for other electrification plays riding similar product momentum by filtering for 44 power grid technology and infrastructure stocks that could benefit from rising spend on industrial, charging, and renewable energy infrastructure alongside Vishay Intertechnology.
Bulls point to Vishay Intertechnology’s product pipeline and substantial 1-year return, while bears focus on the recent 90-day pullback and cyclicality. The key question is which side the current valuation really supports next.
Most Popular Narrative: 5.4% Undervalued
Set against the last close of $37.84, the most followed narrative pegs Vishay Intertechnology’s fair value at $40.00. The current price sits slightly below that anchor while analysts focus on how new capacity and product mix might reshape earnings power.
The main thing that has to go right is that Vishay Intertechnology successfully fills its expanded Western and wide-bandgap capacity with sustained demand from AI infrastructure, industrial power and smart grid projects, automotive electrification, and aerospace and defense customers, while executing planned mix and pricing actions.
See why 11 investors see Vishay Intertechnology as 5% undervalued.
Result: Fair Value of $40.00 (UNDERVALUED)
Still, the whole Vishay Intertechnology story can change quickly if heavy capex keeps free cash flow weak or if new fabs struggle to attract profitable programs.
Find out about the key risks to this Vishay Intertechnology narrative.
Another View: Vishay Intertechnology Through The Sales Lens
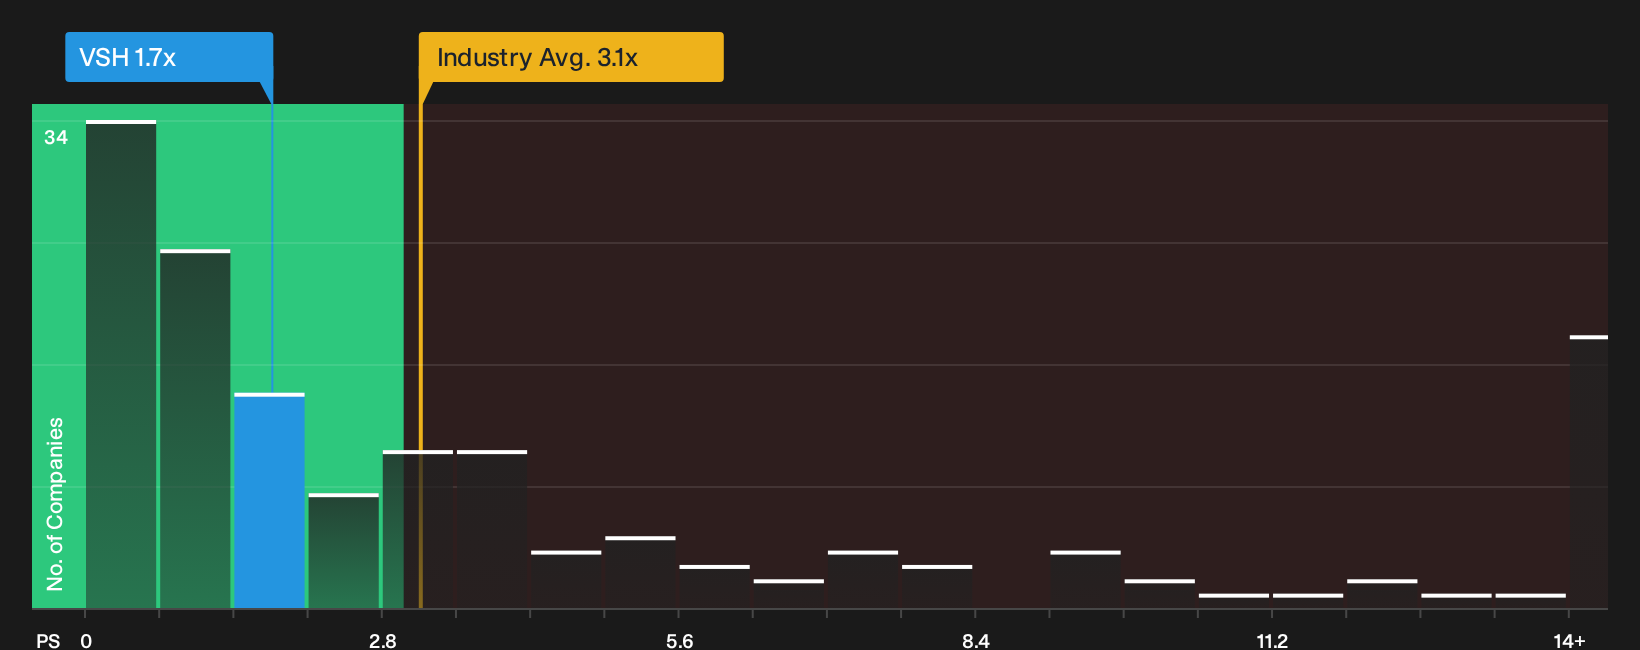
The earlier fair value of $40.00 leaned on long term earnings power and discounted cash flow style thinking. A simple sales based yardstick tells a slightly different story. Vishay Intertechnology trades on a P/S ratio of 1.7x, above a fair ratio of 1.4x, yet well below the US Electronic industry on 3.1x and peers on 3.6x. That mix of local expensiveness versus wider sector cheapness leaves a practical question. Is the real risk missing further rerating if the stock drifts toward sector levels, or overpaying if it slides back toward the fair ratio?
Our valuation breakdown can help you pressure test which outcome you think is more realistic for your own portfolio. It is worth going deeper into how this sales multiple was derived and what might drive it to change over time, then seeing what the numbers say in the See what the numbers say about this price — find out in our valuation breakdown.
For a visual sense of how that current P/S ratio stacks up against the rest of the sector, review the latest comparison in
Next Steps
Mixed signals around Vishay Intertechnology can either feel exciting or confusing, so move quickly, pull up the full data set, and pressure test both the upside and the downside by reviewing the 3 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Vishay Intertechnology?
Do not stop your research with Vishay Intertechnology when a wider set of opportunities could sharpen how you position your portfolio for the next phase of the cycle.
- Target companies with strong fundamentals and sensible valuations by scanning a curated 27 high quality undervalued stocks that might complement or contrast your view on Vishay Intertechnology.
- Prioritize resilience over excitement by reviewing a 31 resilient stocks with low risk scores that can help balance more cyclical exposure in your holdings.
- Hunt for underfollowed opportunities by checking a 19 high quality undiscovered gems that could broaden your watchlist beyond the usual large caps.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com