


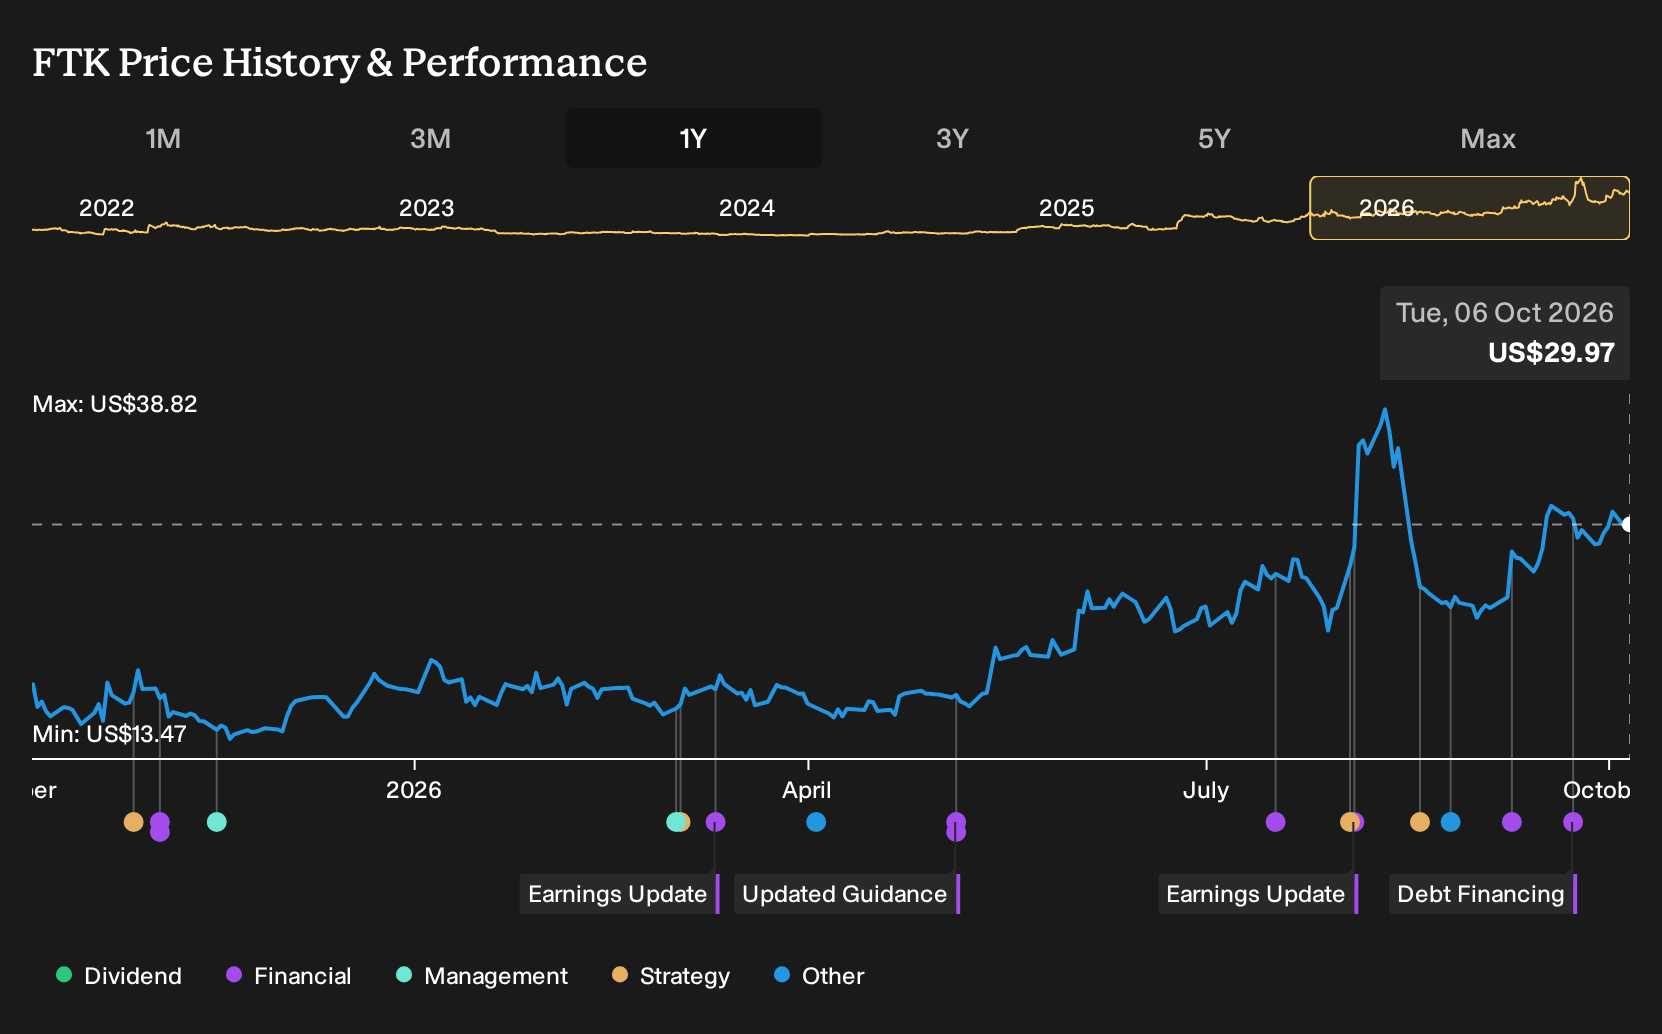
- Flotek Industries entered a new secured term loan agreement in September 2026, providing $75 million at closing and up to $45 million in delayed-draw capacity to refinance existing debt, fund its Data Analytics segment, support working capital, and extend its asset-based loan maturity to October 31, 2027.
- The long-dated term loan to September 23, 2031, with no amortization or excess cash sweep for two years, gives Flotek Industries more room to prioritize Data Analytics build-out, capital spending, and contract execution without immediate pressure to redirect cash toward rapid debt paydown.
- This article examines how Flotek Industries' investment narrative is affected by this long-term secured funding that targets its Data Analytics operations.
Scan how Flotek Industries' funding move compares with other companies that are reshaping their balance sheets, using the curated list of solid balance sheet and fundamentals (25 results) as a starting point for ideas.
Flotek Industries Investment Narrative Recap
To own Flotek Industries, you need to believe the shift toward higher margin Data Analytics can gradually matter more than the legacy Chemistry Technologies unit. The new US$120 million secured term loan gives management room to keep funding measurement hardware, software and deployments without immediately squeezing near term spending.
The key near term swing factor remains execution on multi year analytics contracts and pilots, especially where customer concentration is high. The biggest risk still sits in that combination of contract reliance and execution. If major counterparties slow roll deployments or resize agreements, the extra liquidity will not fully offset revenue and margin pressure.
The fresh term loan is itself the most relevant recent announcement. It refinances a prior US$40 million facility, extends the asset based loan to October 31, 2027, and pushes the new term loan maturity out to 2031, with no amortization or excess cash sweep for the first two years.
For you as a shareholder, that structure matters because Flotek Industries now has committed delayed draw capacity tied to Data Analytics capital expenditure and working capital, alongside an undrawn asset based line. The funding mix still leans on higher risk external borrowing, so balance sheet strength hinges on converting pilots into recurring analytics revenue and keeping the chemistry segment resilient against commodity and activity swings.
Flotek Industries' outlook projects US$362.3 million in revenue and US$29.1 million in earnings by 2029. This scenario assumes 7.3% yearly revenue growth and an earnings decrease of US$8.9 million from US$38.0 million today.
Uncover why Flotek Industries' fair value indicates a 28% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts look at the Puerto Rico power project risk very differently from the baseline view you just read. You see them still penciling in US$431.8 million of revenue and US$32.9 million of earnings by 2029 for Flotek Industries, even though those forecasts came before this new US$120 million term loan. That gap in expectations shows how far opinions can spread, so it can help to compare several narratives and decide which assumptions feel realistic to you.
Explore 3 other Flotek Industries fair value estimates, including one that suggests there could be as much as 47% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Flotek Industries research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Flotek Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Flotek Industries' overall financial health at a glance.
Looking For More Investment Ideas Beyond Flotek Industries?
If the Flotek Industries story has sharpened your thinking about risk, funding structure, and contract exposure, it can help to compare it with other businesses that screen well on different fundamentals using the Simply Wall St Screener.
- For investors who want lower volatility and sturdier finances, review companies that pass a strict resilience filter through the 31 resilient stocks with low risk scores.
- If you are hunting for potential value opportunities with strong fundamentals, scan the 27 high quality undervalued stocks and see which stocks currently line up with that profile.
- Income focused readers who care most about steady cash returns can start with the 8 dividend fortresses and look for yields that fit their risk tolerance.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com