


GlobalFoundries (GFS) just reported 62% year over year growth in its Communications Infrastructure and Data Center business, raised full year growth targets, and reached its non IFRS gross margin goal of 29.9% ahead of schedule.
GLOBALFOUNDRIES shares trade at US$48.63, with a 30 day share price return of 7.56% and a year to date gain of 31.90%, suggesting momentum has recently picked up after a 90 day slide of 28.45%. Over a longer horizon, the 1 year total shareholder return of 39.85% contrasts with a 3 year total shareholder return that has declined 15.85%. This hints that the latest earnings beat and new funding announcements are being treated more as a turn in sentiment than the end of a longer rebuilding phase.
Scan beyond GLOBALFOUNDRIES and compare this earnings-driven momentum with our hand picked list of 91 AI infrastructure stocks powering the same build out in data centers and communications networks.
GLOBALFOUNDRIES now trades well below the average analyst price target, yet above some intrinsic estimates based on current cash flows. Is the recent surge a catch up to fair value, or is it already past it?
Most Popular Narrative: 36% Undervalued
GLOBALFOUNDRIES is pinned at a fair value of $76.00 in the most followed narrative, compared with the latest close at $48.63. This frames the recent rally as only a partial move toward that anchor.
Capacity additions in high demand areas such as silicon photonics, SiGe, FDX and power are coinciding with strong communications infrastructure and data center demand, including 62% year over year growth and raised 2026 guidance to the 50% to 60% range. This can provide operating leverage for gross margin and earnings as utilization stays high. The expansion of technology services, including IP, licensing, software and contributions from the MIPS and Synopsys ARC acquisitions that are expected to reach the high end of 10% to 12% of 2026 revenue with higher than corporate gross margins, supports a mix shift that can lift GlobalFoundries overall margin profile and earnings power.
See why 43 investors see GLOBALFOUNDRIES as 36% undervalued.
Result: Fair Value of $76.00 (UNDERVALUED)
Still, if smart mobile weakness lingers or heavy capital spending fails to earn its keep, the optimistic GLOBALFOUNDRIES narrative could quickly lose traction.
Find out about the key risks to this GLOBALFOUNDRIES narrative.
Another View on GLOBALFOUNDRIES Valuation
The first narrative pegs GLOBALFOUNDRIES at a fair value of $76.00, implying the stock is undervalued. The SWS DCF model points in the other direction, with an intrinsic value of $34.71, which would leave shares trading above that estimate. Which story do you think fits your own assumptions better?
Look into how the SWS DCF model arrives at its fair value.
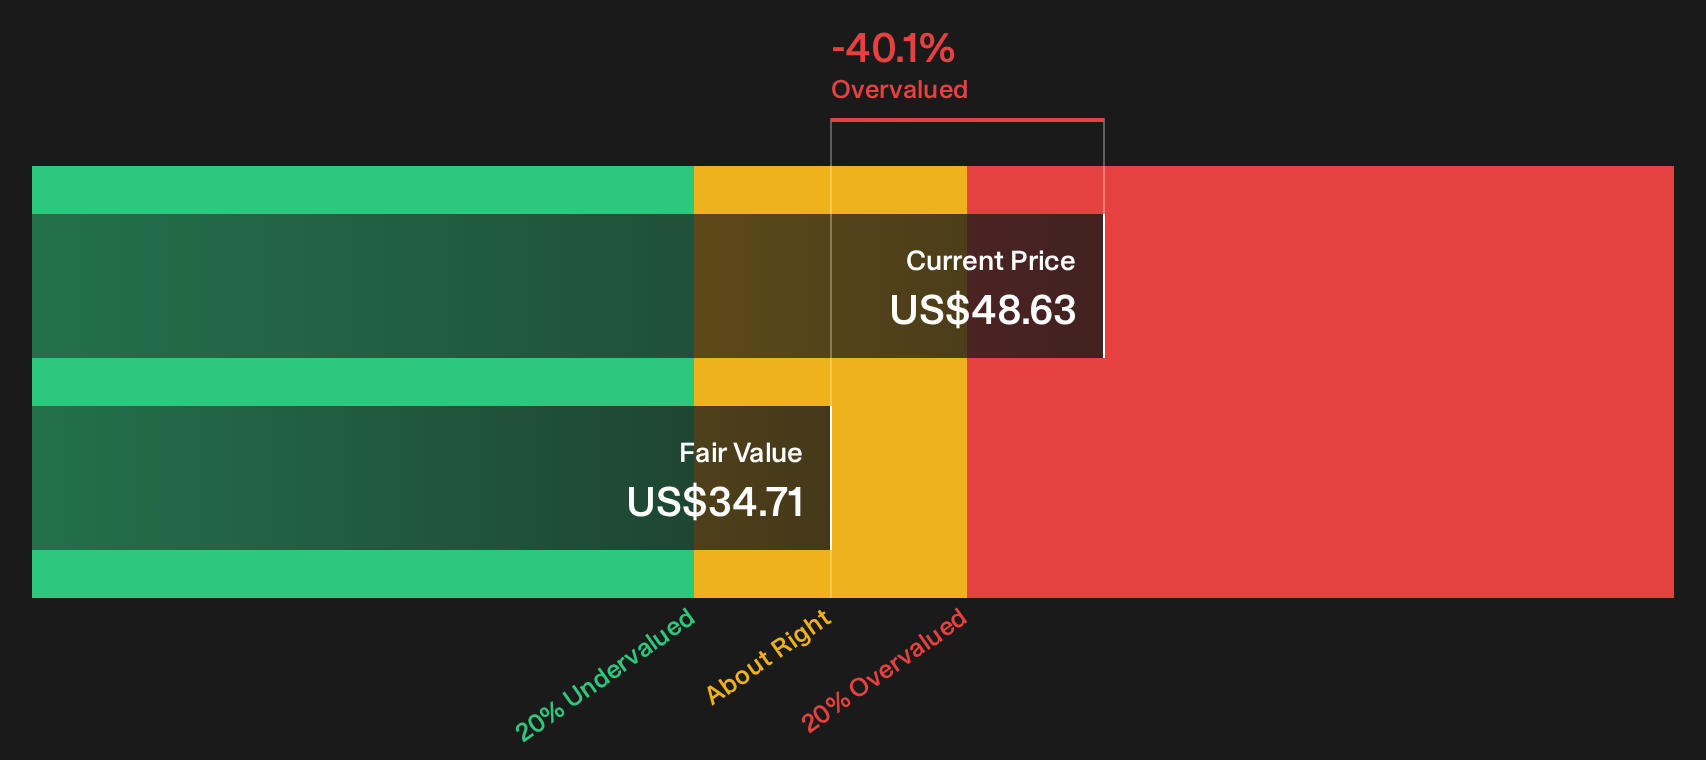
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out GLOBALFOUNDRIES for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If GLOBALFOUNDRIES really has sentiment at its back, you probably want to test the numbers yourself and not just lean on one storyline. To see what optimism is already baked in, take a closer look at 3 key rewards.
Want more ideas beyond GLOBALFOUNDRIES?
If GLOBALFOUNDRIES caught your attention, do not stop there. Broader context across other stocks can sharpen your judgement and highlight opportunities you might otherwise skip.
- Zero in on quality at a discount and scan through 27 high quality undervalued stocks that may already align with the return profile you want.
- Build a steadier income base by reviewing 8 dividend fortresses that focus on higher yielding payouts backed by stronger fundamentals.
- Prioritise resilience first and stress test your watchlist against 31 resilient stocks with low risk scores before committing fresh capital.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com