


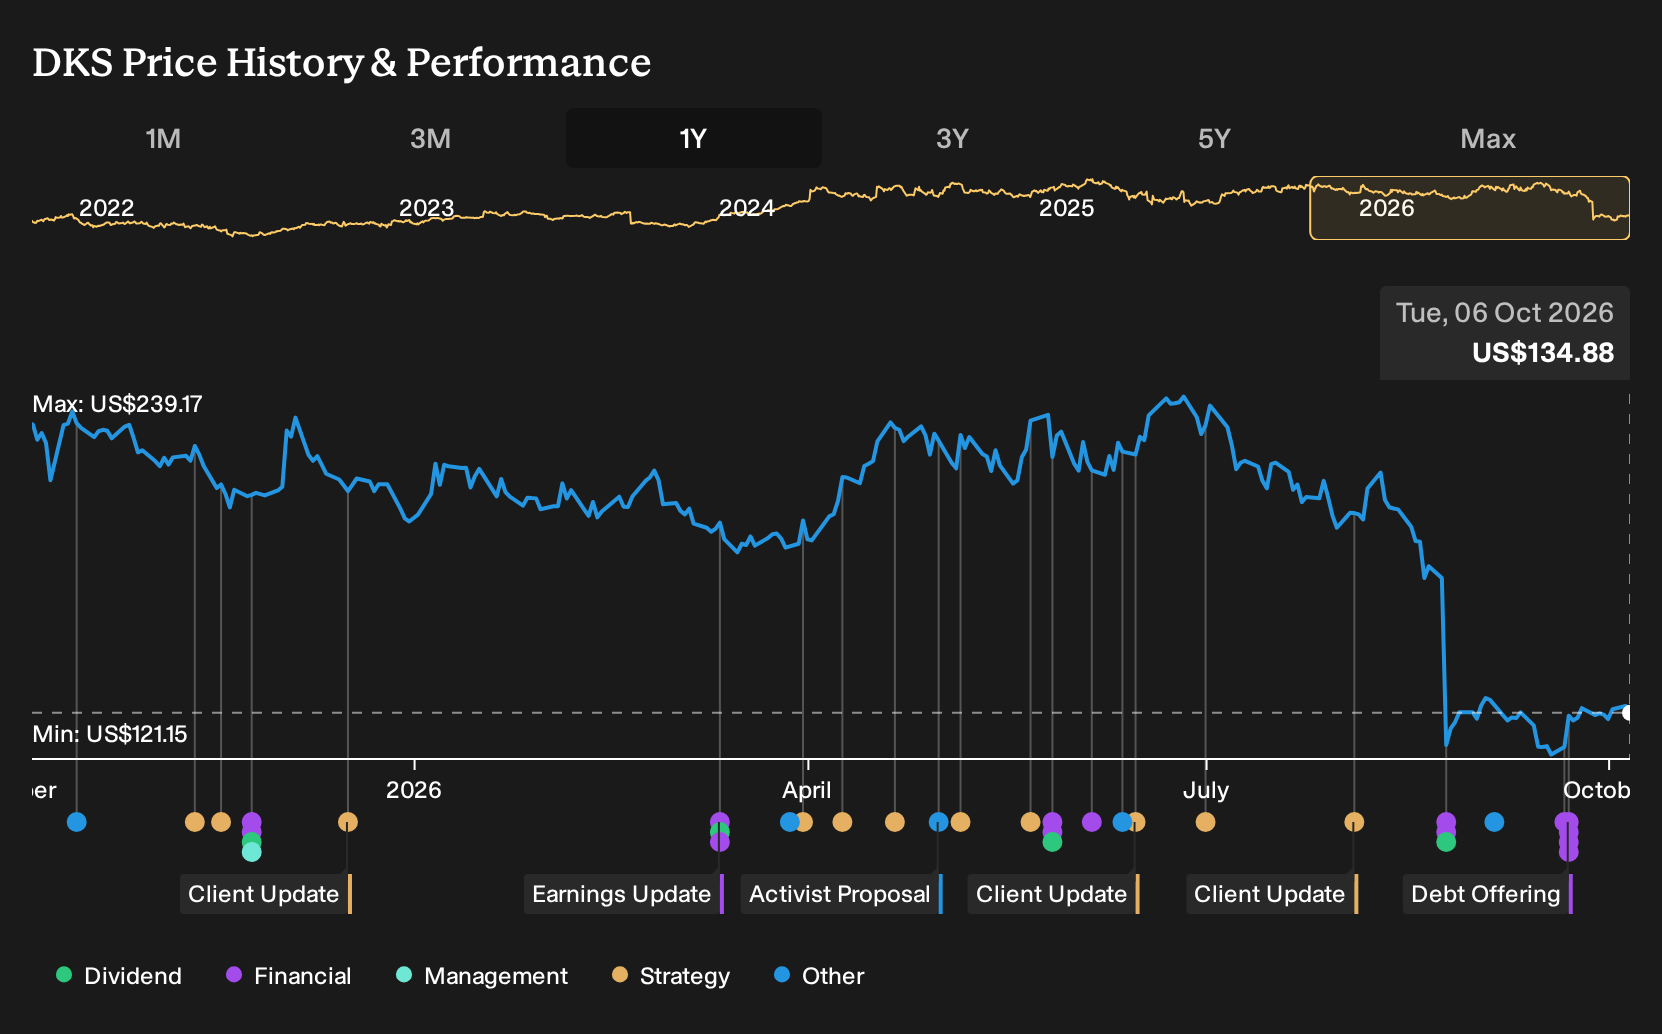
If you had backed DICK'S Sporting Goods on the bullish April 2025 view that health and sports trends would power omni channel retail, the outcome felt very different from the promise. For DICK'S Sporting Goods shareholders, the loss over the past year was 38.4%, including dividends. Class action filings and a sharp reaction to Foot Locker inventory issues now grab attention, but what, exactly, did the original revenue, margin and 2028 P/E assumptions miss about this acquisition risk?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
If the move has made DICK'S Sporting Goods harder to judge, start where the gap is still open and scan 27 high quality undervalued stocks.
What DICK'S Sporting Goods Investors Were Really Choosing Between
The shares cost US$230 at the start of the period, and anyone looking at DICK'S Sporting Goods had to decide which story felt more realistic.
The bullish narrative put fair value at US$273 and focused on health and sports participation trends, with expectations for revenue growth of 6.2% a year and profit margins rising to 8.9%, alongside a future P/E of 18.0x.
The bearish case set fair value at US$199 and accepted slower 3.0% revenue growth, with margins easing to 8.5% and a lower future P/E assumption of 15.1x, as House of Sport expansion and heavy spending increased perceived risk.
What The Results Changed For The DICK'S Sporting Goods Thesis
DICK'S Sporting Goods later disclosed that Foot Locker produced operating losses and ongoing inventory cleanup, while Q2 2027 results showed revenue at US$5.59b and net income at US$315m, with net margin falling from 10.5% to 5.6%. That combination challenged the bullish assumption that footwear expansion and acquisitions would reliably lift profitability, and it supported the more cautious case on margin risk.
The key lesson is to track whether an acquisition thesis rests on margin expansion. When you see raised guidance for synergies or higher profitability, check later filings for segment level losses, inventory write downs, and the direction of net margin.
What DICK'S Sporting Goods Price Now Asks You To Believe
DICK'S Sporting Goods trades at US$135 today, with this Narrative's Fair Value sitting above the current price based on its own assumptions about the business.
The Narrative leans on omni channel engagement, media and software platforms and consolidation benefits. A buyer now would need to believe that these strengths can outweigh footwear weakness and Foot Locker noise over time for the fall to look like opportunity rather than warning.
"The launch and ongoing growth of proprietary platforms like GameChanger (a high-growth, high-margin SaaS subscription for youth sports engagement) and the DICK’S Media Network (leveraging highly valuable ScoreCard loyalty data to create a new retail media profit stream) are set to meaningfully boost gross margins and support above-trend net earnings growth as these business segments scale."
One Narrative disagrees with today's price. → See where this Narrative says DICK'S Sporting Goods should trade
Looking Past DICK'S To Delivery
DICK'S Sporting Goods is wrestling with store traffic, inventory choices and margin pressure. You could also look one step away.
Every online order that skips a store still needs to arrive quickly for customers. That push has driven retailers toward dense logistics networks and higher automation.
One large digital retailer has spent years refining fulfillment, routing and last mile efficiency. It is also weaving AI into those systems to sharpen demand forecasts.
The result is a different bet from DICK'S Sporting Goods. You would be weighing store exposure against a model built on scale, data and delivery efficiency.
That argument has a Narrative and a number behind it. → See the company one Narrative values 76% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com