


The recent performance of the FTSE 100 and FTSE 250 indices, influenced by weak trade data from China, highlights ongoing global economic challenges impacting UK markets. In such an environment, identifying stocks trading below their estimated intrinsic values can offer potential opportunities for investors seeking value amid broader market fluctuations.
Top 10 Undervalued Stocks Based On Cash Flows In The United Kingdom
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Stelrad Group (LSE:SRAD) | £1.45 | £2.50 | 42% |
| Smiths News (LSE:SNWS) | £0.738 | £1.45 | 49.2% |
| Smith & Nephew (LSE:SN.) | £10.115 | £17.33 | 41.6% |
| Property Franchise Group (AIM:TPFG) | £4.175 | £7.33 | 43.1% |
| Premier Foods (LSE:PFD) | £1.88 | £3.13 | 39.9% |
| PayPoint (LSE:PAY) | £6.40 | £10.56 | 39.4% |
| LSL Property Services (LSE:LSL) | £2.55 | £4.55 | 43.9% |
| Gamma Communications (LSE:GAMA) | £10.91 | £20.18 | 45.9% |
| Distribution Finance Capital Holdings (AIM:DFCH) | £0.74 | £1.35 | 45.3% |
| Autotrader Group (LSE:AUTO) | £4.645 | £7.81 | 40.6% |
Here's a peek at a few of the choices from the screener.
Gamma Communications (LSE:GAMA)
Overview: Gamma Communications plc offers technology-based communications and software services to organizations of varying sizes across the UK, Europe, and internationally, with a market cap of £972.57 million.
Operations: Revenue segments for Gamma Communications include £136 million from Enterprise, £120.70 million from Germany SME, and £31.20 million from Other Europe.
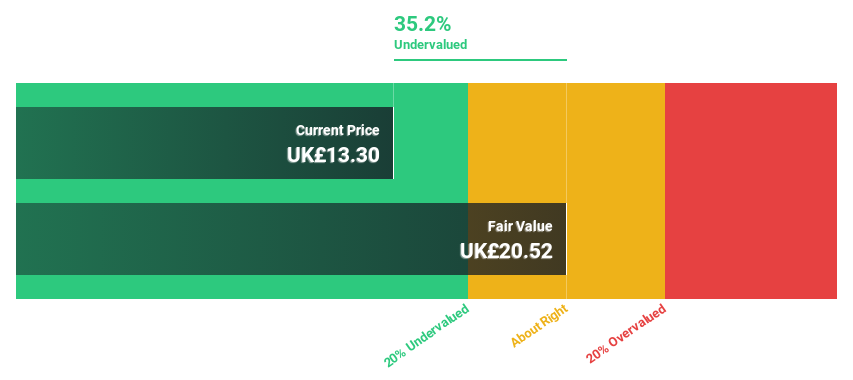
Estimated Discount To Fair Value: 45.9%
Gamma Communications appears undervalued based on cash flows, trading at £10.91 compared to an estimated future cash flow value of £20.18. Recent earnings show a growth in net income to £36.7 million, up from £32.4 million last year, despite revenue growth forecasts lagging behind the UK market average. The company completed a share buyback for £21.1 million and is subject to a pending acquisition by Epiris LLP valued at approximately £1 billion, potentially influencing its valuation further.
- The analysis detailed in our Gamma Communications growth report hints at robust future financial performance.
- Unlock comprehensive insights into our analysis of Gamma Communications stock in this financial health report.
Shell (LSE:SHEL)
Overview: Shell plc is a global energy and petrochemical company with operations across Europe, Asia, Oceania, Africa, the United States, and other parts of the Americas, and has a market cap of £209.04 billion.
Operations: Shell plc generates revenue through several segments: Marketing ($134.62 billion), Chemicals and Products ($131.76 billion), Renewables and Energy Solutions ($41.79 billion), Integrated Gas excluding Renewables and Energy Solutions ($48.98 billion), and Upstream excluding Integrated Gas & Oil Sands Mining ($44.23 billion).
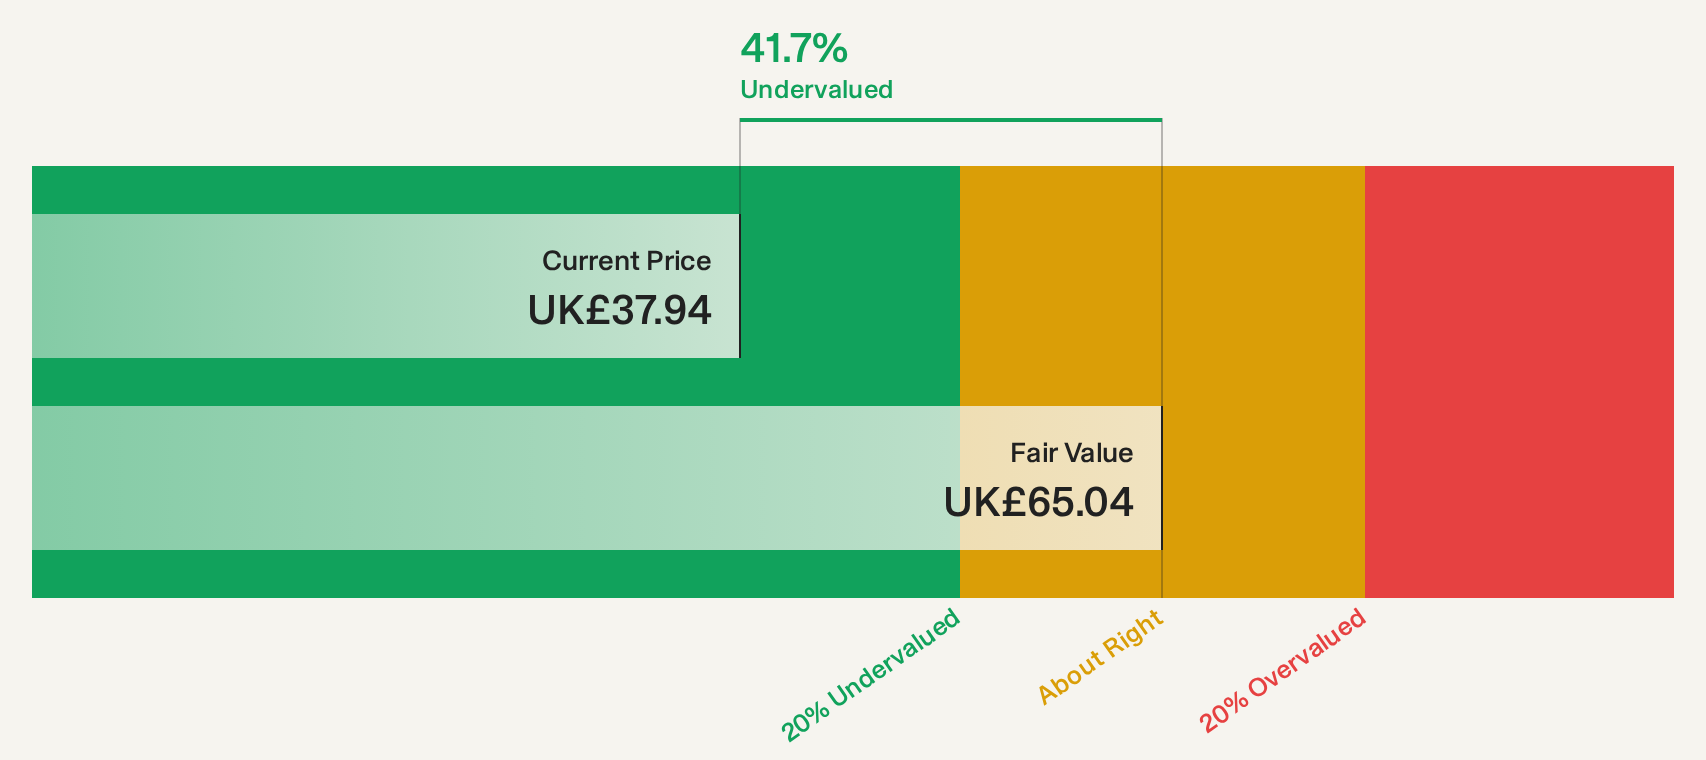
Estimated Discount To Fair Value: 26.6%
Shell is trading at £36.51, significantly below its estimated future cash flow value of £49.77, suggesting it may be undervalued based on cash flows. Despite a 90.9% earnings growth last year, forecasts indicate a decline in revenue and earnings over the next three years. Recent strategic moves include potential asset sales and a $3 billion share repurchase program, which could impact its financial positioning and shareholder value amidst an unstable dividend track record.
- Upon reviewing our latest growth report, Shell's projected financial performance appears quite optimistic.
- Take a closer look at Shell's balance sheet health here in our report.
Smith & Nephew (LSE:SN.)
Overview: Smith & Nephew plc is a global medical device company that develops, manufactures, markets, and sells medical devices and services in the UK, the US, and internationally with a market cap of approximately £8.51 billion.
Operations: Smith & Nephew's revenue is primarily derived from its Orthopaedics segment at $2.46 billion, Sports Medicine & ENT at $2.03 billion, and Advanced Wound Management (AWM) at $1.82 billion.
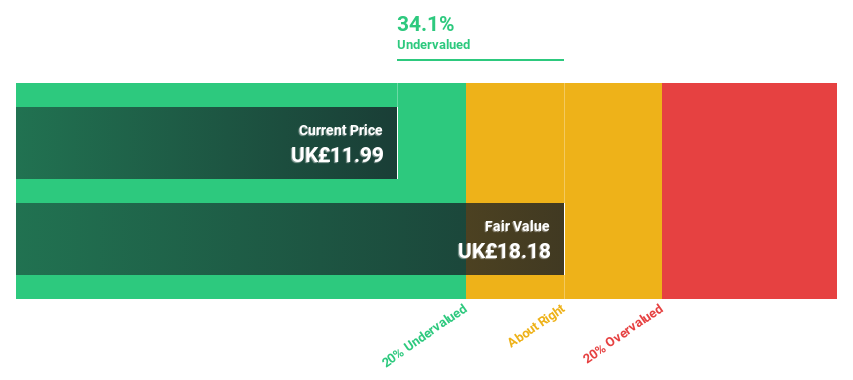
Estimated Discount To Fair Value: 41.6%
Smith & Nephew is trading at £10.12, below its estimated future cash flow value of £17.33, indicating potential undervaluation based on cash flows. Despite a high debt level, the company has been actively managing its financials through recent debt redemptions and tender offers. The commercial launch of innovative products like the CARTIHEAL Implant in Europe could bolster revenue growth prospects, which are forecasted to outpace the broader UK market at 5.2% annually.
- Our expertly prepared growth report on Smith & Nephew implies its future financial outlook may be stronger than recent results.
- Click to explore a detailed breakdown of our findings in Smith & Nephew's balance sheet health report.
Taking Advantage
- Click this link to deep-dive into the 27 companies within our Undervalued UK Stocks Based On Cash Flows screener.
- Are any of these part of your asset mix? Tap into the analytical power of Simply Wall St's portfolio to get a 360-degree view on how they're shaping up.
- Elevate your portfolio with Simply Wall St, the ultimate app for investors seeking global market coverage.
Contemplating Other Strategies?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com