


UL Solutions (ULS) just put AI and data center plumbing in sharper focus by naming Kelly Manthey as Chief AI & Digital Trust Officer and launching a liquid cooling certification program for high-density computing hardware.
Recent trading tells a mixed story for UL Solutions. The share price is up 5.31% over the past week but down 7.40% over 30 days and 20.81% over 90 days, while the 1 year total shareholder return has slipped 6.31%. The AI leadership hire and liquid cooling certification launch sit against that backdrop and may help explain why short term momentum has improved despite weaker performance over the year and a year to date share price return that is down 15.50%.
Scan this AI infrastructure theme even further by checking the hand picked 91 AI infrastructure stocks that are also plugged into data center demand and high density computing trends.
UL Solutions is pitching itself as a critical AI infrastructure partner, yet its shares have trended lower this year. Are investors getting a quality testing powerhouse at a fair entry price today?
Most Popular Narrative: 30% Undervalued
UL Solutions last closed at $68.37 while the most followed narrative pins fair value closer to $98.23, which frames the current pullback as a valuation gap rather than a verdict on the business.
UL Solutions' robust revenue growth, strong profitability, strategic investments, and stable income streams position the company for sustained success and future expansion.
See why 5 investors see UL Solutions as 30% undervalued.
Result: Fair Value of $98.23 (UNDERVALUED)
Still, the bullish case for UL Solutions has fault lines, including pressure on profit margins and tax changes that could weigh on earnings compared with prior years.
Find out about the key risks to this UL Solutions narrative.
Another Take On UL Solutions' Valuation
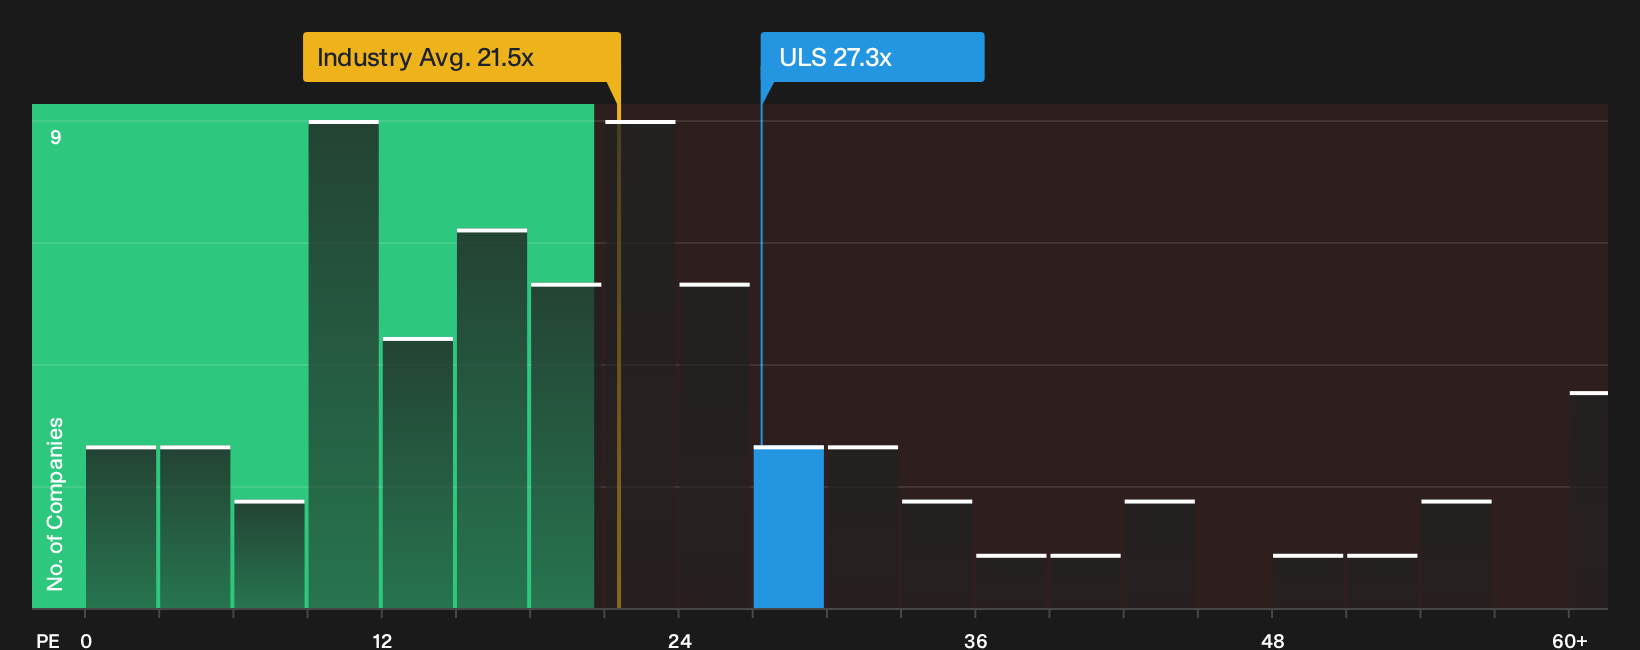
Analysts see upside for UL Solutions based on their fair value narrative, yet the current P/E of 27.3x tells a different story. That multiple sits above the US Professional Services industry on 21.6x, peers at 24.3x, and a fair ratio of 16x, which raises the question of how much optimism is already in the price.
To pressure test that premium against hard numbers, it helps to step through a simple valuation breakdown instead of relying on headlines alone. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around UL Solutions can be confusing. Treat this as your prompt to move quickly, dig into the data, and weigh both sides of the story using the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond UL Solutions?
If UL Solutions has your attention, do not stop here. Fresh ideas often come from comparing it with other high quality opportunities across different angles.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (25 results) that could help anchor your portfolio.
- Hunt for mispriced quality by reviewing the 27 high quality undervalued stocks before the crowd catches on to those opportunities.
- Prioritize stability and income potential by checking the 8 dividend fortresses that offer higher yields than many investors realize.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com