


Hilton Worldwide Holdings (HLT) just grew its Hawaiʻi footprint with Hale Hokuala Kauaʻi, a 210 room Curio Collection resort that emphasizes cultural programming, wellness amenities, and group friendly event space.
For context, Hilton Worldwide Holdings shares finished the latest session at US$322.61, with a 1-day share price return of 2.05% and a 30-day share price return of 3.67%. The 1-year total shareholder return of 24.98% and 3-year total shareholder return of about 2x suggest momentum that has built over time rather than faded recently.
Scan for other travel and leisure operators showing similar momentum to Hilton Worldwide Holdings by reviewing the hand picked 27 high quality undervalued stocks with stronger balance sheets and cash flows.
Hilton Worldwide Holdings shares have already delivered strong multi year gains. Yet the latest Hawaiʻi addition and fresh price strength leave a different question hanging: Is most of the upside now in the rearview, or not?
Most Popular Narrative: 9% Undervalued
On the most followed view of Hilton Worldwide Holdings, a fair value of $353 sits above the last close at $322.61, which puts the Hale Hokuala opening into a much bigger system wide expansion story.
The rapid expansion of Hilton Worldwide Holdings' development pipeline, now at a record 541,000 rooms with almost half under construction across more than 130 countries, is cited to support the view that continued 6% to 7% net unit growth can feed higher fee revenue and earnings over the next several years.
See why 15 investors see Hilton Worldwide Holdings as 9% undervalued.
Result: Fair Value of $353 (UNDERVALUED)
Still, sustained RevPAR pressure in regions like the Middle East and China, along with renovation related EBITDA drag at key owned hotels, could challenge the Hilton Worldwide Holdings narrative.
Find out about the key risks to this Hilton Worldwide Holdings narrative.
Another View: Rich Multiples On Hilton Worldwide Holdings
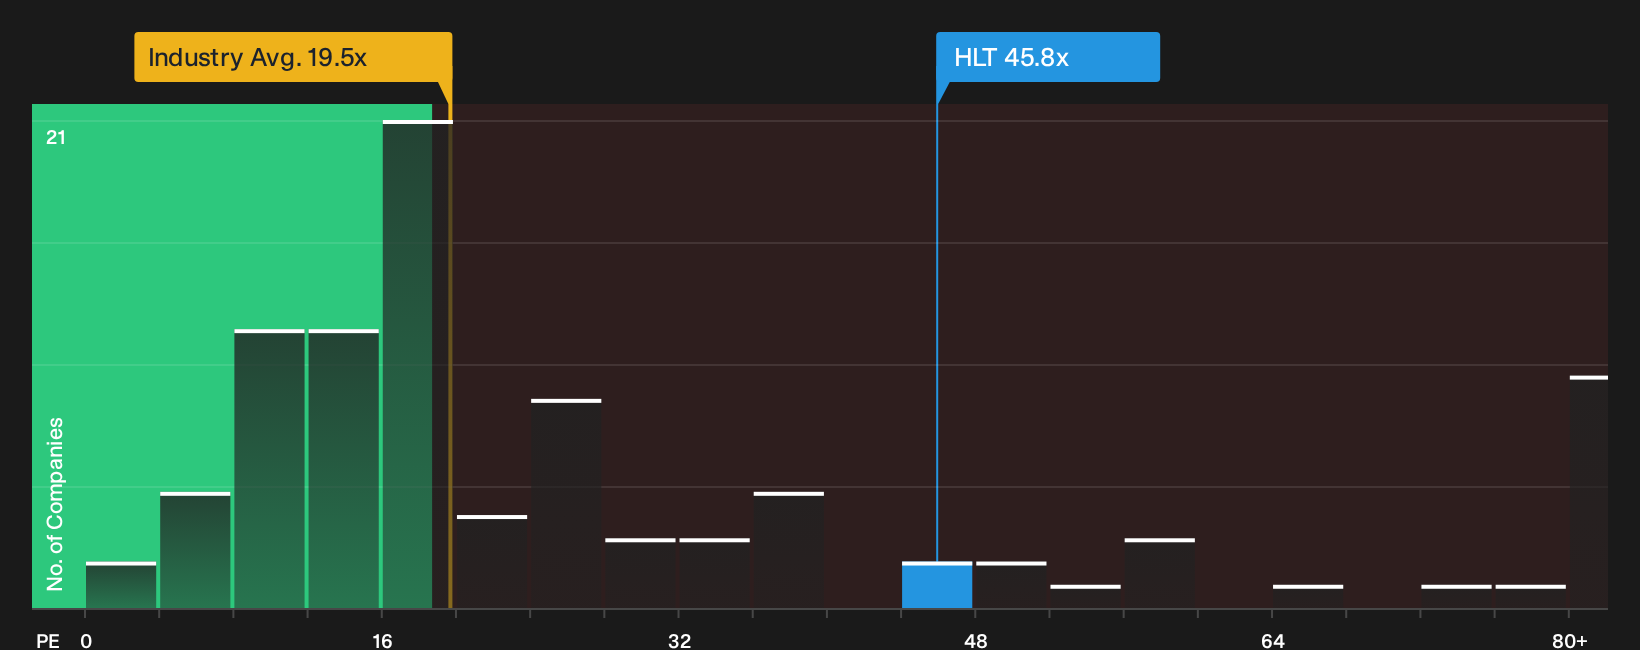
The first story paints Hilton Worldwide Holdings as about 9% undervalued on fair value estimates. A different lens using the current P/E of 45.8x tells a less comfortable story. That figure sits well above the US Hospitality group at 19x and above a fair ratio of 27.2x.
In plain terms, investors are paying a much higher price for each dollar of earnings than both peers and the fair ratio suggest. That can work if growth and execution line up with expectations. It also raises the question of how much room is left if sentiment cools or earnings slip.
See what the numbers say about this price in more detail in our valuation breakdown, then decide which framework you trust more for Hilton Worldwide Holdings: the upbeat fair value or the richer earnings multiple signal See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Hilton Worldwide Holdings so far. If you want to move quickly and base your own call on the full picture, start with the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Hilton Worldwide Holdings?
If the Hilton Worldwide Holdings story has your attention, do not stop here. Broader opportunity often hides in places the headline momentum never touches.
- Target resilient potential by reviewing a 31 resilient stocks with low risk scores to help you focus on companies with steadier risk profiles when markets feel unpredictable.
- Hunt for quality at a better entry point by scanning the 27 high quality undervalued stocks that highlights businesses with stronger fundamentals than their current pricing may suggest.
- Build a portfolio with more than just growth flair by checking the 8 dividend fortresses that points you toward companies combining income potential with disciplined payout histories.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com