


- ICF International reported that in August 2026 it secured two new multiyear work orders under Los Angeles County's Energy Support Services Master Agreement, with a combined ceiling value of about US$70 million tied to SoCalREN public sector energy efficiency programs.
- The expanded remit gives ICF International broader, end-to-end responsibility across engineering, customer targeting, marketing, financing, and construction management. This deepens its commercial and local government energy efficiency footprint beyond existing residential and agricultural portfolios.
- We will examine how ICF International's investment narrative is influenced by these added SoCalREN implementation duties and the multiyear contract ceiling.
Scan beyond ICF International and size up other contractors benefiting from the energy transition with our curated 44 power grid technology and infrastructure stocks as grid reliability spending gains more attention.
ICF International Investment Narrative Recap
To own ICF International, you need to believe the consulting and implementation engine can keep tilting toward commercial energy, state and local, and international work while federal softness is managed. The SoCalREN awards speak directly to that mix shift. They deepen exposure to grid efficiency and resilience programs that already underpin a large commercial energy revenue base.
In the near term, the key swing factor is whether new contracts convert into backlog growth after a period of pressure and softer recent sales trends. The biggest risk remains federal funding delays, which have already weighed on that segment. If federal awards stay slow and book to bill does not improve, execution elsewhere has less room for error.
The fresh SoCalREN work ties neatly into one of the clearest catalysts already in play. Rapid demand for energy efficiency, electrification, and grid resilience has been associated with commercial energy revenue of about US$550 million in 2025 and double digit organic growth expectations in 2026. The Los Angeles work orders extend that theme into public sector infrastructure across a wide service territory.
For you as a shareholder, the operational question is whether ICF International can consistently turn this kind of grid focused award into higher margin commercial style delivery while federal revenues remain under pressure. If contracts like SoCalREN feed into the US$9.3b pipeline and lift backlog trends, they may help offset the risk from volatile quarters that have already hit sentiment.
ICF International Consensus Forecasts and Valuation Setup
ICF International's current analyst narrative ties the SoCalREN contract wins into a broader set of expectations around growth, profitability, and valuation that runs out to the end of the decade. The key moving parts for you are the pace of projected revenue expansion, the shift in profit margins, and the earnings profile that analysts are using to anchor their price targets.
Analysts are working off an assumed 7.1% annual top line growth rate over the next three years, paired with margin forecasts that move from 4.9% today to 6.7% by 2029. On the earnings line, the consensus view points to US$88.5 million of profit today rising to US$149.6 million by 2029, which is an increase of about US$61 million. That path implies a company that is not only growing its revenue base but also converting a larger share of each dollar of sales into net income.
On their numbers, ICF International would reach US$2.2b of revenue and US$149.6 million of earnings in 2029. This setup also bakes in a P/E multiple of 14.9x on those future earnings, down from 16.6x today and below the current 21.3x level cited for the wider US Professional Services group. For you, the question is whether a lower future multiple on higher earnings feels reasonable given the mix toward commercial energy contracts like SoCalREN and other nonfederal work.
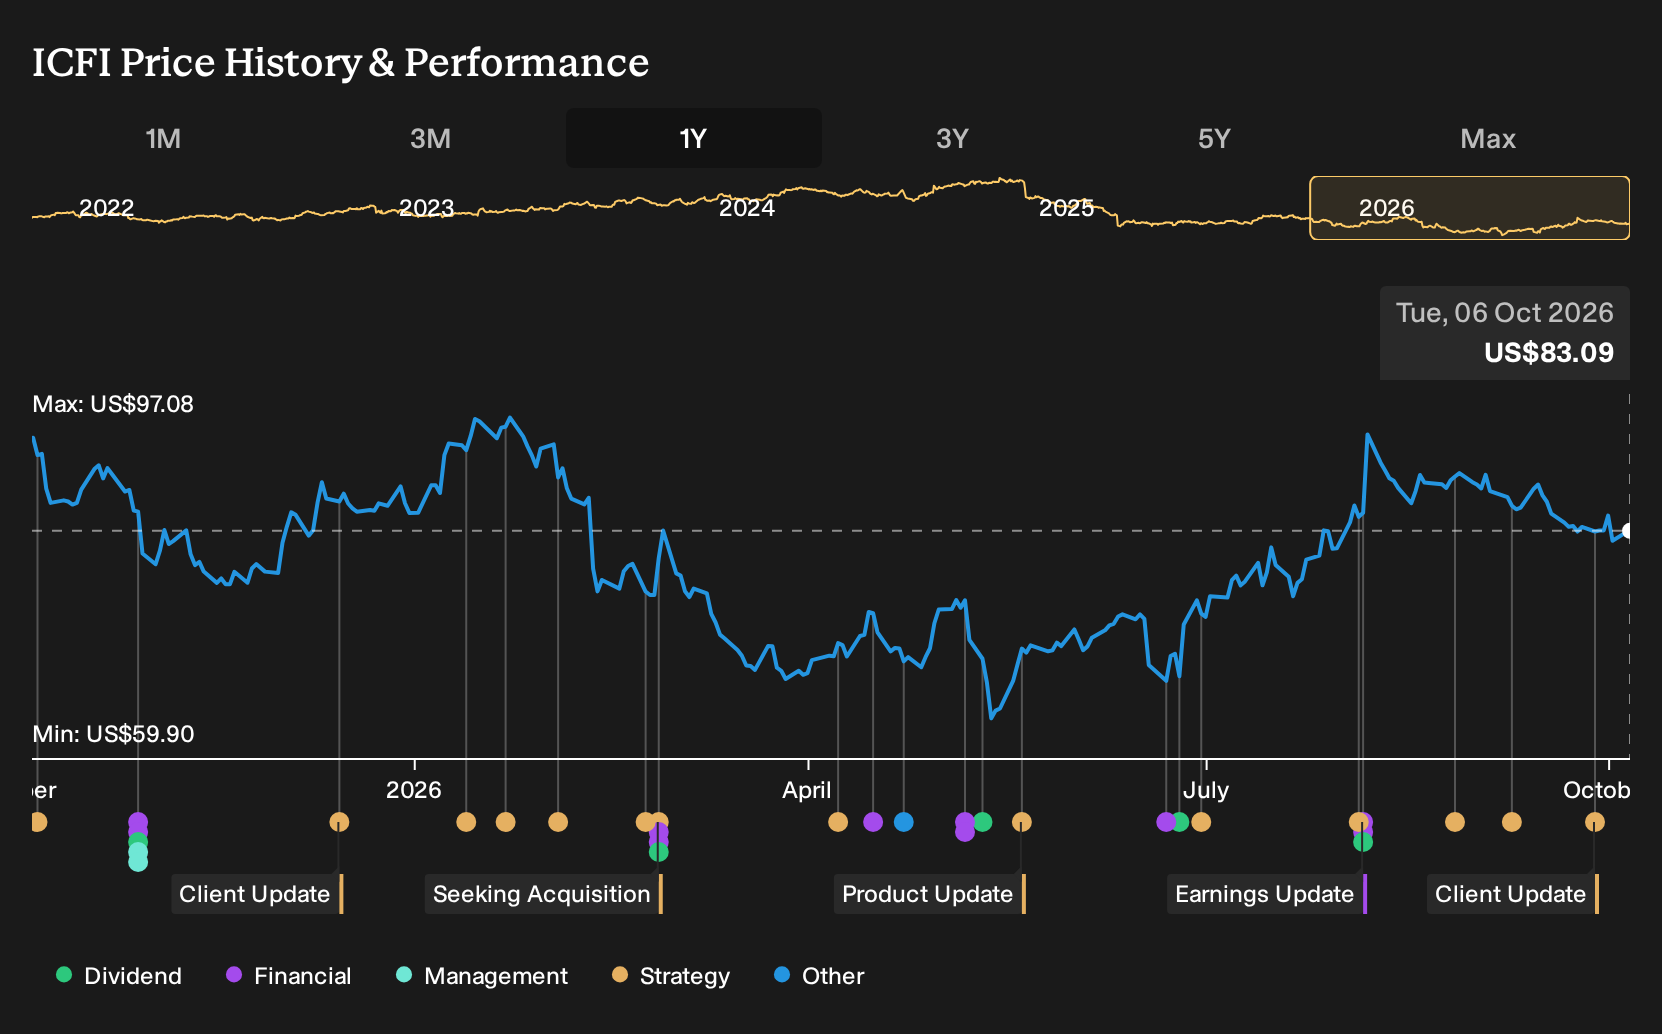
The same models assume the share count shrinks by 2.72% per year over the next three years, which would help earnings per share even if operating trends come in closer to the middle of the range. Against a spot share price of US$81.86, the consensus target of US$107.25 sits 23.7% higher. Individual analyst targets span from US$80.00 up to US$124.00. That spread signals some disagreement around how reliably ICF International can translate the current contract pipeline into the revenue, margin, and earnings profile implied for 2029.
ICF International's outlook ties to revenue of US$2.2b and earnings of US$149.6 million by 2029, built on 7.1% yearly revenue growth and an earnings increase of about US$61 million from US$88.5 million today.
Uncover why ICF International's fair value indicates a 29% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on ICF International leans heavily on backlog risk. That bearish camp saw only mid single digit progress, with revenue assumptions of about US$2.3b and earnings of roughly US$152.8 million by 2029. You can read that as a much harsher multiple cut, even before the SoCalREN news is incorporated into their models.
Explore another ICF International fair value estimate, including one that suggests it could be worth just $99.72!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ICF International research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for ICF International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ICF International's overall financial health at a glance.
Looking for more investment ideas beyond ICF International?
If you want to stress test your thesis on ICF International against other opportunities, the Simply Wall St Screener lets you filter by quality, valuation, income profile, and balance sheet strength in a few clicks.
- For investors who care most about resilience and capital preservation, start with a 31 resilient stocks with low risk scores that have historically shown steadier risk profiles.
- If your focus is on dependable income streams, scan through a curated set of 8 dividend fortresses that may suit a yield focused approach.
- When you want to get in early on underfollowed stories with solid fundamentals, the 19 high quality undiscovered gems can help surface ideas that often slip past broader market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com