


Independence Realty Trust (IRT) drew fresh attention after its recent share price performance, with the stock closing at US$14.73 as short term and year to date returns moved lower.
For Independence Realty Trust, the latest 1 day share price return of 0.07% comes after a weaker patch, with the 30 day share price return down 8.45% and the year to date share price return down 16.31%. The 3 year total shareholder return of 17.67% contrasts with a 5.16% decline over the past year, which points to fading momentum in the near term following a stronger multi-year run.
Look beyond Independence Realty Trust's recent pullback and identify alternatives with resilient fundamentals using our curated list of list of solid balance sheet and fundamentals (25 results)
After that slide in Independence Realty Trust, the debate now hinges on whether the lower price still compensates you for the risks you are taking or if the odds have tilted away from new buyers.
Most Popular Narrative: 23% Undervalued
Independence Realty Trust is currently priced at $14.73 compared with a widely followed fair value estimate of $19.14. This frames the recent share price weakness as a potential valuation gap rather than just fading sentiment.
The tapering of new multifamily supply and a 43% year over year reduction in deliveries projected for IRT's Sun Belt focused markets in 2026 positions the company for a reacceleration of rent growth and stronger occupancy as demand continues to outpace incoming inventory, which should drive future revenue and NOI growth. Sustained strong demographic tailwinds including millennial and Gen Z household formation and Sun Belt migration are reflected in rising lead and tour volumes and high retention rates, supporting expectations for high occupancy and steady rent roll, which directly underpin future top line revenue and stabilized net operating margins.
See why 0 investors see Independence Realty Trust as 23% undervalued.
Result: Fair Value of $19.14 (UNDERVALUED)
Still, the narrative around Independence Realty Trust can be knocked off course if Sun Belt oversupply keeps rent growth muted, or if asset sales fail to deliver the expected returns.
Find out about the key risks to this Independence Realty Trust narrative.
Another View on Independence Realty Trust's Valuation
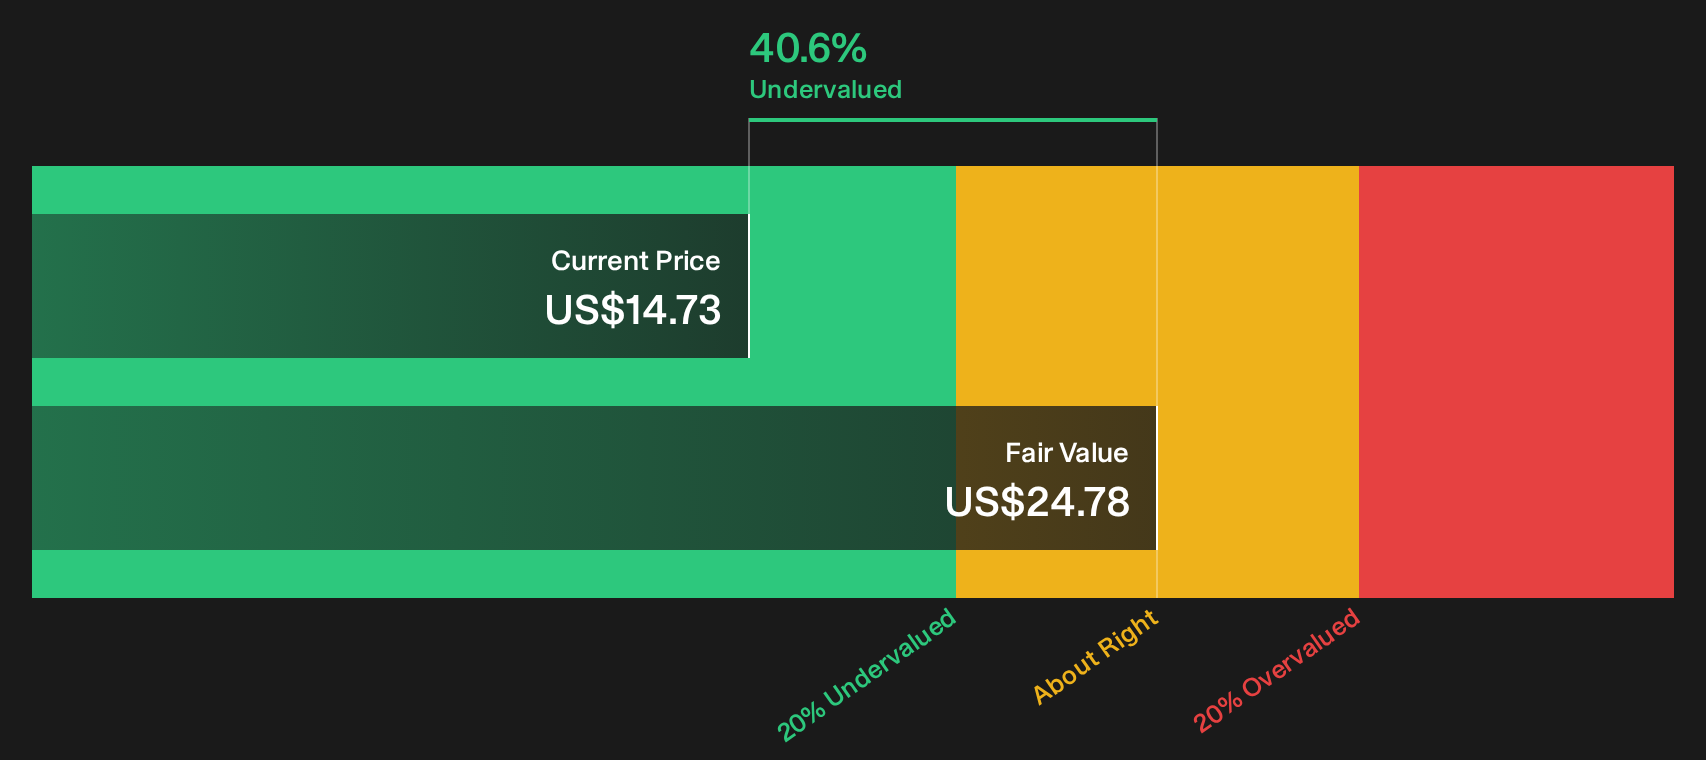
Our DCF model points in the same direction as the analyst narrative but with a different magnitude. On this approach, Independence Realty Trust screens as undervalued, with a fair value estimate of $24.78 versus the current $14.73. If both models lean positive, the question becomes which set of assumptions you trust most.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If this mix of optimism and concern around Independence Realty Trust feels familiar, treat it as your cue to review the numbers yourself, weigh both sides of the argument, and then use the full breakdown of 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Independence Realty Trust?
If Independence Realty Trust has your attention, do not stop at one ticker. Use the Simply Wall St screener to compare, contrast, and pressure test fresh ideas.
- Target dependable cash generators by scanning companies with strong balance sheets and solid fundamentals using our curated list of solid balance sheet and fundamentals (25 results).
- Hunt for potential value opportunities by focusing on businesses that our models flag as attractively priced through the 27 high quality undervalued stocks.
- Build a short list of under-the-radar opportunities by zeroing in on financially sound smaller companies via the 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com