


- Citigroup expanded its digital payments push by rolling out Citi Token Services into Japan and the UAE, going live on Swift’s multi market instant payments solution, and deepening its Coinbase partnership so institutional clients can accept stablecoin payments with automatic conversion to fiat.
- These moves shift more transaction flows onto Citi controlled rails, which can deepen client reliance on its services franchise and support fee based and interest linked income streams tied to higher cross border and real time payment volumes.
- We will examine how Citigroup’s investment narrative is influenced by this push into tokenized deposits and cross border instant payments.
Citigroup Investment Narrative Recap
To own Citigroup, you need to believe the global services engine, digital payments build out and AI driven efficiency push can translate into durable returns on tangible equity, even as competition from fintech and stablecoin platforms intensifies. The near term swing factor sits in Services transaction volumes and credit quality in U.S. consumer, neither of which this week’s announcements appear to change materially.
The biggest risk still sits in regulatory and conduct exposure plus any hit to the perceived value of Citi’s cross border payments franchise if rivals scale faster. Recent bond issuance and the funding mix tweaks around it look incremental for now, more about balance sheet housekeeping than a new earnings driver.
The most interesting recent item alongside the tokenization news is the cluster of senior and subordinated fixed income offerings, spanning short, medium and very long dated tenors, with both fixed and floating coupons. These add to Citigroup’s flexibility in matching asset duration, supporting liquidity and meeting regulatory capital and total loss absorbing capacity requirements over time.
For you as a shareholder, the question is whether ongoing issuance at these coupons still supports the equity story built on capital return, Banamex capital release and Services growth. If funding costs grind higher, that could pressure net interest income and blunt some benefit from higher volume in tokenized payments, so execution on pricing and balance sheet management remains central to the catalyst path.
Citigroup's current narrative assumes revenue growth of 9.5% per year, with earnings today of US$16.5b and a consensus forecast for earnings of US$22.3b by 2029. This implies an earnings increase of about US$5.8b as part of a wider profile that also targets US$107.2b of revenue in the same year.
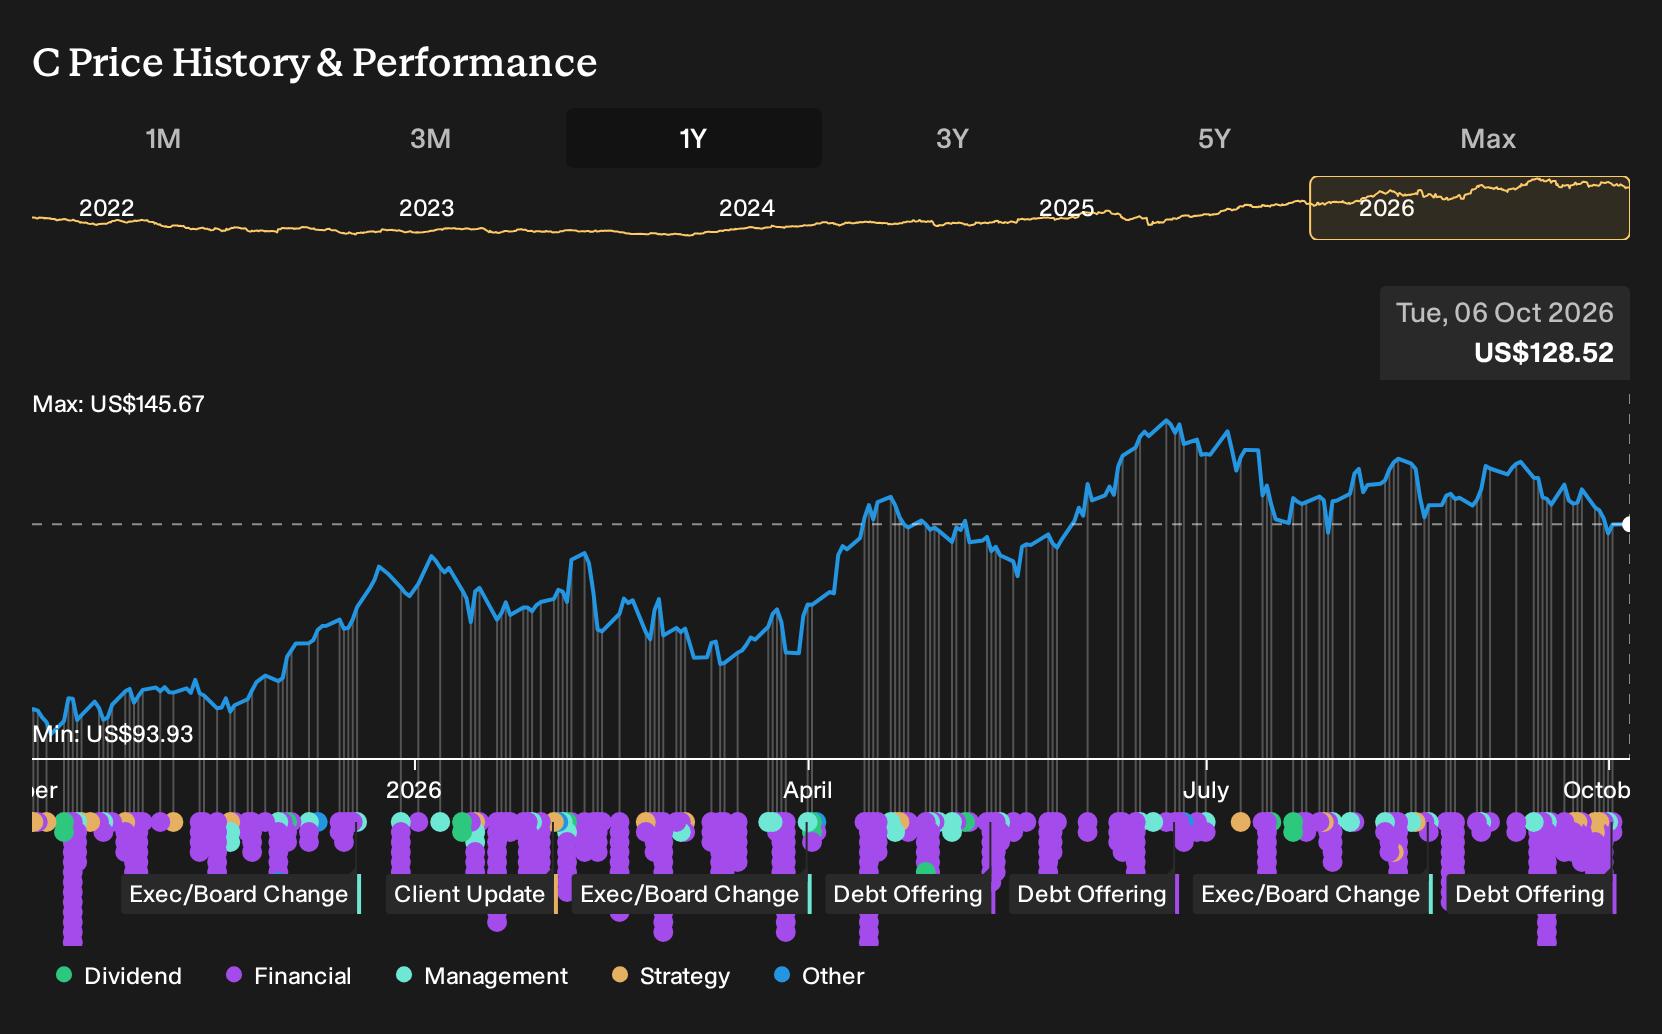
Uncover how Citigroup's fair value indicates a 21% potential upside to its current price. This potential could narrow quickly if sentiment catches up.
Exploring Other Perspectives
One catalyst the most optimistic analysts keep circling is how far Citigroup can push Services earnings if tokenized and instant payments really scale. Before this news, that group was already penciling in about US$112.3b of revenue and US$24.8b of earnings by 2029. You may see those forecasts as punchy, yet they highlight how far opinions can stretch. Use this tokenization and Coinbase news as a prompt to compare that upbeat view with your own expectations and decide which narrative feels closer to your reality.
Explore 4 other Citigroup fair value estimates, including one that suggests as much as 51% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A useful starting point for your Citigroup research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Citigroup. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to evaluate Citigroup's overall financial health at a glance.
Looking For More Investment Ideas Beyond Citigroup?
If Citigroup’s tokenization push has sharpened your interest in financial infrastructure, it can help to line it up against other potential opportunities that share similar themes in quality, balance sheet strength or valuation.
- If you want ideas that combine strong financial footing with room to run, scan our hand picked 19 high quality undiscovered gems in adjacent sectors to see what else might deserve a spot on your watchlist.
- If capital preservation matters as much as upside potential, filter for steadier businesses using our curated 31 resilient stocks with low risk scores that screen for resilient balance sheets and lower risk profiles.
- If you care about fundamentals and staying power, build a comparison set using the list of solid balance sheet and fundamentals (25 results) to spot companies with financial structures that can support their long term plans.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com