


- BorgWarner has been flagged by analysts as trading on a P/E of 9.26 versus an industry average of 16.81, which positions the auto supplier as comparatively lowly valued given its current earnings profile.
- The blend of combustion, hybrid, and electric vehicle technologies across BorgWarner’s diversified segments gives that low valuation particular weight, because investors are getting exposure to both legacy and electrified drivetrains at the same time.
- We will now look at how BorgWarner’s low P/E multiple, alongside its earnings outlook, could influence the broader investment narrative.
What Is BorgWarner's Investment Narrative?
The big picture for BorgWarner is simple. You have to believe the auto sector keeps needing a mix of combustion, hybrid, and electric drivetrains, and that this manufacturer can keep winning business across all three. The recent focus on its low P/E and value rating reinforces that the market is still pricing BorgWarner as a cyclical auto supplier rather than as a differentiated powertrain platform. That affects sentiment more than day to day operations, but it can shape how much flexibility management has when allocating capital.
In the short term, the real swing factors stay the same: execution on large OEM programs, the cost of ramping PowerDrive and Battery & Charging Systems, and how aggressively the group invests against its US$14.3b revenue base. Earnings forecasts, the A grade on value, and analyst agreement on upside targets indicate that expectations are already oriented toward solid but not explosive growth. Risks around return on equity, capital intensity, one off items in recent results, and funding mix still hang over the story.
Even so, before leaning too hard into the value angle, there is a structural issue in the BorgWarner setup that could still...
There's only one way to know the right time to buy, sell or hold BorgWarner. Head to Simply Wall St's company report for the latest analysis of BorgWarner's Fair Value.
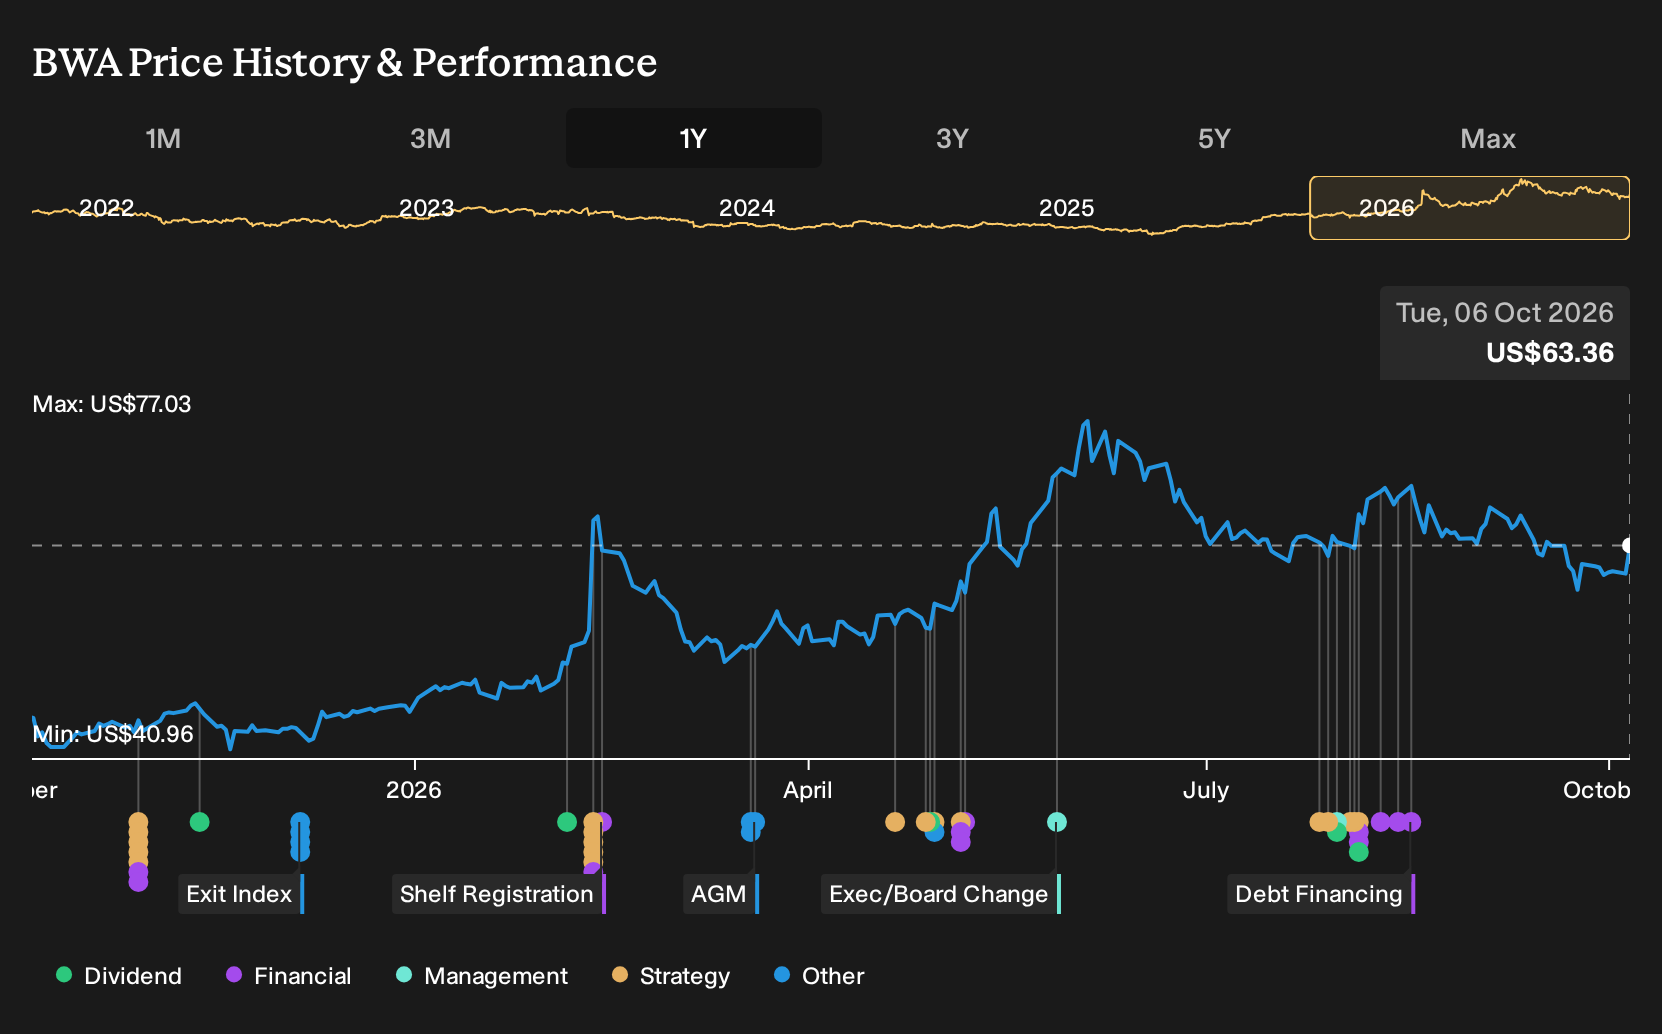
Exploring Other Perspectives
One alternative angle on BorgWarner focuses on the turbine generator rollout. The most cautious analysts worry that any delay in those data center and microgrid projects could cap the planned US$300 million first year contribution. They were only penciling in about 2.0% annual revenue growth and earnings of US$969.5 million by 2029, so their story is much more restrained. Those forecasts were all set before this latest valuation news, so some of these viewpoints may change as fresh information becomes available.
Explore 3 other BorgWarner fair value estimates, including one that suggests it could be worth just $81.53!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your BorgWarner research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for BorgWarner. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BorgWarner's overall financial health at a glance.
Looking For More Investment Ideas Beyond BorgWarner?
If you want to stress test the BorgWarner thesis against a wider opportunity set, it helps to scan other companies with different risk and income profiles using the Simply Wall St Screener.
- For investors who prioritize stability and lower downside risk, review a curated 31 resilient stocks with low risk scores that may help you balance out more cyclical holdings in your portfolio.
- If you care about resilience and financial strength, compare BorgWarner with a list of solid balance sheet and fundamentals (25 results) that can support growth plans and potential downturns.
- For those hunting for mispriced opportunities, check a 19 high quality undiscovered gems that the wider market may not be paying close attention to yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com