


AT&T shares have delivered a strong 87.7% gain over the past three years, so the key issue now is whether that trajectory is properly reflected in what the business earns today. With the company pushing hard on fiber buildouts and dealing with the financial impact of a major data breach settlement, the current share price of US$24.43 naturally raises the question of how solid the earnings base behind it really is.
- The 87.7% three year return puts real weight on the question of whether AT&T's current earnings can support that kind of rerating in the stock.
- The new fiber joint venture with Global Infrastructure Partners and CPP Investments, along with a multi year Corning supply deal, can reshape how quickly AT&T converts heavy network spending into future earnings power and cash generation.
- The analysts covering AT&T have run their own numbers. See what analysts think AT&T's shares could be worth.
The stock's next move may depend on whether AT&T's current earnings profile can justify where the shares trade today.
If you want a wider set of ideas built around similar earnings focused questions, a curated list of 27 high quality undervalued stocks.
Does AT&T Look Undervalued on Earnings?
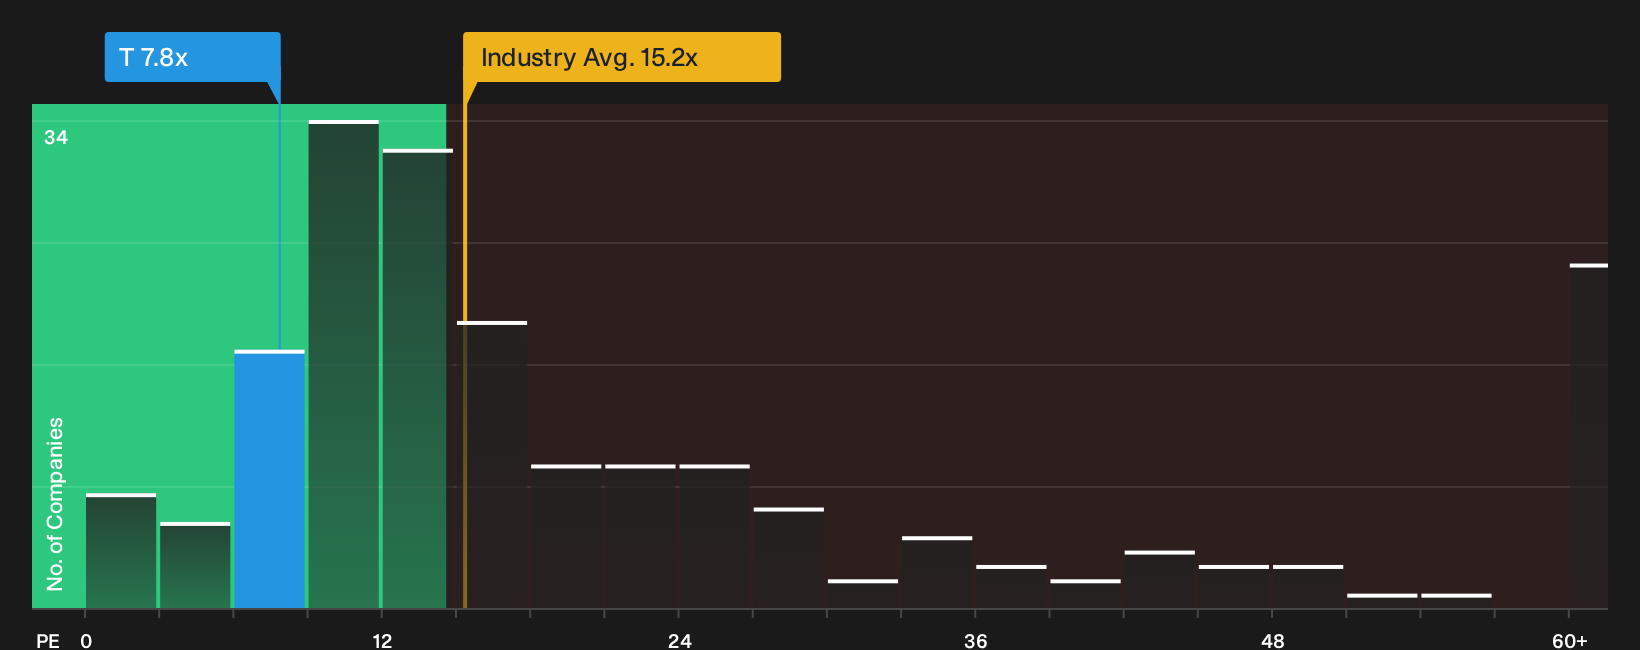
The P/E ratio is useful for AT&T because earnings still drive much of how investors frame telecom valuations. AT&T trades on a P/E of about 7.8x, compared with a Telecom industry average near 15.2x and a peer group around 11.7x. That puts the stock on a noticeably lower earnings multiple than both its sector and closer rivals.
The fair P/E level implied by the valuation model sits above where AT&T trades today, so the current 7.8x screens as undervalued on this framework. Because the new fiber joint venture with Global Infrastructure Partners and CPP Investments concentrates attention on the long term economics of AT&T's network build, the gap between the present multiple and that implied fair level is important for anyone weighing how much of that story is already in the price. Explore the numbers behind AT&T's P/E valuation.
The AT&T Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for AT&T pick up where this valuation puzzle leaves off. They spell out which expectations on growth, profitability and earnings would need to hold for the stock to be worth meaningfully more or less than it is today on the market. Each narrative links a fair value estimate to a specific storyline about AT&T's potential catalysts and key risks, so you can track over time which interpretation of the business appears to be gaining traction on the Community page.
Community views on AT&T are now split between potential upside from fiber execution and concern that capital demands and integration work already justify the current valuation.
Bull case: 16% undervalued
"Retirement of legacy copper and wireline infrastructure is moving forward, with plans to eliminate roughly US$6b of costs tied to copper networks…"
Discover why this Narrative puts AT&T at 16% undervalued.
Bear case: 12% overvalued
"The current valuation implies that AT&T's share price already reflects guided double digit EPS growth through 2028, disciplined capital returns of $45 billion over three years…"
Explore why this Narrative puts AT&T at 12% overvalued.
One more thing about AT&T that deserves a closer look
AT&T's valuation story is only part of the picture, because recent checks on the business have raised specific concerns that investors may want to examine before relying too heavily on the numbers. Take a closer look at 4 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com