


Wyndham Hotels & Resorts (WH) is pushing deeper into sports-themed travel after expanding its partnership with Travel + Leisure Co. to grow the Sports Illustrated Resorts hotel platform across traditional lodging and mixed-use projects.
The latest Sports Illustrated Resorts partnership lands as Wyndham Hotels & Resorts trades at US$72.65, with the share price up 2.01% over the past day but down 5.85% across the last 90 days. The 1 year total shareholder return has declined 6.59%, while the 3 year total shareholder return is up 10.87%, pointing to stronger momentum over a longer holding period than in recent months.
Scan how Wyndham Hotels & Resorts compares with other potential travel and leisure opportunities by checking our curated list of 19 high quality undiscovered gems that may still be flying under most investors' radar.
Recent weakness and a richer three year track record put Wyndham Hotels & Resorts in an awkward middle ground. Has most of the upside already played out, or does the current valuation still leave meaningful room on the table?
Most Popular Narrative: 26% Undervalued
Against a last close of $72.65, the most followed narrative pegs Wyndham Hotels & Resorts at a fair value of $97.59, framing the current price as a material discount that hinges on fee based earnings and technology execution actually coming through.
Record net room growth and a development pipeline of about 261,000 rooms with roughly a 30% FeePAR premium over the current system create ongoing mix uplift toward higher fee hotels, which can support faster growth in fee-related revenue and EBITDA for Wyndham Hotels & Resorts.
Find out how 2 investors see Wyndham Hotels & Resorts as 26% undervalued.
Result: Fair Value of $97.59 (UNDERVALUED)
Still, the narrative around Wyndham Hotels & Resorts could crack if U.S. RevPAR weakens for a longer period or if legal and reputational issues escalate materially.
Find out about the key risks to this Wyndham Hotels & Resorts narrative.
Another View on Wyndham Hotels & Resorts Valuation
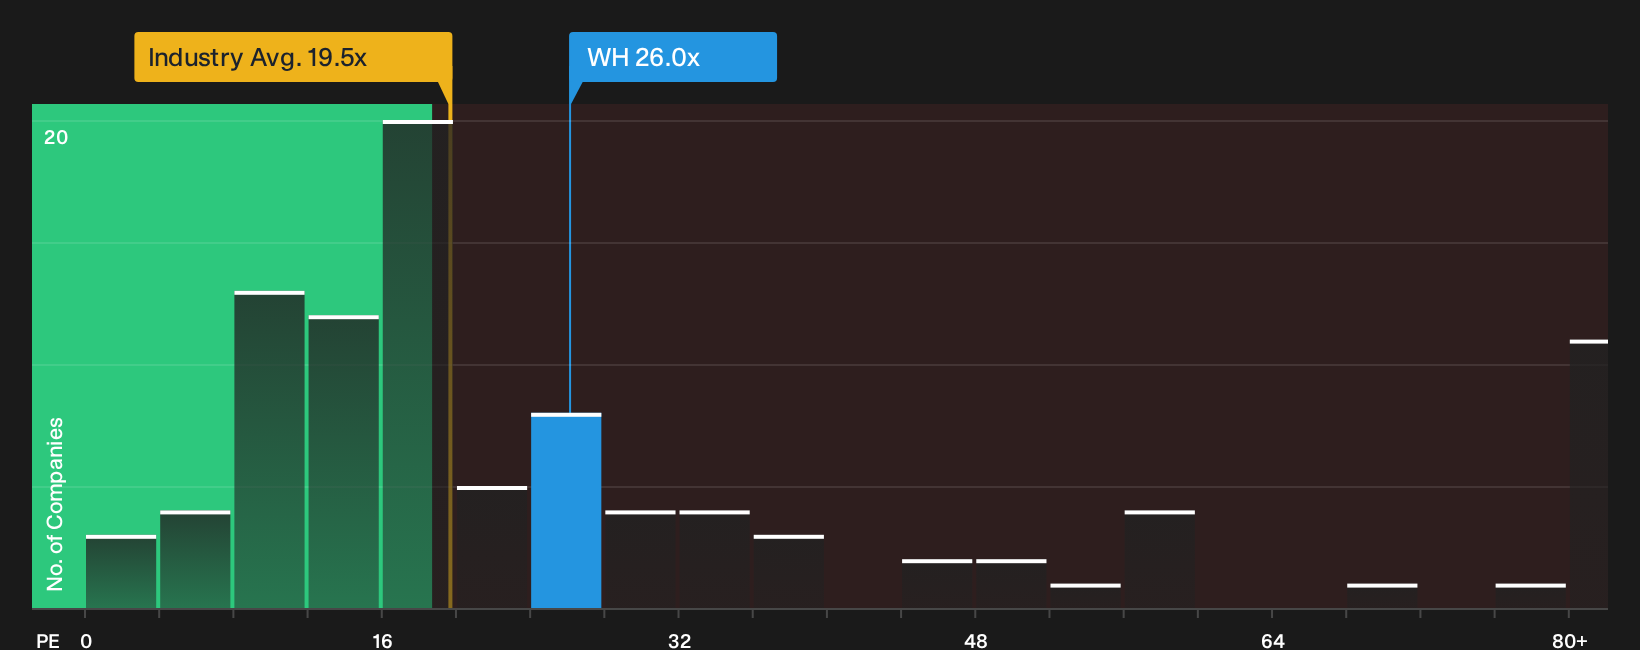
The fair value story for Wyndham Hotels & Resorts looks less one sided once the P/E ratio enters the frame. The stock trades on 26x earnings, which is richer than the US Hospitality sector at 19x and above the fair ratio of 21.2x that the regression suggests the market could move toward.
Peers as a group sit on a loftier 39.7x P/E, so Wyndham screens cheaper against close comparables yet still prices in more optimism than the wider industry. For investors weighing the 26% undervalued narrative against this higher than fair ratio, the real question is which crowd they trust more, analysts or the broader market.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Wyndham Hotels & Resorts valuation and sentiment only matter if you test them yourself, so move quickly, review the full data and weigh both sides by checking the 3 key rewards and 4 important warning signs.
Looking For More Ideas Beyond Wyndham Hotels & Resorts?
If Wyndham Hotels & Resorts has your attention, do not stop with a single ticker. Broad input usually leads to sharper decisions and better risk control.
- Target higher quality opportunities by focusing on strong cash generation and sensible valuations through our 27 high quality undervalued stocks.
- Prioritise resilience by scanning a list of solid balance sheet and fundamentals (25 results) that can better handle shocks than heavily indebted peers.
- Lean into stability seekers' favorites by reviewing our 8 dividend fortresses that concentrate on meaningful income potential.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com