


Martin Marietta Materials (MLM) has drawn fresh attention after recent share performance left the stock down 5% over the past month and 14% over the past 3 months, which has sharpened investor focus on its valuation.
The recent slide in Martin Marietta Materials’ share price sits against a longer record where short term momentum has faded, yet the 3 year total shareholder return of 16.28% and 5 year total shareholder return of 44.42% still point to meaningful value creation over time.
Scan beyond Martin Marietta Materials and review other construction and materials players with a track record of solid fundamentals using our curated list of solid balance sheet and fundamentals (25 results).
With Martin Marietta Materials now trading well below its recent highs, some investors may be tempted to step in, while others may prefer to wait for an even lower entry. How does the current valuation compare with those choices?
Most Popular Narrative: 25% Undervalued
On the most followed view, Martin Marietta Materials has a fair value of about $652.71, compared with a last close of $489.01. This frames the recent pullback as a discount to that narrative outlook.
The enlarged Specialties platform, now including Premier Magnesia and Lhoist North America with lime and magnesia products serving steel, soil stabilization, water treatment, flue gas treatment and other industrial uses, brings a larger base of contracted, less cyclical revenue with higher EBITDA margins and modest maintenance capital needs. This can improve Martin Marietta Materials consolidated margins and earnings resilience through cycles.
See why 10 investors see Martin Marietta Materials as 25% undervalued.
Result: Fair Value of $652.71 (UNDERVALUED)
Still, the Martin Marietta Materials story can change quickly if energy and diesel costs stay high, or if the large acquisitions fail to deliver planned synergies.
Find out about the key risks to this Martin Marietta Materials narrative.
Another View: Martin Marietta Materials On Earnings Multiples
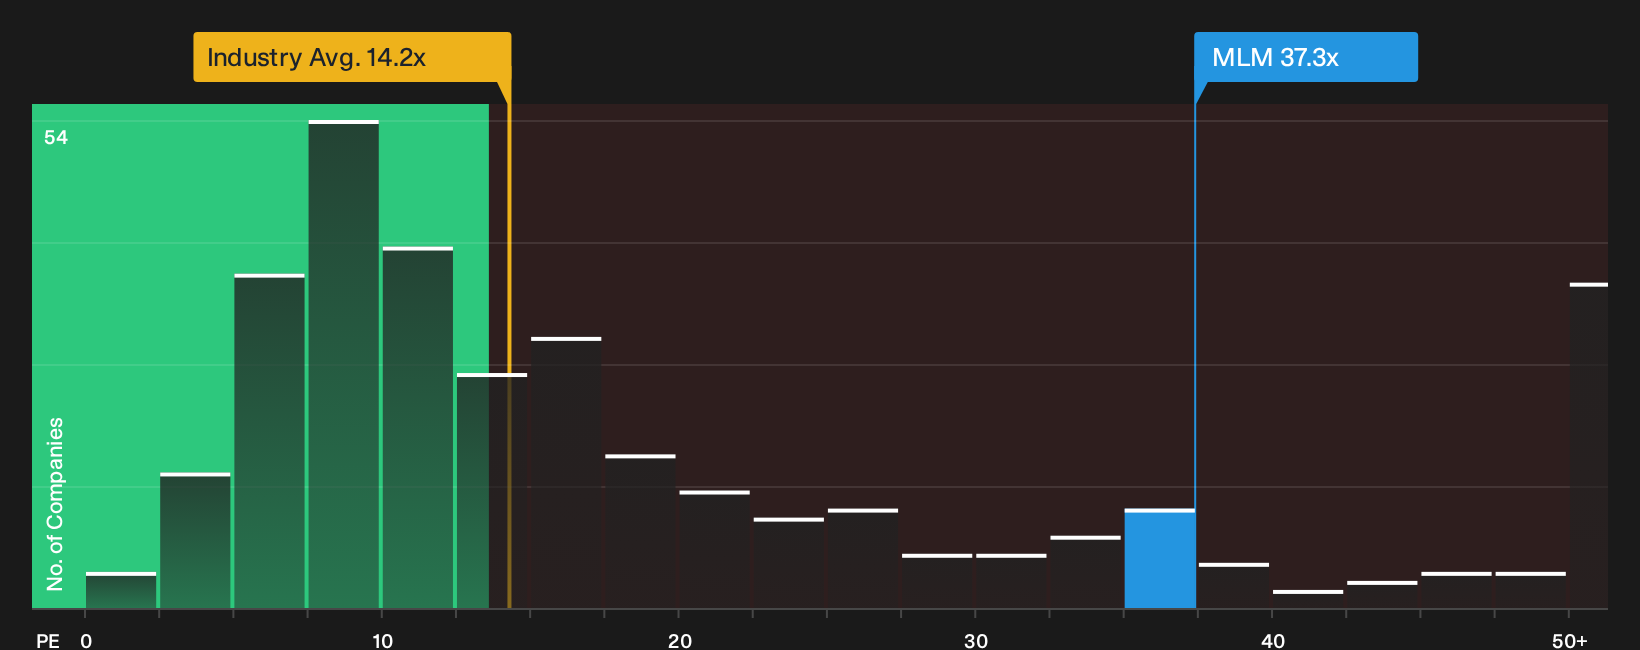
The fair value work for Martin Marietta Materials points to a discount, yet the earnings multiple tells a different story. The stock trades on a P/E of 37.3x, compared with 17.7x for peers and 14.2x for the wider Basic Materials group, while the fair ratio sits at 24.9x. That gap signals investors are already paying a premium, so it raises the question of how much safety margin really exists if the growth narrative wobbles.
For a closer look at what this richer multiple could mean for valuation risk and upside, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Martin Marietta Materials so far. If you want to move quickly and build your own view using the same information, you can start by weighing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Martin Marietta Materials?
If Martin Marietta Materials is on your radar, do not stop there. Use the same disciplined approach to uncover fresh ideas that fit your goals and risk comfort.
- Target potential value opportunities by scanning companies that combine strong fundamentals with attractive pricing using our 27 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses with robust payouts and higher yields through the 8 dividend fortresses.
- Reduce portfolio stress by focusing on financially resilient businesses screened via the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com