


Adobe has seen its share price fall sharply over multiple years, yet the company keeps generating earnings that investors still pay attention to. With the stock closing at US$238.12 and recent news centering on AI partnerships and earnings power, the live question is whether that price can be explained by the profits the business is producing.
- Over the past 5 years the stock has declined 59.0%, which puts the focus squarely on whether the current valuation is now more aligned with Adobe's underlying earnings power.
- Recent updates pointing to strong profitability metrics and raised earnings expectations suggest the market may reassess how much it is willing to pay for each dollar of profit, which directly affects how the P/E ratio compares with the Fair Ratio benchmark.
- The analysts covering Adobe have run their own numbers. See what analysts think Adobe's shares could be worth.
The issue now is whether Adobe's recent share price and earnings multiples are justified by the level and quality of its current profits.
To put Adobe's earnings story in context, it can help to compare it with other companies in similar situations using the 27 high quality undervalued stocks.
Is Adobe Still Cheap on Earnings?
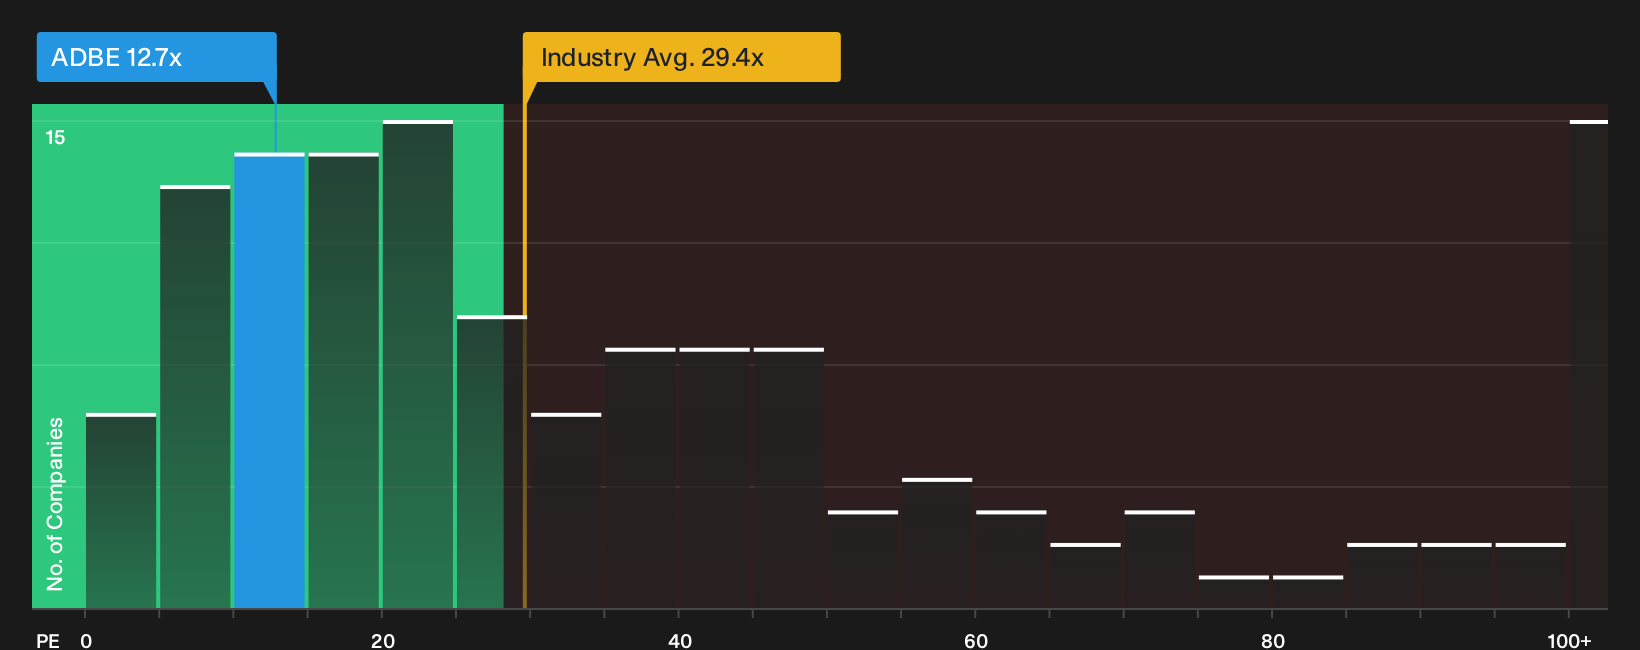
The P/E ratio fits Adobe because earnings still drive most of the debate around the stock. On this measure, the shares trade on roughly 12.7x earnings, which is far below the Software sector average of about 29.4x and well under the peer group on roughly 49.5x. For a large software platform with long established products and steady free cash flow, that is a wide gap.
Fair Ratio modelling, which looks at Adobe’s growth profile, margins, size and risk, points to a higher P/E than where the stock currently trades. As a result, the shares screen as undervalued on this metric. Despite the recent Q3 earnings beat and higher guidance lifting sentiment, the market is still pricing Adobe at a P/E well below both sector and peer benchmarks. This keeps the valuation debate very much alive for anyone weighing the recent AI partnerships and earnings guidance. Explore the numbers behind Adobe's P/E valuation.
The Adobe Narrative: What Would Justify Today's Price?
Adobe Narratives on Simply Wall St pick up where the P/E puzzle leaves off and explain which future paths for growth, profitability and earnings would need to occur for the stock to be worth materially more or materially less than today’s valuation. Rather than relying on a single multiple or one model output, each narrative lays out its own set of assumptions so you can weigh those against Adobe’s actual results as they arrive over time.
Community views on Adobe sit on opposite sides of the valuation line, with one camp seeing a discount and the other calling it a value trap.
Bull case: 48% undervalued
"The current valuation of Adobe reflects a market that is pricing in a structural obsolescence that is not supported by the company’s underlying financial performance or its aggressive technological pivots…"
Discover why this Narrative puts Adobe at 48% undervalued.
Bear case: 46% overvalued
"Adobe was an amazing company. I'm an end user since 1991. I think it's become a value trap…"
Explore why this Narrative puts Adobe at 46% overvalued.
Adobe’s share price is only one piece of the puzzle
Before deciding how Adobe fits in your portfolio, it helps to know that Simply Wall St’s broader checks have also flagged specific risk signals that deserve a closer look beside the headline valuation. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com