


Global energy prices sit at stubbornly high levels, and the IMF is warning that this kind of pressure can strain company profits and government budgets alike. That kind of stress often pushes investors toward Canadian businesses that throw off steady cash and yet trade at modest valuations. This article highlights three stocks from a cash flow focused value screen that may interest patient bargain hunters.
The three stocks highlighted below are only a sample from this cash flow focused screen. This screen also surfaced 7 more businesses with equally interesting stories that do not feature in the rest of this article.
If you want to move beyond the short list and systematically hunt for value, head straight to the Undervalued Stocks Based On Cash Flows screener to identify, analyze, and prioritize the highest conviction ideas from this cash flow universe.
Stantec (TSX:STN)
Stantec is a global design and consulting group best known for infrastructure and sustainable water projects that can support long, visible cash flows, while broader engineering and architecture services round out the offering for clients across public agencies, utilities, and private operators.
Stantec generates about CA$3.6b of revenue from the United States, CA$1.6b from Canada, and CA$1.7b from global operations, and the stock carries a market value of roughly CA$10.7b.
Demand for infrastructure upgrades, water/wastewater treatment, energy transition, and climate adaptation projects remains exceptionally strong globally, with double-digit organic growth and a $7.9 billion backlog, positioning the company for sustained revenue expansion in line with multi-decade trends toward urbanization and aging infrastructure.
What happens to that opportunity set if a single pressure point quietly shifts the balance between rising project demand and future profitability.
If that pressure point matters to you, read the full narrative for Stantec to see whether Stantec’s backlog strength is masking risk or accelerating opportunity.

Pan American Silver (TSX:PAAS)
Pan American Silver is a precious metals producer that matters for this cash flow focused screen because its producing silver and gold mines feed the very operating cash streams that underpin discounted cash flow valuations and shape how value driven investors judge the stock.
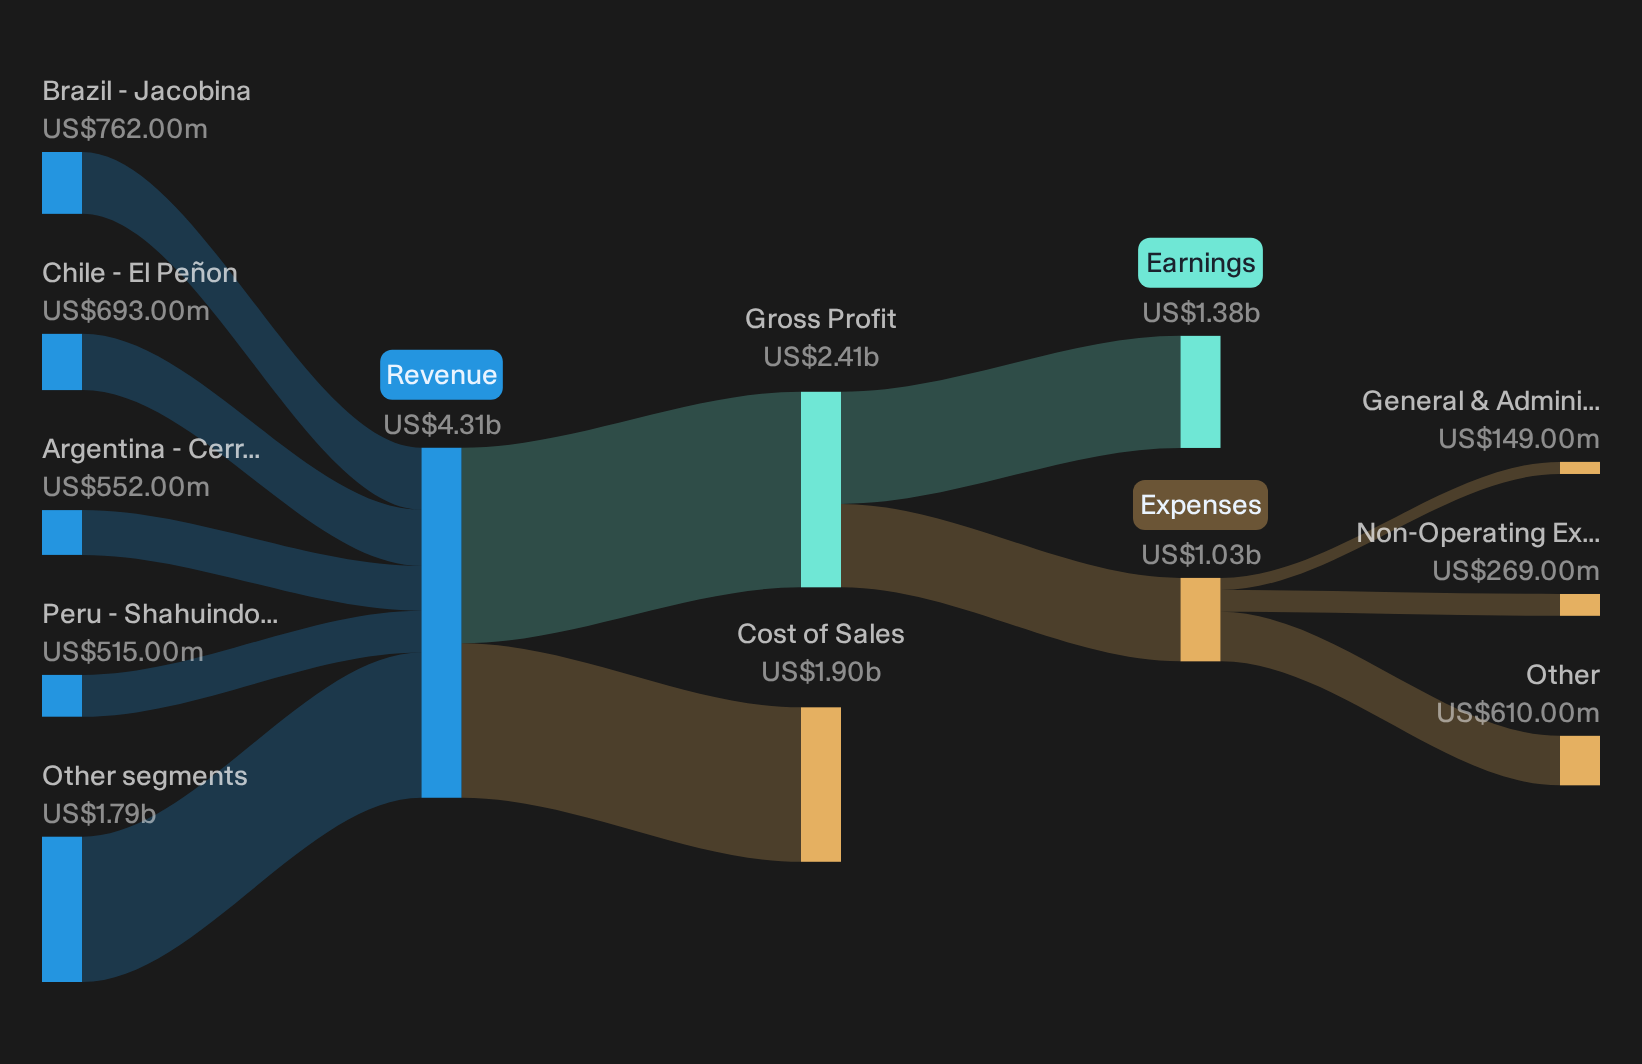
Pan American Silver runs silver and gold mines across the Americas, with material revenue from Brazil’s Jacobina mine at about $762 million, Chile’s El Peñon at roughly $693 million and Peru’s Shahuindo at around $515 million, and carries a market value near CA$27.0b.
Integration of Juanicipio, with its low cash costs and contribution to attributable silver production and income, refines the cost base and can support higher segment margins and free cash flow generation.
The real test comes if one less visible cost and capital pressure shifts, and those projected cash flows meet tougher margin realities.
If that margin squeeze is what you are weighing up, read the full narrative for Pan American Silver to see how Pan American Silver’s cash engine could accelerate or stall next.
Suncor Energy (TSX:SU)
Suncor Energy is an integrated producer and refiner where long life Oil Sands operations feed directly into the cash flow focused value theme. While downstream refining and marketing remain a larger revenue engine with about CA$36.8b, Oil Sands contribute roughly CA$26.9b and Exploration and Production about CA$2.5b, supporting a business valued near CA$114.6b.
Suncor Energy appeals to value focused investors who care about long lived cash streams because its Oil Sands cash generation is closely tied into an integrated refining and retail system that can translate operational reliability into hard dollars over long periods.
Reliance on very high utilization of existing oil sands and refining assets, including refinery runs consistently at or above 100% and upgrader utilization above 100%, leaves little unused capacity to offset unplanned outages, which could pressure volumes and compress margins if reliability slips from current record levels.
What happens to that carefully balanced cash engine if one cost pressure or operating constraint quietly shifts and resets the margin math?
To see how that pressure could be accelerating or masking Suncor Energy’s long term cash story, walk through the full narrative for Suncor Energy for the full picture.

Seeking Fresh Alternatives Before They Fly
Fresh breakouts and under the radar movers rarely stay quiet for long. Spot early momentum before the crowd, while the data still matters. Get in early.
- Track resilient performers that keep compounding through different cycles by scanning the 8 resilient stocks with low risk scores, curated to spotlight sturdier balance sheets and more predictable cash profiles.
- Catch potential breakout miners before silver momentum gets fully priced by running the 10 top silver producer stocks, focused on producers with meaningful scale and targeted operating footprints.
- Target AI platforms already turning code into profits using the 35 profitable AI stocks that aren't just burning cash, which filters for cash generative developers instead of capital hungry experiments.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com