


In recent weeks, global markets have experienced mixed performances, with U.S. major stock indices showing varied results amid fluctuating Treasury yields and persistent inflation concerns. As investors navigate this uncertain landscape, growth companies with significant insider ownership can offer a unique perspective on potential revenue expansion, particularly those anticipating substantial increases in their financial performance.
Top 10 Growth Companies With High Insider Ownership Globally
| Name | Insider Ownership | Earnings Growth |
| Shanghai Skychem Technology (SHSE:688603) | 31.8% | 67.7% |
| Shanghai Biren Technology (SEHK:6082) | 10.4% | 119.7% |
| Pharma Mar (BME:PHM) | 12.1% | 39.8% |
| Meitu (SEHK:1357) | 23% | 26.7% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| JHT DesignLtd (SHSE:603061) | 23.1% | 48.6% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 32% |
| Fulin Precision (SZSE:300432) | 10.8% | 66.5% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
Let's uncover some gems from our specialized screener.
Oscotec (KOSDAQ:A039200)
Simply Wall St Growth Rating: ★★★★★★
Overview: Oscotec Inc. is a biotechnology company involved in drug development, functional materials, and dental bone graft materials, with a market cap of ₩1.50 billion.
Operations: The company's revenue segments consist of ₩1.31 billion from the Food Business, ₩213.80 million from Functional Materials, ₩1.78 billion from the Medical Business Sector, and ₩140.88 billion from the New Drug Business Division.
Insider Ownership: 32.4%
Revenue Growth Forecast: 30.3% p.a.
Oscotec's recent earnings report highlights a remarkable turnaround, with a net income of KRW 36.66 billion for Q2 2026, contrasting sharply with last year's loss. The company's earnings and revenue are projected to grow significantly over the next three years, outpacing the Korean market averages. With its stock trading at a substantial discount to estimated fair value and no significant insider trading activity in recent months, Oscotec presents an intriguing growth opportunity.
- Unlock comprehensive insights into our analysis of Oscotec stock in this growth report.
- Our comprehensive valuation report raises the possibility that Oscotec is priced lower than what may be justified by its financials.
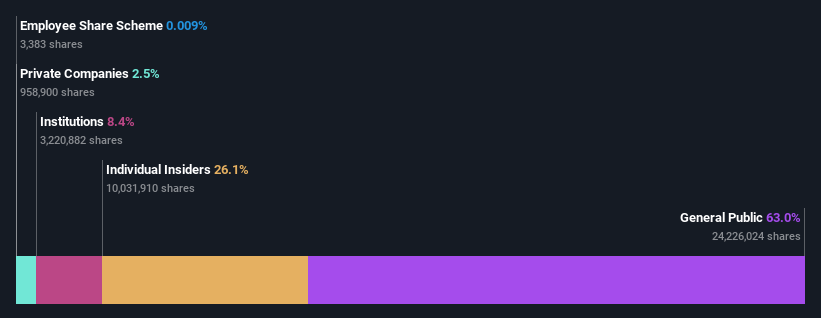
Electrical Industries (SASE:1303)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Electrical Industries Company specializes in the manufacture, assembly, and servicing of various electrical equipment such as transformers and switch gears, with a market capitalization of SAR15.70 billion.
Operations: The company's revenue is primarily derived from Manufacturing, Assembly and Supply, which contributes SAR2.51 billion, and Services, which generate SAR114.18 million.
Insider Ownership: 38.7%
Revenue Growth Forecast: 14.1% p.a.
Electrical Industries reported strong half-year results with sales of SAR 708.57 million and net income of SAR 211.53 million, reflecting significant growth from the previous year. The company is expected to see revenue and earnings grow faster than the Saudi Arabian market at 14.1% and 18.7% per year, respectively. Despite a lower-than-industry-average P/E ratio of 20.5x, no substantial insider trading activity has been noted recently, indicating stable insider confidence in its growth trajectory.
- Click here and access our complete growth analysis report to understand the dynamics of Electrical Industries.
- Upon reviewing our latest valuation report, Electrical Industries' share price might be too optimistic.

Chenbro Micom (TWSE:8210)
Simply Wall St Growth Rating: ★★★★★★
Overview: Chenbro Micom Co., Ltd. is involved in the R&D, design, manufacture, processing, and sale of computer peripherals and main systems across various international markets including the United States, China, Taiwan, Singapore, and Europe with a market cap of NT$110.91 billion.
Operations: The company generates revenue of NT$27.33 billion from its computer peripherals segment.
Insider Ownership: 23.7%
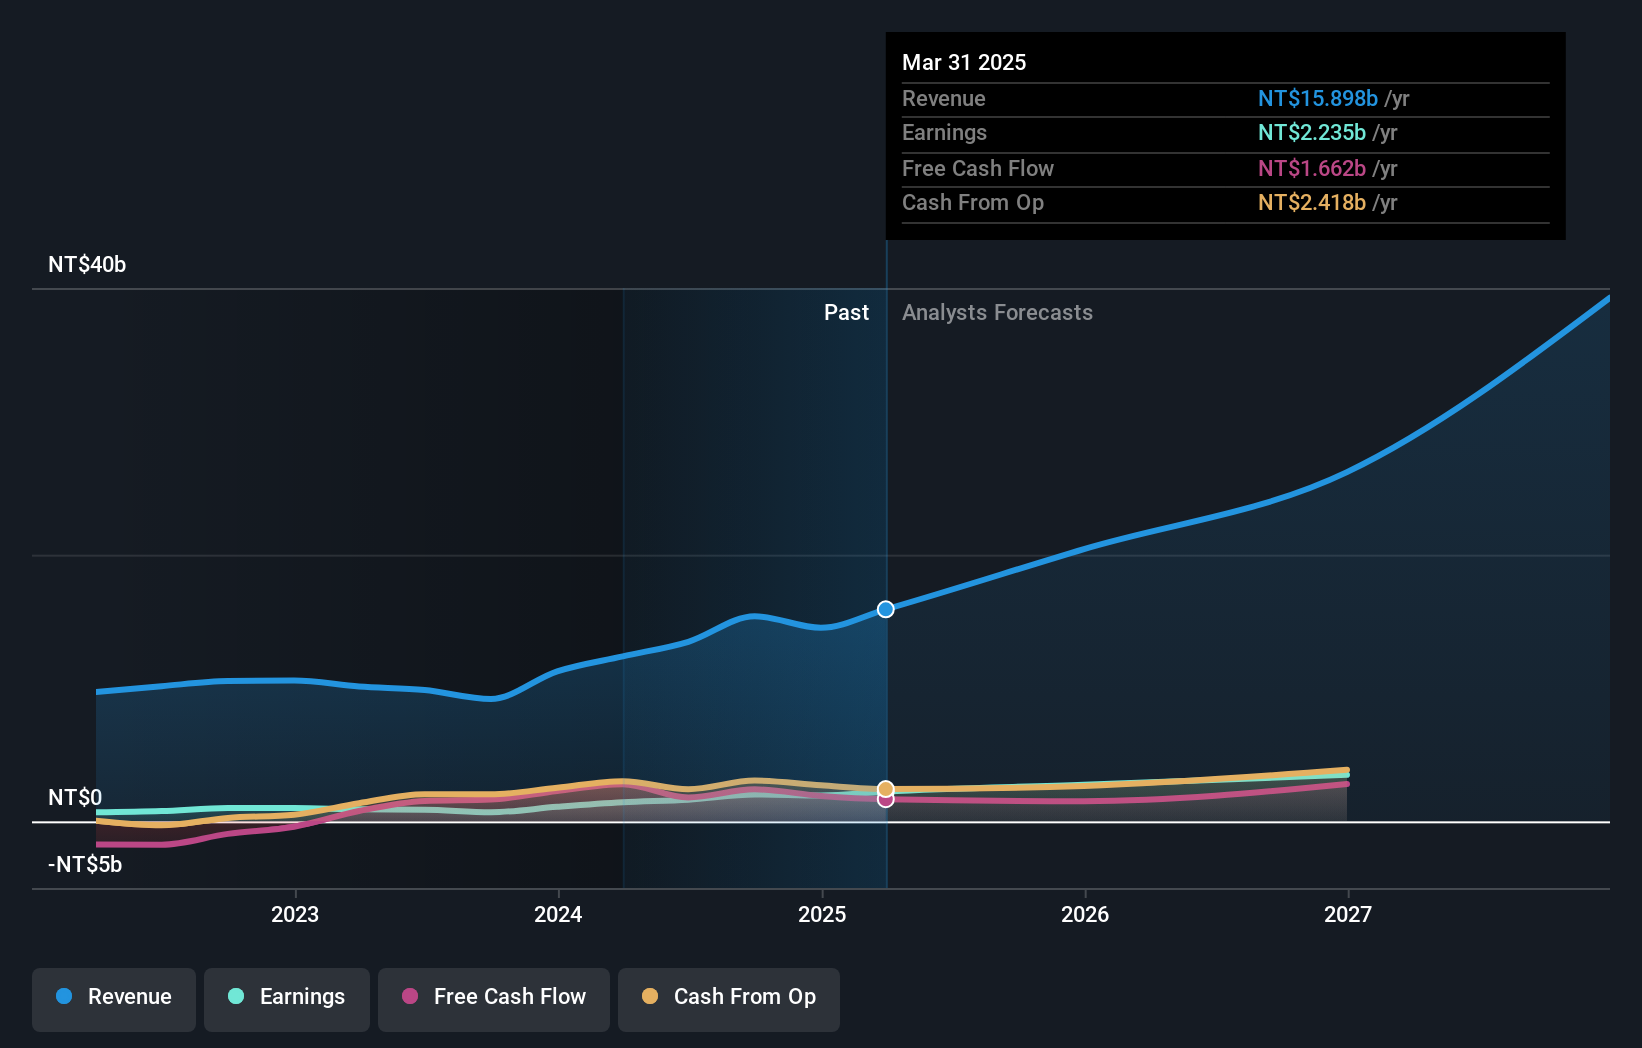
Revenue Growth Forecast: 29.8% p.a.
Chenbro Micom's recent earnings report revealed substantial growth, with Q2 sales reaching TWD 7.82 billion and net income at TWD 1.38 billion, up from the previous year. The company's revenue is forecast to grow significantly faster than the Taiwan market, supported by a very high expected return on equity of 41.9% in three years. Despite trading below its estimated fair value, its share price remains highly volatile with an unstable dividend history.
- Dive into the specifics of Chenbro Micom here with our thorough growth forecast report.
- Upon reviewing our latest valuation report, Chenbro Micom's share price might be too pessimistic.
Where To Now?
- Get an in-depth perspective on all 703 Fast Growing Global Companies With High Insider Ownership by using our screener here.
- Searching for a Fresh Perspective? Explore 24 top quantum computing companies leading the revolution in next-gen technology and shaping the future with breakthroughs in quantum algorithms, superconducting qubits, and cutting-edge research.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com