


Ondas has seen its share price swing sharply in recent years, yet the more pressing issue for anyone looking at the stock today is whether that current market value lines up with what its earnings can reasonably support.
- Over the past 3 years, the stock has delivered a very large gain of about 15x. That puts extra focus on whether that move is consistent with the underlying earnings power of the business.
- A recent US$56 million order for Electronic Safe & Arm Devices in Europe, together with a series of defense-focused acquisitions, can reshape expectations for Ondas' future profitability, capital needs and how quickly any earnings could scale.
- Your read on Ondas is one view; the desks covering it have another. See what analysts think Ondas's shares could be worth.
The issue now is whether the earnings behind Ondas can justify where the share price sits after these moves and new contracts.
For a wider lens on defense and autonomy themes beyond Ondas, it can help to compare it with other specialists in the space using 87 robotics and automation stocks.
Does Ondas Look Pricey on Earnings?
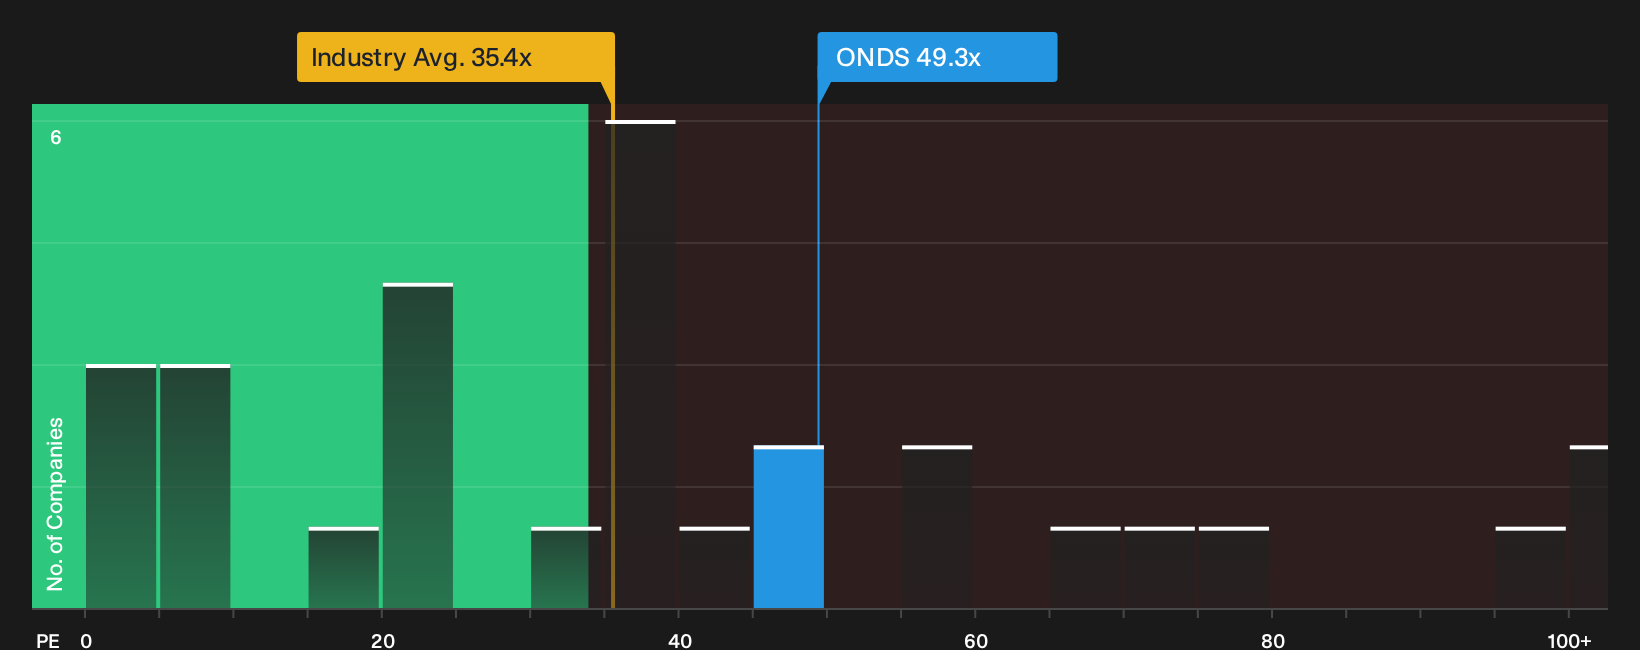
The P/E ratio works reasonably well for Ondas because the discussion is already centered on what current earnings can support. On this measure, Ondas trades on a P/E of about 49.3x, which is very close to peers on roughly 50.4x and well above the wider communications sector on about 35.4x. That combination signals a market that is pricing the stock closer to specialist comps than to the broader industry group.
The fair ratio model, which blends in factors like growth potential, margins, size and risk profile, points to a lower P/E than where Ondas trades today, so the current 49.3x screens as overvalued on this framework. Because the recent US$56 million European ESAD order and the series of defense-focused acquisitions have lifted expectations around the business, the rich multiple effectively assumes that these contracts and platforms can translate into stronger earnings over time. Investors weighing Ondas on P/E alone would need to judge whether those assumptions feel robust enough to support paying this kind of premium. Explore the numbers behind Ondas's P/E valuation.
The Ondas Narrative: What Would Justify Today's Price?
Narratives for Ondas pick up where the valuation puzzle leaves off by explaining which paths for growth, profitability and future earnings would need to occur for the stock to be worth meaningfully more or less than it is today. Each one treats fair value as a clear thesis about the business that can be revisited over time on Simply Wall St's Community page to see how it holds up against new information.
One of the top community narratives on Ondas: 62% undervalued
"By architecting what they call "Layered ISR," Ondas is effectively merging two worlds that used to operate in isolation…"
Discover why this Narrative puts Ondas at 62% undervalued.
One more piece of the Ondas puzzle worth checking
Price tags and contracts only tell part of the story for Ondas, because the people steering the business and how they are rewarded can heavily shape what happens next. See who runs Ondas and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com