


Leadership transition puts Johnson Controls International in focus
Johnson Controls International (NYSE:JCI) is back on investor screens after the firm agreed with Julie Brandt, its Vice President and President, Global Commercial and Field Operations, that she will exit her role as part of a planned operating model shift.
The leadership reshuffle lands at a time when Johnson Controls International’s momentum is already strong, with a 1-month share price return of 9.54%, year to date share price gains of 29.80%, and a 1-year total shareholder return of 48.35% reflecting rising optimism toward the story over both shorter and longer horizons.
Scan how Johnson Controls International compares with other companies showing strong momentum and leadership shifts by reviewing our curated list of 27 high quality undervalued stocks in related sectors.
After a sharp run and a fresh leadership shake up, Johnson Controls International now forces a choice. Is the recent momentum enough to justify stepping in today, or does patience on price still look smarter before the valuation work starts?
Most Popular Narrative: 4% Undervalued
On the most followed view of Johnson Controls International, the shares recently closed at $158.76 against an implied fair value of about $165.80. The bullish story rests on whether the underlying engine can justify that gap.
The main factor that has to go right is continued execution on service attach and productivity, so that stronger equipment demand in areas like North America and data centers ultimately translates into the more profitable, higher margin mix the business system is designed to support.
The focus on expanding service capabilities and improving service attachment rates, especially on the growing installed base in AI and other mission critical data centers where uptime is critical, is likely to shift mix toward higher margin recurring revenue and support net margin expansion.
See why 25 investors see Johnson Controls International as 4% undervalued.
Result: Fair Value of $165.80 (UNDERVALUED)
Still, if complexity in product lines drags on execution or Fire and Security weakness lingers, the bullish Johnson Controls International narrative could quickly lose traction.
Find out about the key risks to this Johnson Controls International narrative.
Another view on Johnson Controls International’s valuation
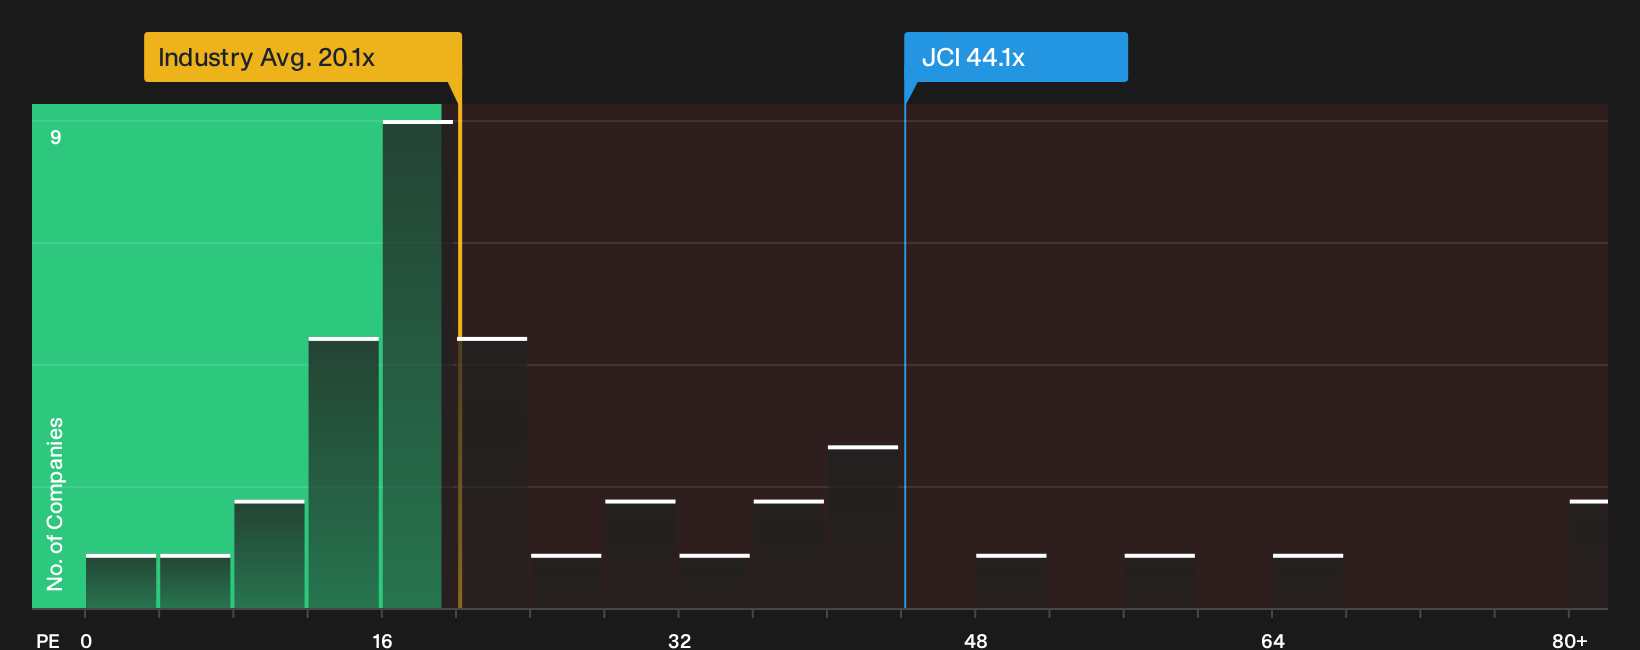
The story so far leans on a fair value of $165.80 implying Johnson Controls International is about 4% undervalued. The preferred P/E view paints a tougher picture. The current P/E of 44.1x screens well above the fair ratio of 35.1x, the US Building industry at 20.1x and peers at 27x. That kind of premium narrows the margin for error, so investors may want to consider how much valuation stretch they are comfortable holding through the next wobble.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Johnson Controls International story can be useful. Look at the full data set, move quickly, and weigh both the 2 key rewards and 2 important warning signs.
Looking for more Johnson Controls International style investment ideas?
Do not stop at Johnson Controls International. Put fresh ideas on your radar now, because waiting on the sidelines can mean missing the next move entirely.
- Target reliable cash flows with companies built to return capital consistently and stress test your income stream using the 8 dividend fortresses.
- Hunt for quality businesses at sensible prices and focus your research on pricing power, balance sheets and cash generation with the 27 high quality undervalued stocks.
- Prioritize resilience by filtering for companies with sturdier finances, so drawdowns hurt less and recoveries feel faster through the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com