


Cenovus Energy has delivered a powerful share price run in recent years, which puts a sharper spotlight on whether today's valuation is still backed by its earnings. With the stock now reflecting both strong past returns and fresh corporate moves, investors are asking if the current price accurately reflects what the business is earning right now.
- Over the past 5 years the stock has returned 255.0%, which raises the question of how much of that gain is supported by the underlying earnings power of the business.
- The planned C$5.7b acquisition of Athabasca Oil can reshape Cenovus Energy's production mix and capital needs, which may influence how investors weigh its earnings against the purchase price.
- There is a second opinion on Cenovus Energy worth weighing. See what analysts think Cenovus Energy's shares could be worth.
The stock's next move may depend on whether Cenovus Energy's current share price is justified by the earnings the company is producing today.
If you want a broader starting list of ideas alongside Cenovus Energy, consider using a focused stock screen built around 7 high quality undervalued stocks.
Is Cenovus Energy a Bargain on Earnings?
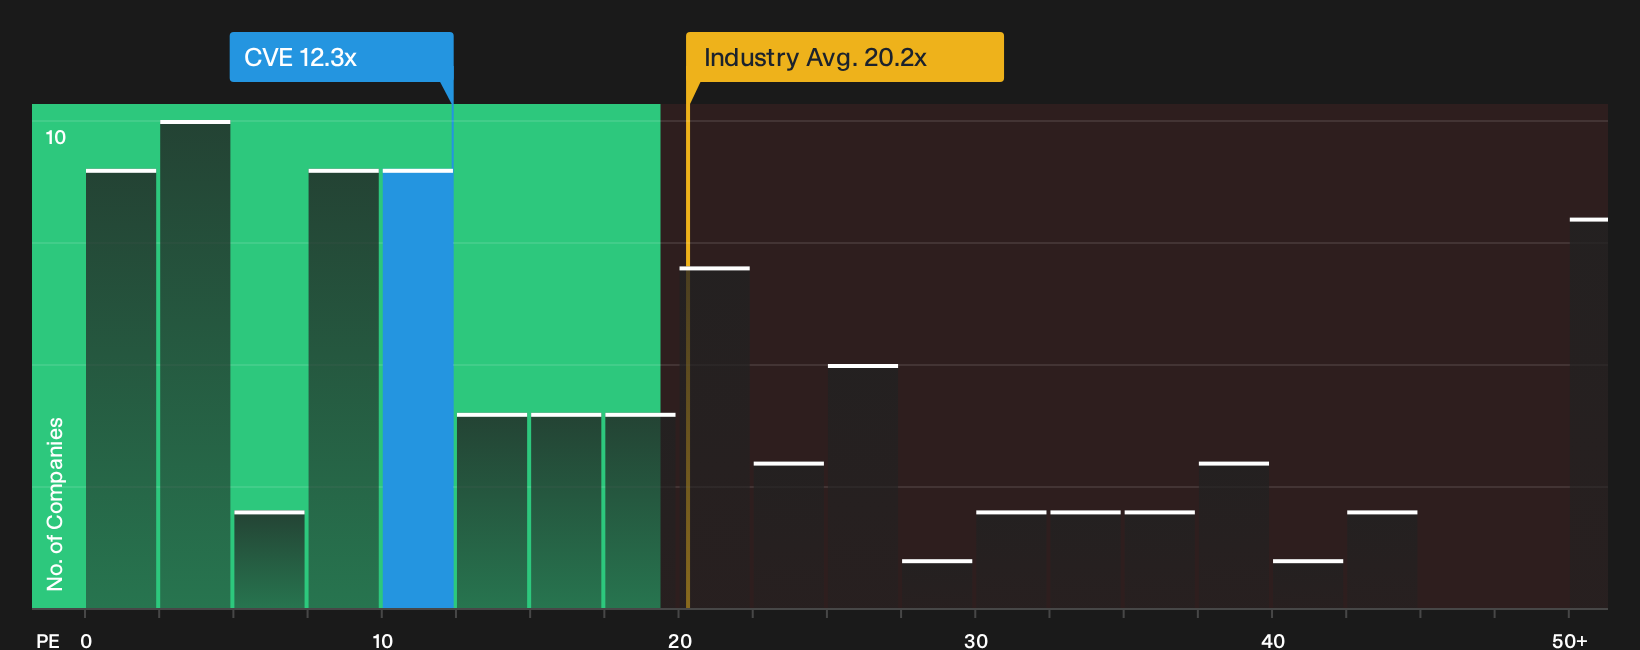
The P/E ratio is a useful yardstick for Cenovus Energy because earnings remain a central focus for investors in large, established producers. On this measure, the stock trades at about 12.3x earnings, which is below both the Oil and Gas sector average of roughly 20.2x and a peer group closer to 17.3x. The gap suggests the market is pricing Cenovus at a discount to many comparable producers on current profits.
The fair P/E level implied by Cenovus Energy's own profile is higher than where the shares trade today. This points to the stock being undervalued on this specific earnings yardstick. Because the planned C$5.7b Athabasca Oil acquisition has put a spotlight on Cenovus's future capital needs, the current discount suggests investors are still demanding a margin of safety despite the recent operational and free cash flow headlines. Explore the numbers behind Cenovus Energy's P/E valuation.
The Cenovus Energy Narrative: What Would Justify Today's Price?
Narratives pick up where Cenovus Energy's valuation puzzle leaves off by spelling out which future paths for production, margins and earnings would need to play out for the stock to look materially cheaper or more expensive than it does today, and they sit on Simply Wall St's Community page. Each one turns Cenovus Energy's implied fair value into a specific, trackable hypothesis about the business so you can see how that thesis holds up over time.
One of the top community narratives on Cenovus Energy: 13% undervalued
"Successful completion of key growth projects such as Narrows Lake, West White Rose, and the Foster Creek optimization is set to deliver significant new, stable, long-life production..."
Discover why this Narrative puts Cenovus Energy at 13% undervalued.
Cenovus Energy's price is only one piece of the decision puzzle
Valuation tells you what the market is willing to pay today, but the research community has already mapped out where they expect Cenovus Energy to be a few years from now, and that comparison can sharpen your own view. Explore where analysts expect Cenovus Energy to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com