


Corning (GLW) is back in focus after signing a multi year fiber and cable supply agreement with AT&T, worth more than US$3b and tied directly to U.S. network and AI infrastructure buildouts.
Recent trading suggests buyers are leaning back in. Corning’s share price is up 6.0% over the past day and 9.5% over the last month, even after a roughly 8.2% decline across the past 90 days. The 1-year total shareholder return is about 100%, pointing to strong longer term momentum as investors weigh contracts like the new AT&T deal against execution and valuation risks.
Scan how Corning’s AI driven fiber story compares to other potential breakouts by running your eye over our 91 AI infrastructure stocks in the same space.
After a 1 year total shareholder return around 100% and a fresh US$3b AT&T contract in hand, does Corning still offer an attractive skew for new buyers, or has the easy part of the rerating already passed?
Most Popular Narrative: 11% Undervalued
On the most followed view, Corning’s fair value of $189.94 sits above the last close at $168.97. This frames the AT&T deal as one piece of a wider rerating story rather than the whole case.
The numbers imply that Corning’s current valuation treats the stock as if execution risk, equity issuance and mixed end market conditions fully offset the multibillion long term growth opportunities in AI data centers, U.S. solar and photonics. This underpins the view that the shares are undervalued.
See why 95 investors see Corning as 11% undervalued.
Result: Fair Value of $189.94 (UNDERVALUED)
Still, Corning’s use of a US$2b at the market equity program and recent solar segment losses could challenge the upbeat Springboard narrative if issues persist.
Find out about the key risks to this Corning narrative.
Another View: Corning Looks Expensive On Earnings
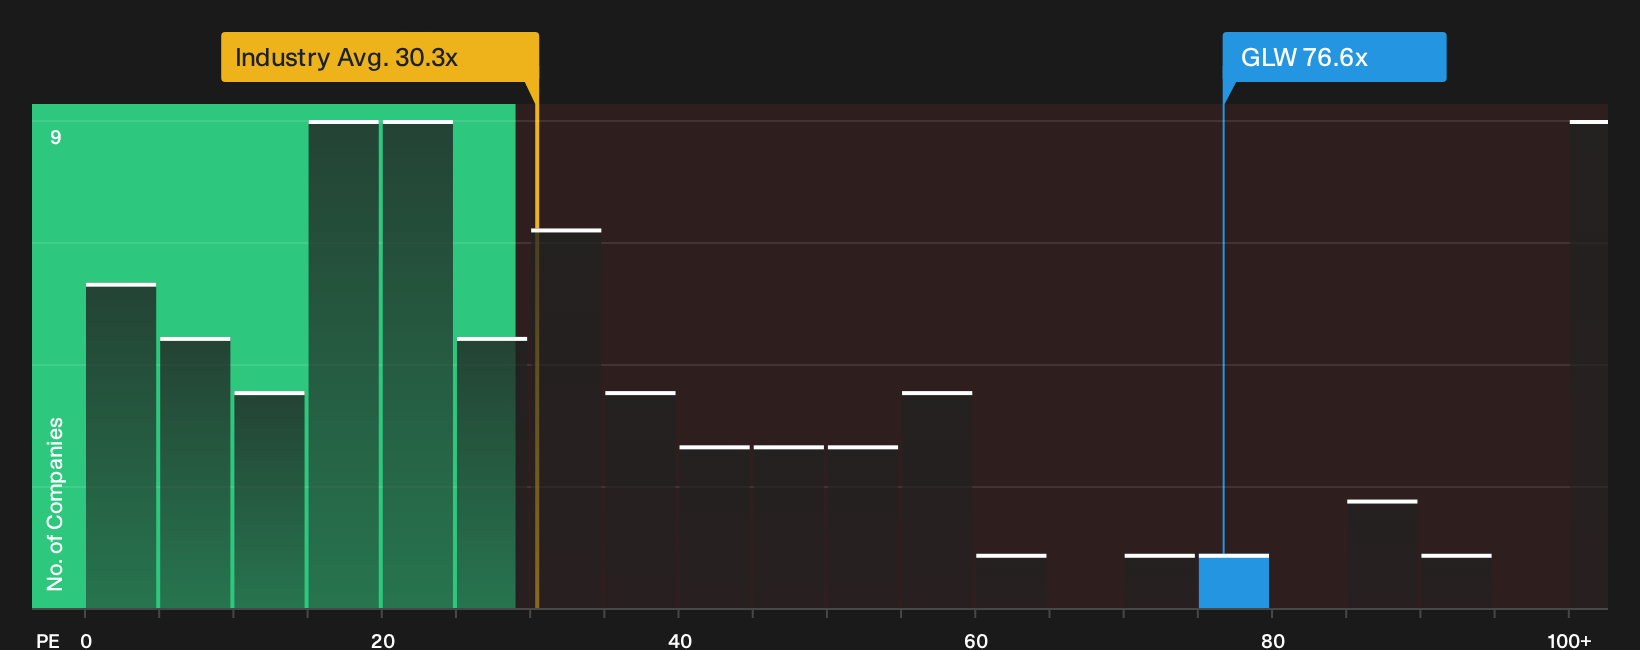
The fair value story for Corning leans on future cash flows. On straight earnings, the picture is less forgiving. The stock trades on a P/E of 76.6x, compared with 30.3x for the US Electronic industry and a fair ratio of 53.2x based on Simply Wall St regression work. That gap suggests investors are already paying up heavily for the growth narrative. If the Springboard plan stumbles, how quickly could sentiment swing back toward that fair ratio?
For a closer look at how this earnings based view fits into the wider numbers, including how different profit and growth assumptions affect the implied P/E, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Corning’s story so far shows mixed signals. If sentiment shifts quickly when new data arrives, it can help to act promptly, review the numbers yourself, and weigh both sides of the thesis using our breakdown of 3 key rewards and 3 important warning signs
Hunting For More Ideas Beyond Corning?
If Corning has sharpened your focus on where capital goes next, do not stop at a single ticker. Push your research edge by lining up more potential opportunities with clear themes.
- Target dependable cash generators by scanning a list of solid balance sheet and fundamentals (25 results) that can better withstand shocks when conditions change.
- Chase value with discipline by reviewing a 27 high quality undervalued stocks that already show stronger fundamentals than their current pricing implies.
- Get ahead of the crowd by tracking a 19 high quality undiscovered gems before they attract broader attention and tighter pricing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com