


Why Campbell's latest bond deal matters for CPB shareholders
Campbell's (CPB) has just completed a US$300 million fixed income offering, issuing fixed to floating rate notes due 2057. That long dated funding move gives investors fresh information about the company’s capital structure.
Set against that bond sale, Campbell's equity story has been under pressure, with the share price down 11.13% over 30 days and the year-to-date share price return down 31.43%, while the 1-year total shareholder return has fallen 35.02%, pointing to fading momentum as investors reassess both earnings quality and risk.
Compare Campbell's current reset with hand picked defensives in our 31 resilient stocks with low risk scores that aim to balance pressure on earnings quality with stronger risk profiles.
Bond investors have just lent Campbell's US$300 million on long terms while equity holders have faced a steady share price slide. Does it make more sense to step in now or wait for a cheaper valuation reset next?
Most Popular Narrative: 9% Undervalued
Campbell's most followed valuation story points to a fair value of $20.79 per share, compared with the latest close at $19.00. This frames the recent bond raise against a stock that screens as discounted on this view.
Ongoing execution of the expanded US$500 million enterprise wide savings program through fiscal 2030, built on prior PEAK savings and now targeting procurement across every P&L line, headcount reductions and further network optimisation after recent plant closures, is intended to lift productivity and operating efficiency. This can support gross margin and EBIT.
See why 41 investors see Campbell's as 9% undervalued.
Result: Fair Value of $20.79 (UNDERVALUED)
Still, the Campbell's story can break if raw material and logistics inflation prove stickier than expected, or if snack volumes keep sliding despite heavier brand support.
Find out about the key risks to this Campbell's narrative.
Another angle on Campbell's valuation
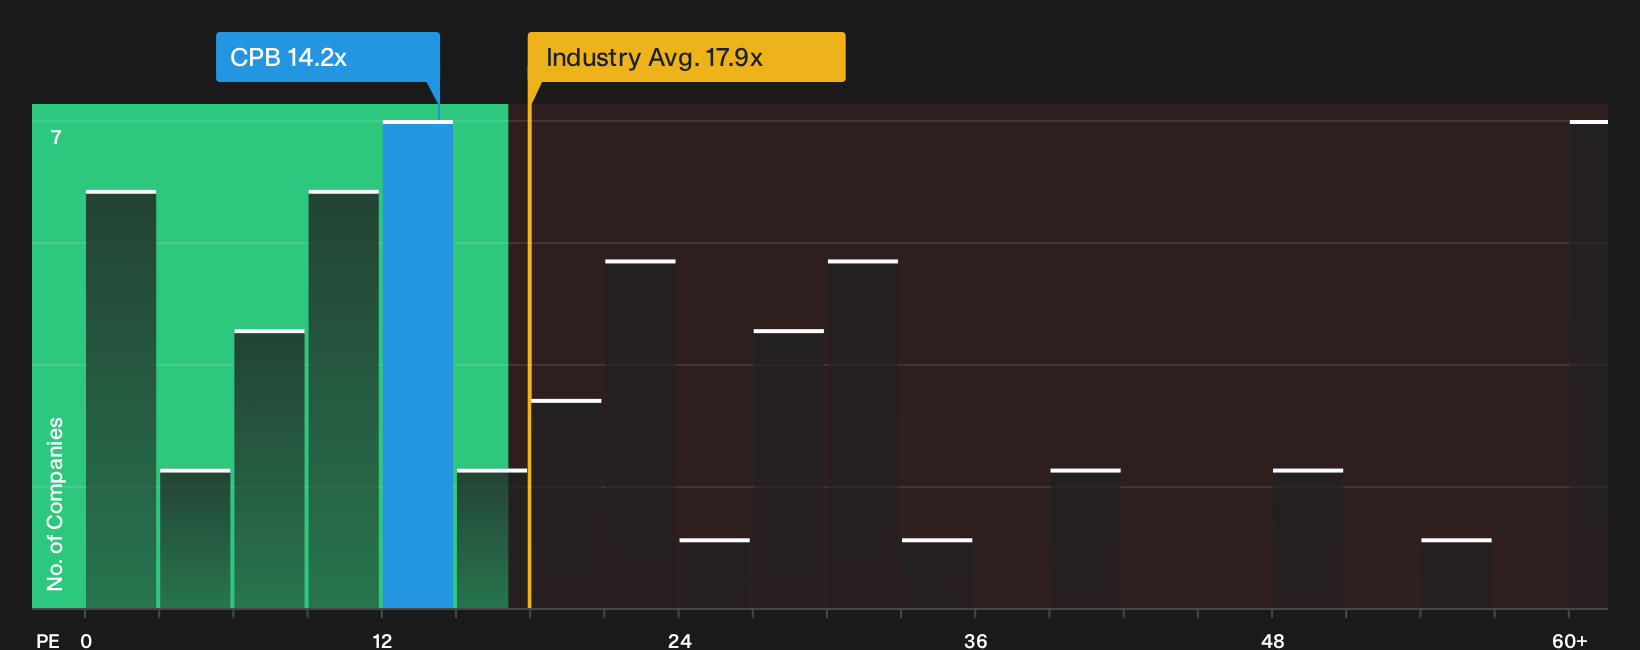
On simple price targets, Campbell's looks modestly undervalued. On earnings multiples, the picture is more cautious. The stock trades on a P/E of 14.2x, which is higher than close peers at 12.8x, yet below the US Food industry on 17.9x and a fair ratio estimate of 19.2x. That mix of premium to peers but discount to the sector leaves you weighing whether this is a safety margin or a sign of limited upside from here.
To pressure test that earnings based view against the detailed assumptions behind margins, growth and cash flows, it is worth walking through the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Seeing mixed signals around Campbell's valuation and risk profile can feel messy, so move quickly, review the data in full, and weigh both the potential upside and the downside using the 2 key rewards and 4 important warning signs.
Looking for more ideas beyond Campbell's?
You have seen how messy a single stock can look. Now widen your field of vision and line up alternatives that fit your own risk and income goals.
- Target income first and stress test Campbell's against other payers by reviewing stocks in the 8 dividend fortresses that focus on yield with substance behind it.
- Hunt for potential mispricing by weighing Campbell's valuation story against companies in the 19 high quality undiscovered gems that pair solid fundamentals with thinner analyst coverage.
- Dial back risk and compare Campbell's profile with the list of solid balance sheet and fundamentals (25 results) to see which businesses keep financial resilience front and centre.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com