


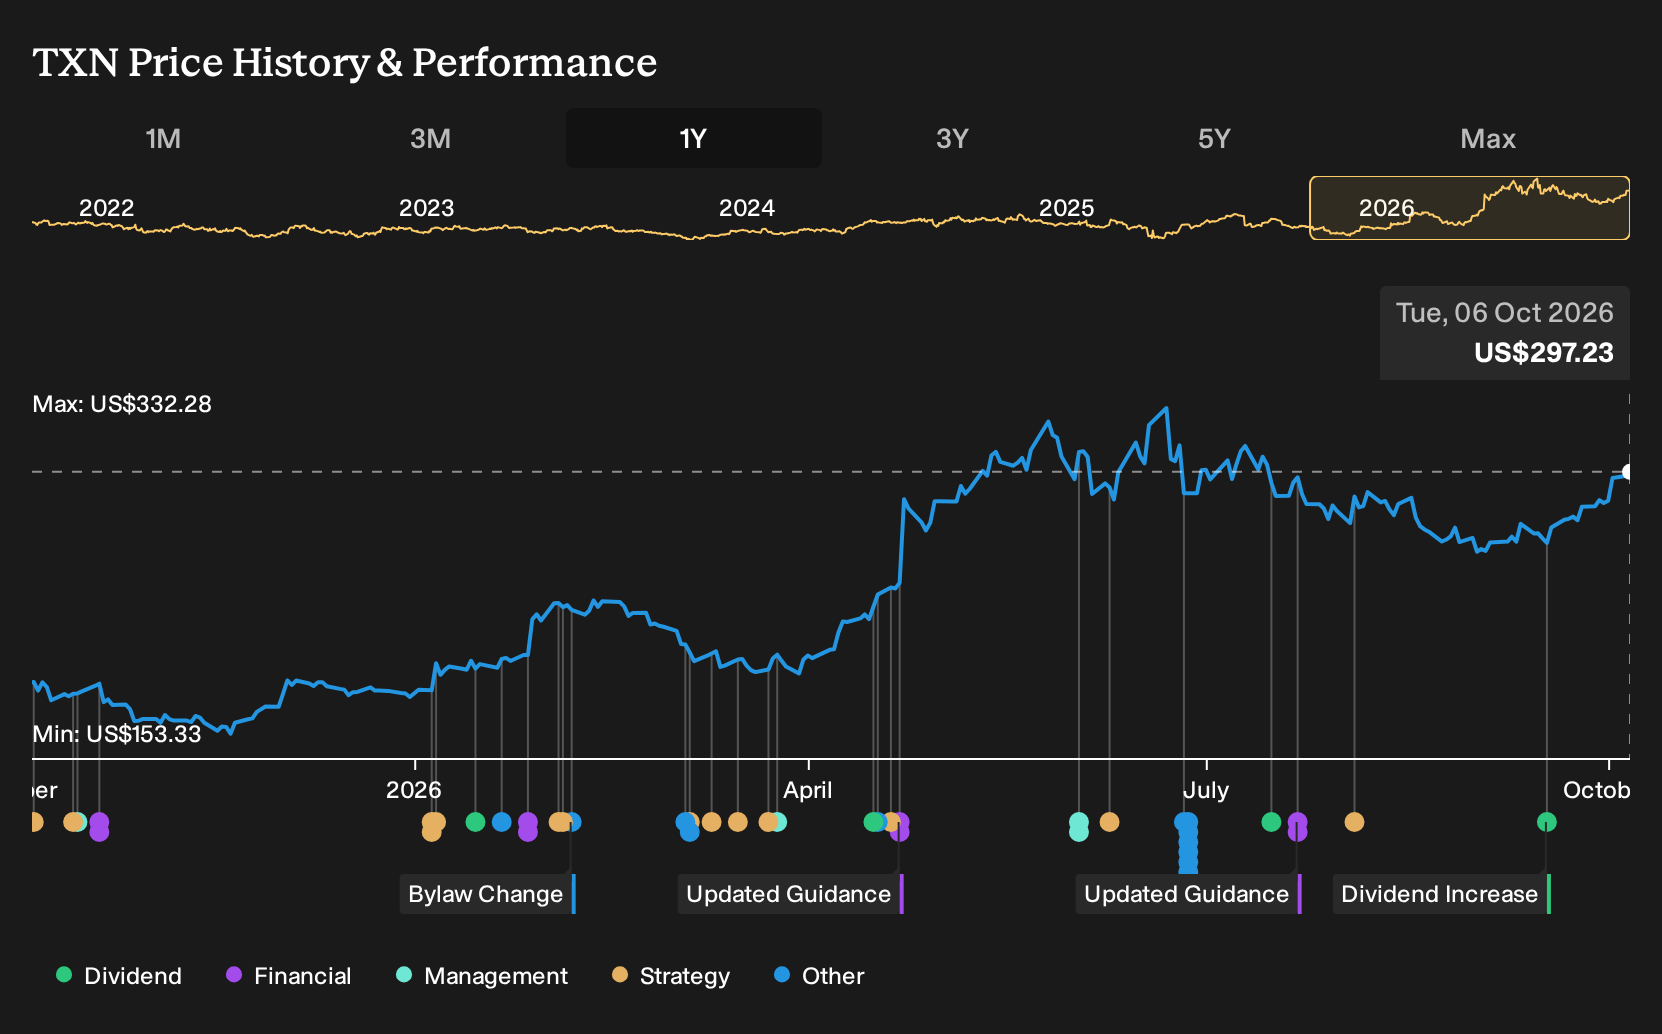
- Texas Instruments recently raised its quarterly dividend by 7% and announced a US$1.52 cash payout after reporting stronger sales and healthier operating margins.
- The firm is pairing higher cash returns with a long-term bet on 300mm in-house manufacturing and the Silicon Labs connectivity acquisition, tying shareholder payouts directly to factory efficiency and sustained chip demand.
- Now the focus shifts to how Texas Instruments' dividend increase and manufacturing payoff phase could reshape the broader investment narrative around the business.
Texas Instruments Investment Narrative Recap
To own Texas Instruments, you need to believe its heavy spend on 300mm fabs, internal manufacturing and connectivity will keep finding buyers across industrial, automotive and data center markets. The recent dividend hike and US$1.52 payout signal confidence in cash generation, but the near term swing factor remains how quickly factory utilization tightens.
The biggest operational risk is that capacity stays underused if industrial automation, auto content or data center orders cool, which would leave Texas Instruments with higher depreciation and pressured margins. The dividend news does not change that. It raises the bar for free cash flow execution while capital spending remains elevated.
The fresh 7% dividend increase to US$1.52 a quarter is the clearest recent signal to connect to this story. Management has discussed a framework where revenue of roughly US$20b could support US$8b to US$9b in free cash flow. A higher payout hard wires expectations that the business eventually turns its CapEx cycle into surplus cash.
For you as a shareholder, the key question is whether Texas Instruments can equip existing clean rooms, ramp high mix analog and embedded output and keep demand from industrial, auto and data center customers firm enough to cover that dividend and more. If factory loadings disappoint or data center enthusiasm cools, that commitment could feel tight.
What Analysts Are Pricing In For Texas Instruments
Analysts are effectively tying the Texas Instruments dividend story to a set of fairly specific growth assumptions. The current consensus framework hinges on revenue expanding by 14.5% a year over the next three years, profit margins stepping up from 30.9% today to 39.0%, and earnings almost doubling as the manufacturing buildout and Silicon Labs deal are absorbed.
On the earnings side, the Street is working with current profit of US$6.0b and a consensus projection of US$11.4b by 2029. That is an increase of about US$5.4b in annual earnings, with individual analyst views spread between US$10.2b and US$15.4b. The story investors are being asked to buy into is that higher factory utilization on 300mm, a richer mix from industrial, auto and data center, and modest share count growth of 0.51% a year combine to deliver that uplift without stretching the balance sheet.
Valuation assumptions then plug those operating targets into a P/E framework. The current analyst target of US$324.71 per share implies Texas Instruments would trade on about 36.7x the US$11.4b earnings estimate in 2029, compared with roughly 42.8x earnings today and around 46.9x for the wider US semiconductor group. That multiple already incorporates a cleaner free cash flow picture and steady dividend support once the heavy CapEx phase matures.
With the shares around US$281.69 as of early October 2026, the consensus target implies upside of 13.2% if those 2029 revenue and profit estimates hold. The spread between the most optimistic target at US$400 and the most cautious at US$225 underlines how much debate there is about utilization, AI heavy data center demand and the eventual payoff from the 300mm footprint. For an income focused holder, that range is a reminder to pressure test the assumptions behind the payout rather than relying on the dividend increase alone.
Texas Instruments' current analyst framework points to forecast revenue of US$29.2b and earnings of US$11.4b by 2029. That profile is built on expected annual revenue growth of 14.5% and an earnings increase of about US$5.4b from US$6.0b today.
Uncover why Texas Instruments' fair value indicates a 9% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
You can read the Texas Instruments dividend hike very differently. The most optimistic analysts lean on the AI data center ramp, penciling in revenue of about US$38.0b and earnings near US$15.3b by 2029, compared with the baseline US$29.2b and US$11.4b. Those projections were set before this dividend news, so opinions may shift and it can be useful to keep testing multiple viewpoints.
Explore 5 other Texas Instruments fair value estimates, including one that suggests as much as 47% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Texas Instruments research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Texas Instruments. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Texas Instruments' overall financial health at a glance.
Looking For More Ideas Beyond Texas Instruments?
If the Texas Instruments dividend story has you thinking about portfolio upgrades, it can help to line it up against other companies with different cash flow profiles and risk levels. The Simply Wall St Screener gives you a way to compare those trade offs in a structured way rather than relying on headlines.
- For investors who want income to feel sturdier through the cycle, start by focusing on dependable payers and review 8 dividend fortresses that may better match your risk tolerance.
- If capital preservation comes first and volatility is a concern, filter for sturdier balance sheets and steadier histories with the 31 resilient stocks with low risk scores to see which businesses fit that brief.
- When you are hunting for businesses that quietly compound in the background, try broadening your watchlist using the 19 high quality undiscovered gems that combine solid fundamentals with less attention from the crowd.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com