


As European equities face volatility amid rising oil prices and elevated sovereign bond yields, investors are increasingly focused on identifying opportunities that may be trading below their estimated value. In this environment, a good stock is often characterized by strong fundamentals and resilience to inflationary pressures, making it potentially attractive for those seeking undervalued investments.
Top 10 Undervalued Stocks Based On Cash Flows In Europe
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Valmet Oyj (HLSE:VALMT) | €27.66 | €53.06 | 47.9% |
| Promotica (BIT:PMT) | €2.98 | €5.91 | 49.6% |
| PORR (WBAG:POS) | €30.65 | €60.31 | 49.2% |
| Orthex Oyj (HLSE:ORTHEX) | €4.50 | €8.90 | 49.4% |
| Lindab International (OM:LIAB) | SEK128.30 | SEK251.92 | 49.1% |
| Koninklijke BAM Groep (ENXTAM:BAMNB) | €12.10 | €22.81 | 46.9% |
| Huuuge (WSE:HUG) | PLN23.40 | PLN45.58 | 48.7% |
| Grupa Pracuj (WSE:GPP) | PLN55.80 | PLN108.76 | 48.7% |
| DWS Group GmbH KGaA (XTRA:DWS) | €68.80 | €127.03 | 45.8% |
| Apator (WSE:APT) | PLN25.80 | PLN49.21 | 47.6% |
Here's a peek at a few of the choices from the screener.
Eiffage (ENXTPA:FGR)
Overview: Eiffage SA is a company that operates in the construction and concessions sectors across France, Germany, Europe, and internationally, with a market cap of €9.91 billion.
Operations: The company's revenue segments include Concessions (€4.26 billion), Construction (€4.28 billion), Energy Systems (€8.30 billion), and Infrastructures (€9.63 billion).
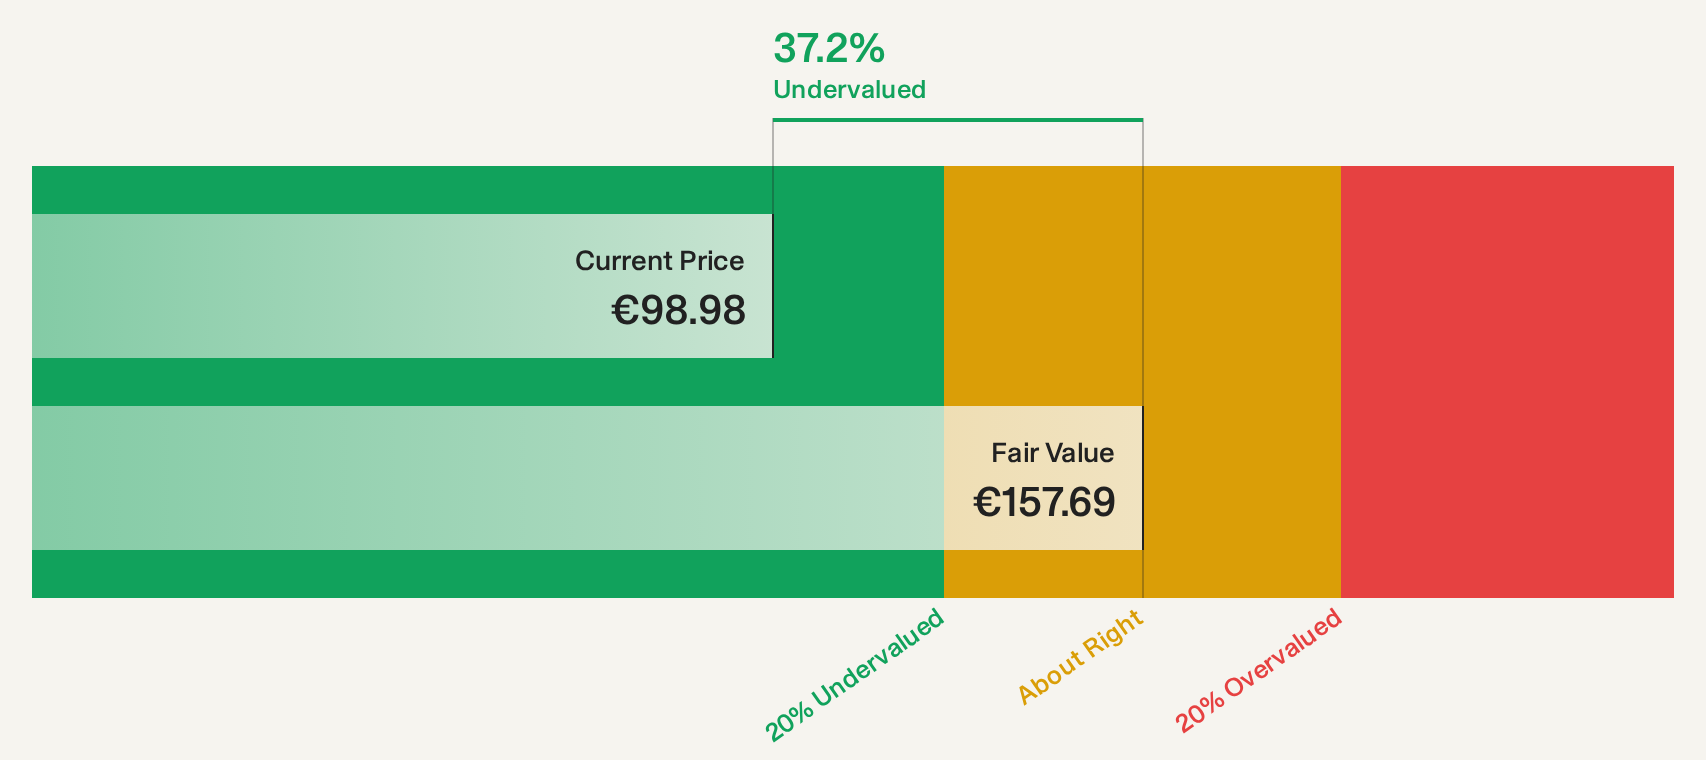
Estimated Discount To Fair Value: 37.5%
Eiffage appears undervalued based on cash flows, trading significantly below its estimated future cash flow value of €163.18. Earnings are expected to grow at 6.55% annually, though slower than the French market's forecasted growth rate. Recent contracts in infrastructure and waste-to-energy projects bolster its revenue streams, yet high debt levels and an unstable dividend history present challenges. Despite this, analysts anticipate a potential stock price increase of 54.2%.
- Our comprehensive growth report raises the possibility that Eiffage is poised for substantial financial growth.
- Delve into the full analysis health report here for a deeper understanding of Eiffage.
Lisi (ENXTPA:FII)
Overview: Lisi S.A. is a company that designs and produces assembly and component solutions for the aerospace, automotive, and medical sectors both in France and internationally, with a market capitalization of €2.74 billion.
Operations: The company's revenue is primarily derived from its LISI Aerospace segment, which generated €1.25 billion, followed by the LISI Automotive segment with €546.32 million.
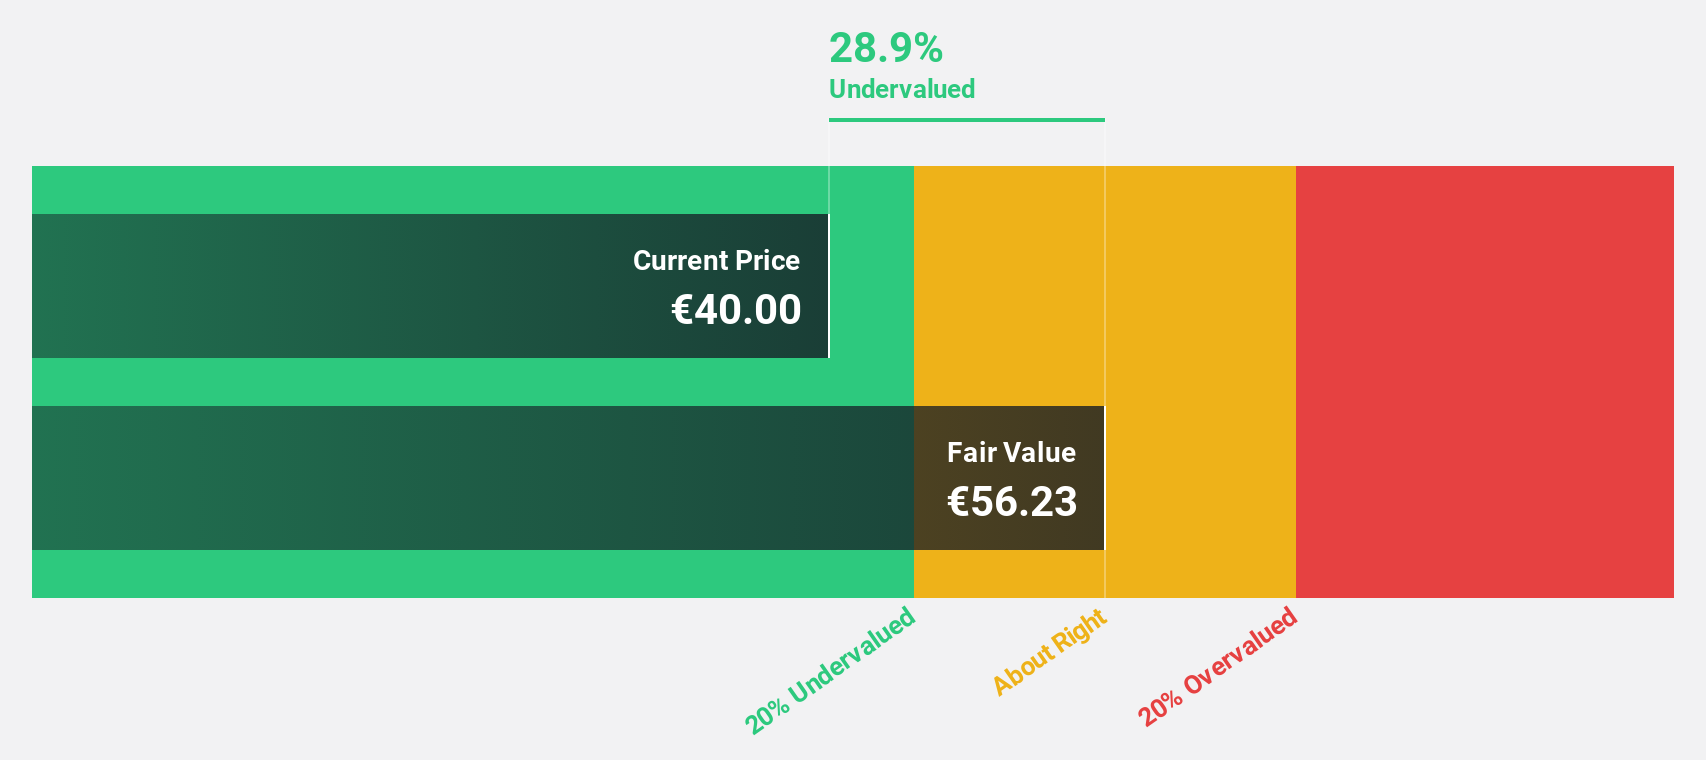
Estimated Discount To Fair Value: 24.7%
Lisi is trading 24.7% below its estimated future cash flow value of €79.11, suggesting it may be undervalued. The company reported strong earnings growth for the first half of 2026, with net income rising to €62.44 million from €38.51 million a year ago and basic EPS increasing to €1.36 from €0.84. Analysts forecast annual earnings growth of 26.9%, outpacing the French market, although revenue growth is expected to be moderate at 9.3%.
- The analysis detailed in our Lisi growth report hints at robust future financial performance.
- Click to explore a detailed breakdown of our findings in Lisi's balance sheet health report.
KWS SAAT SE KGaA (XTRA:KWS)
Overview: KWS SAAT SE & Co. KGaA is involved in breeding, producing, and distributing agricultural seeds and has a market capitalization of €2.24 billion.
Operations: The company generates revenue from several segments, including Corn (€433.63 million), Cereals (€263.94 million), Sugarbeet (€854.22 million), and Vegetables (€67.56 million).
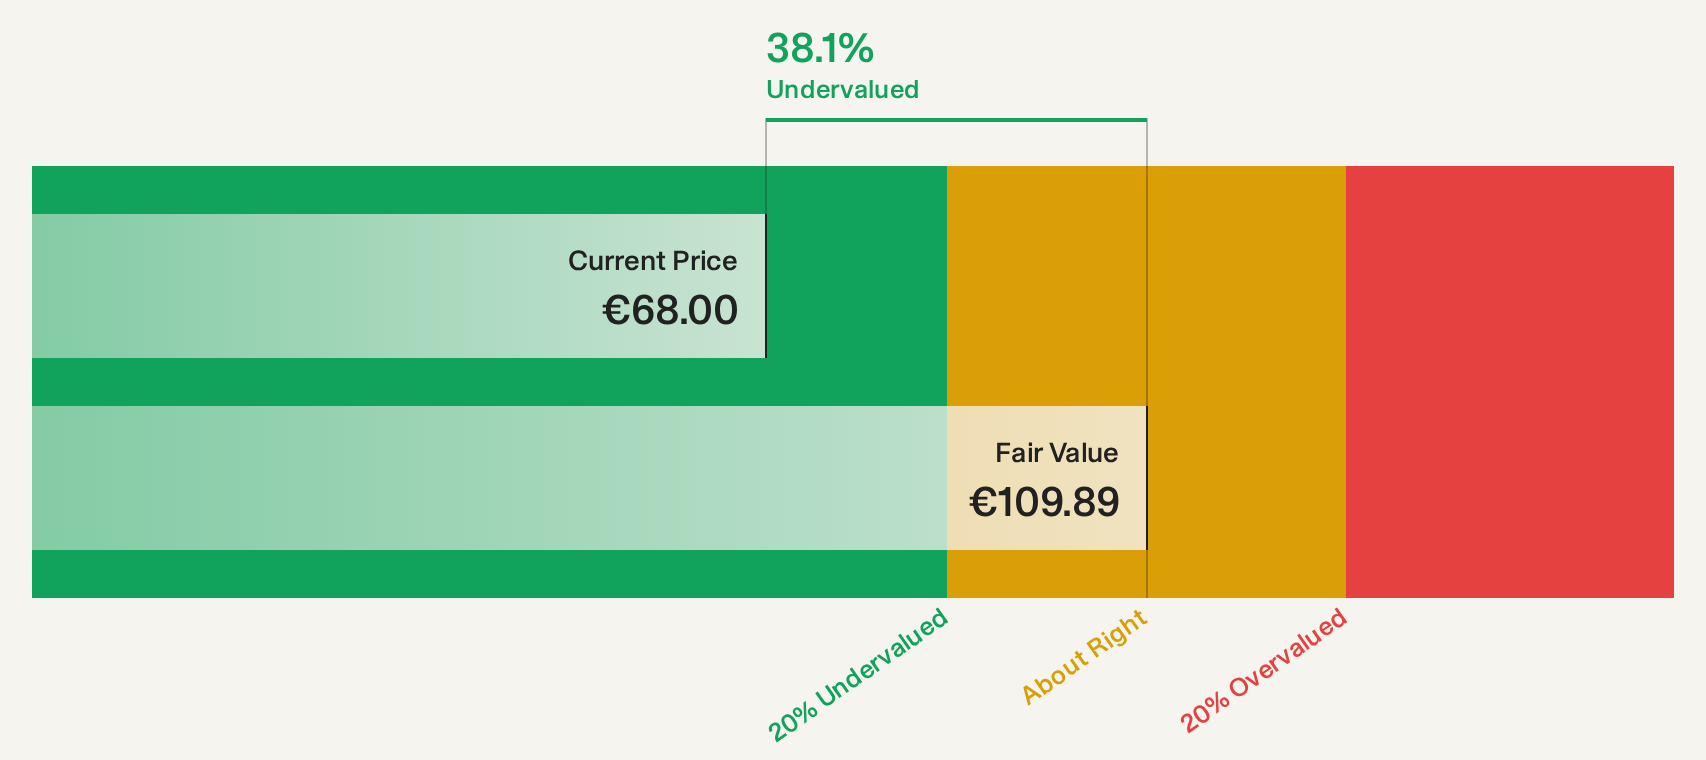
Estimated Discount To Fair Value: 38.1%
KWS SAAT SE & Co. KGaA is trading significantly below its estimated future cash flow value of €109.89, with a current price of €68, reflecting potential undervaluation. Despite a decline in net income to €160.84 million for the year ended June 30, 2026, earnings per share from continuing operations rose to €4.8 from €4.24 the previous year. Analysts expect moderate earnings growth at 6.56% annually, though slower than the German market average of 14.6%.
- Our growth report here indicates KWS SAAT SE KGaA may be poised for an improving outlook.
- Click here and access our complete balance sheet health report to understand the dynamics of KWS SAAT SE KGaA.
Key Takeaways
- Embark on your investment journey to our 57 Undervalued European Stocks Based On Cash Flows selection here.
- Are these companies part of your investment strategy? Use Simply Wall St to consolidate your holdings into a portfolio and gain insights with our comprehensive analysis tools.
- Simply Wall St is your key to unlocking global market trends, a free user-friendly app for forward-thinking investors.
Ready For A Different Approach?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com