


PPG Industries, Inc. (PPG), headquartered in Pittsburgh, Pennsylvania, manufactures and distributes paints, coatings, and specialty materials. Valued at $23.4 billion by market cap, the company makes protective and decorative coatings, flat glass, fabricated glass products, continuous-strand fiber glass products, and industrial and specialty chemicals. The leading paints and coatings manufacturer is expected to announce its fiscal third-quarter earnings for 2026 after the market closes on Tuesday, Oct. 27.
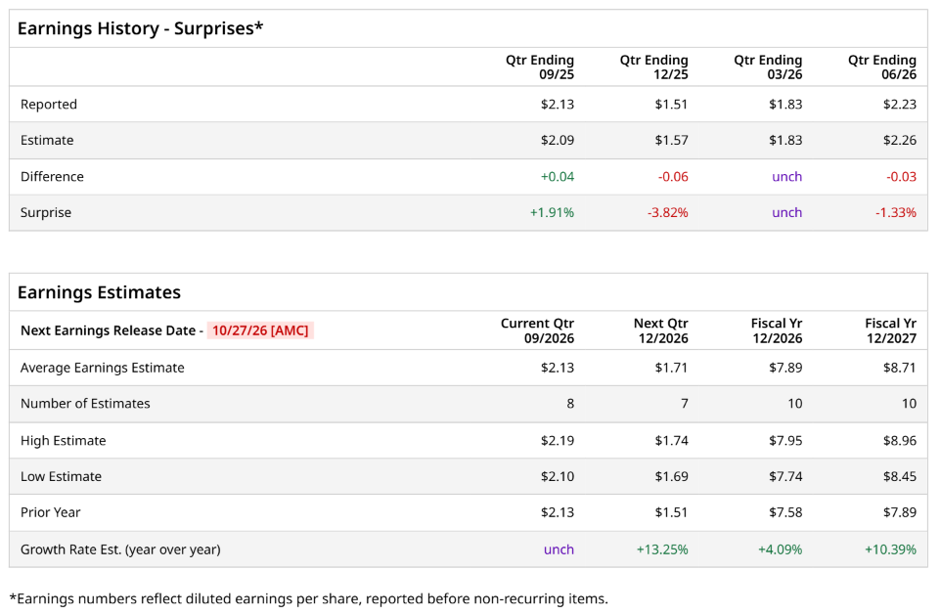
Ahead of the event, analysts expect PPG Industries to report a profit of $2.13 per share on a diluted basis, unchanged from the year-ago quarter. The company beat or matched the consensus estimates in two of the last four quarters while missing the forecast on two other occasions.
For the full year, analysts expect PPG Industries to report EPS of $7.89, up 4.1% from $7.58 in fiscal 2025. Its EPS is expected to rise 10.4% year over year to $8.71 in fiscal 2027.
PPG stock has underperformed the S&P 500 Index’s ($SPX) 16% gains over the past 52 weeks, with shares up 2.9% during this period. Similarly, it underperformed the State Street Materials Select Sector SPDR ETF’s (XLB) 10.8% gains over the same time frame.
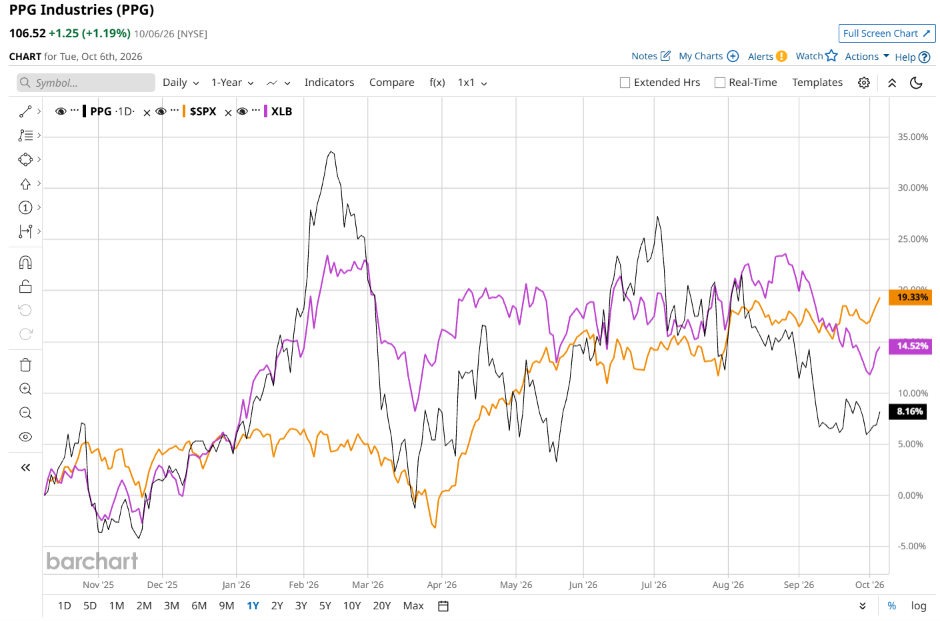
PPG has underperformed due to persistent volume declines across key end-markets such as commercial construction and general manufacturing alongside specific segment drag within its automotive refinish coatings division, where lower body shop demand and shifting customer ordering patterns squeezed margins. Compounding these volume headwinds, input cost inflation across raw materials, energy, and logistics continuously challenged profitability, leading to mixed quarterly earnings execution. Additionally, sluggish economic recovery in European and Asian architectural coatings markets combined with investor caution over future margin expansion timing has weighed heavily on market sentiment, offsetting strength in high-margin segments like aerospace.
On Jul. 28, PPG reported its Q2 results, and its shares closed down more than 6% in the following trading session. Its adjusted EPS of $2.23 did not meet Wall Street expectations of $2.26. The company’s revenue was $4.5 billion, topping Wall Street forecasts of $4.4 billion. PPG expects full-year adjusted EPS in the range of $7.70 to $8.10.
Analysts’ consensus opinion on PPG stock is moderately bullish, with a “Moderate Buy” rating overall. Out of 24 analysts covering the stock, 11 advise a “Strong Buy” rating, and 13 give a “Hold.” PPG’s average analyst price target is $125.28, indicating a potential upside of 17.6% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.