


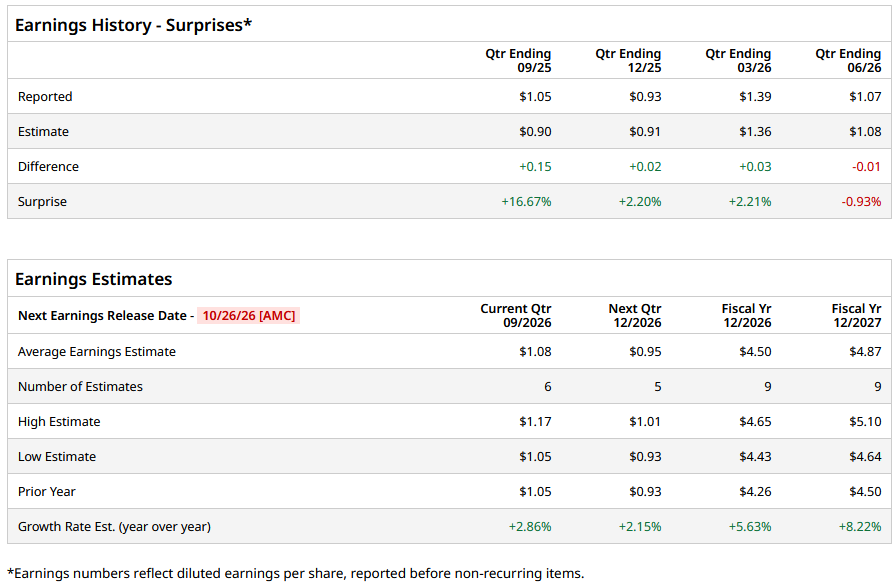
Daytona Beach, Florida-based Brown & Brown, Inc. (BRO) markets and sells insurance products and services in the United States and internationally. Valued at a market cap of $20.4 billion, the company operates through Retail and Specialty Distribution segments and provides property and casualty insurance, employee benefits insurance, personal insurance, specialty insurance, and more. BRO is expected to release its Q3 2026 earnings on Monday, October 26, after the market closes.
Ahead of the event, analysts expect the company’s EPS to be $1.08 on a diluted basis, up 2.9% from $1.05 in the year-ago quarter. The company has exceeded Wall Street’s EPS estimates in three of its last four quarters, while missing on one occasion.
For fiscal 2026, analysts project the company’s EPS to be $4.50, up 5.6% from $4.26 in fiscal 2025. Moreover, its EPS is expected to rise by roughly 8.2% year over year (YoY) to $4.87 in fiscal 2027.
BRO stock has fallen 35.4% over the past 52 weeks, lagging behind the S&P 500 Index’s ($SPX) 16% rise and the State Street Financial Select Sector SPDR ETF’s (XLF) marginal rise during the same time frame.
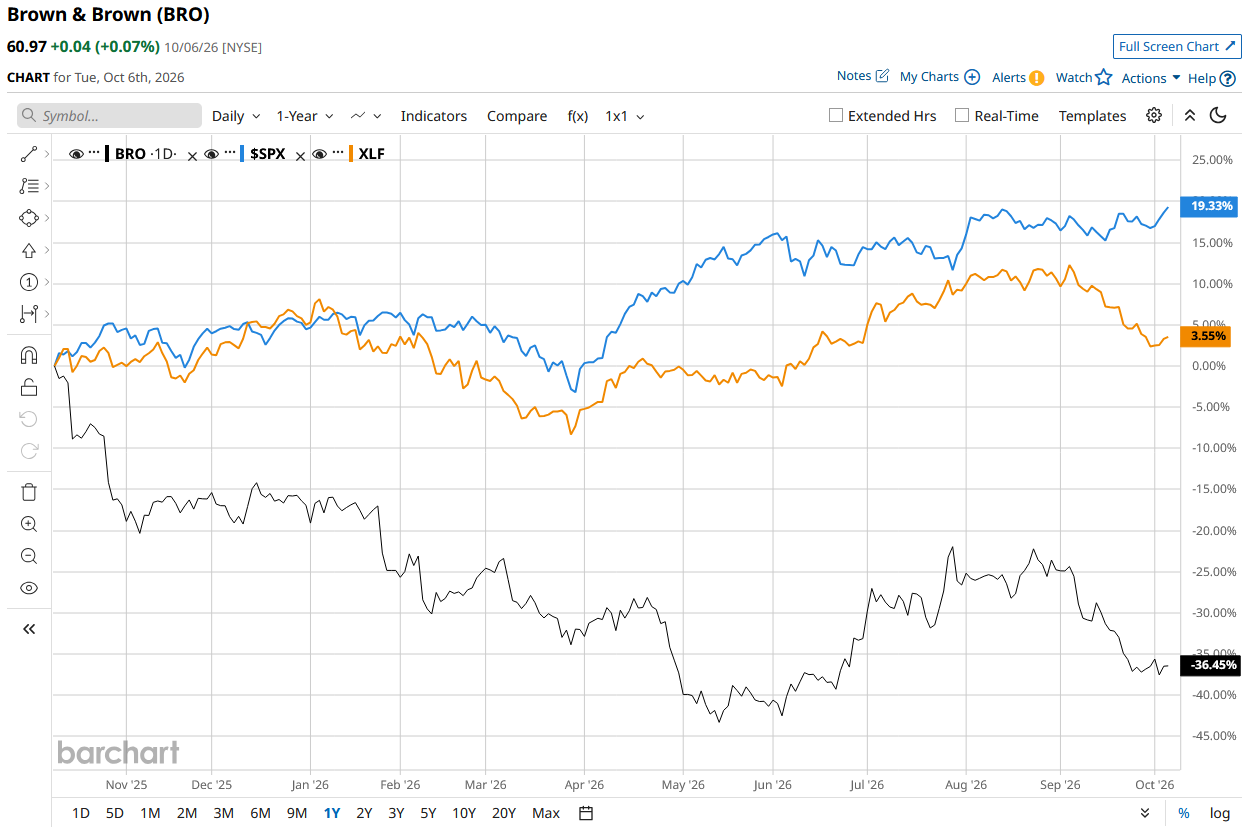
On July 28, BRO stock rose 5.7% after it released mixed Q2 2026 earnings. The company’s revenue for the period rose by a robust 30.4% from the prior year’s quarter to $1.7 billion, but missed the consensus estimates. Moreover, its adjusted EPS came in at $1.07, which was in line with Wall Street’s forecasts. Investors looked past the revenue shortfall and focused on strong year-over-year growth and in-line earnings.
Analysts are unsure about BRO, with the stock having a “Hold” rating overall. Among the 22 analysts covering the stock, three are recommending a “Strong Buy,” one recommends a “Moderate Buy,” 17 suggest a “Hold,” and one suggests a “Moderate Sell” for the stock. BRO’s average analyst price target is $74.35, indicating an upside of 21.9% from the current levels.
On the date of publication, Aritra Gangopadhyay did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.