


Jiangxi Copper (SEHK:358) just locked in a three year agreement to supply materials and services to JCC Group from January 2027, giving investors a fresh data point on contract visibility and partner demand.
Jiangxi Copper’s new JCC Group agreement lands after a mixed share price stretch, with the stock down 23.58% year to date on a share price basis and off 8.8% over the past month. It still shows a 221.23% total shareholder return over three years, which signals earlier momentum and leaves recent weakness looking more like a pause than a reset in the longer story.
Compare Jiangxi Copper’s contract driven story with other stocks exposed to the same theme by scanning our hand picked list of 16 top copper producer stocks today.
Jiangxi Copper now has a sizeable contract lined up while the share price has pulled back sharply this year. Does that set up a reasonable entry today, or is patience on price still your better ally before the valuation work starts?
Preferred P/E of 8.5x for Jiangxi Copper: Is it justified?
On a headline valuation check, Jiangxi Copper trades on a P/E of 8.5x, which screens as inexpensive compared to both peers and the wider Hong Kong Metals and Mining group.
P/E compares the current share price to earnings per share and is often used for mature, cash generating businesses where profits matter more than top line expansion. For a miner such as Jiangxi Copper, this ratio gives you a quick sense of how much the market is willing to pay for each unit of current earnings, knowing that commodity cycles and contract visibility both influence what those earnings might look like over time.
Relative value is where the picture gets more interesting. Jiangxi Copper is flagged as good value versus its direct peer set on a P/E basis, trading at 8.5x compared with a peer average of 10.9x. It is also described as good value relative to the Hong Kong Metals and Mining industry, where the typical P/E sits at 10.2x. Against an estimated fair P/E of 9x, the current multiple still comes in lower. This suggests the market could move closer to that fair ratio if earnings quality and growth forecasts hold up.
Explore the SWS fair ratio for Jiangxi Copper.
Result: Price-to-earnings of 8.5x (UNDERVALUED)
Still, Jiangxi Copper’s reliance on commodity pricing and continued capital demands across mining and smelting could easily knock that low P/E narrative off course.
Find out about the key risks to this Jiangxi Copper narrative.
Another view on Jiangxi Copper’s value
The story looks different when switching to our DCF model. On this approach, Jiangxi Copper at HK$33.38 sits below an estimated fair value of HK$44.31, which points to a sizeable valuation gap. Is that a margin of safety or just the model being too generous about future cash flows?
For readers who want to see the moving parts behind that cash flow view, Look into how the SWS DCF model arrives at its fair value.
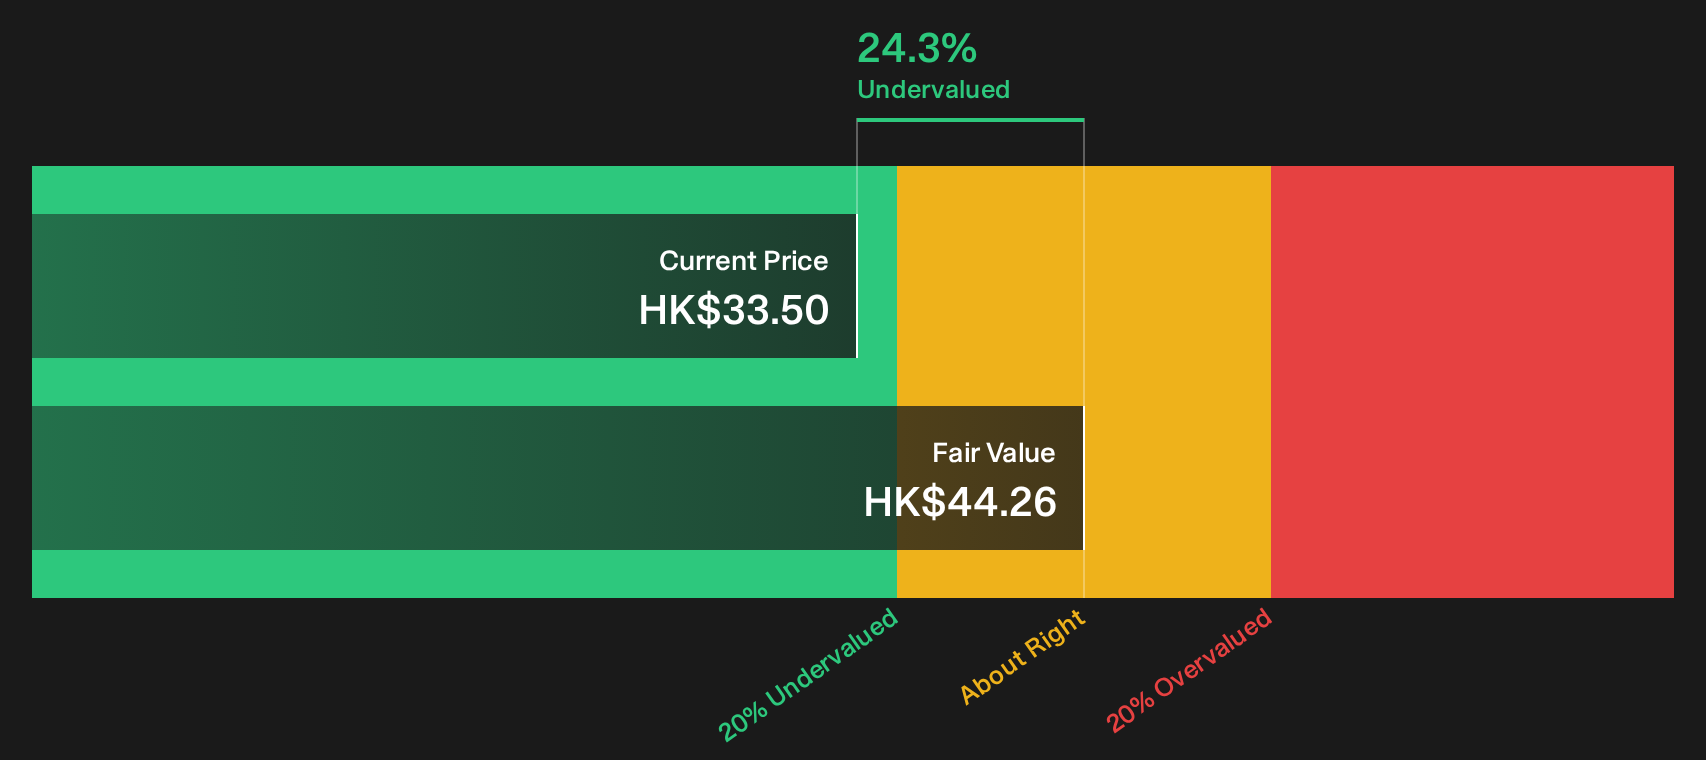
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Jiangxi Copper for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 181 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or early opportunity? If you want a clearer picture before the next move, weigh the upside against the downside by checking the 4 key rewards and 1 important warning sign.
Looking for more Jiangxi Copper style ideas?
Do not stop with Jiangxi Copper alone. Broaden your watchlist now, or you may miss opportunities setting up quietly while attention stays on headline names.
- Target mispriced quality by scanning our 181 high quality undervalued stocks that combine stronger fundamentals with what could be more modest expectations baked into current prices.
- Strengthen your income basket by reviewing 165 dividend fortresses that pair higher yields with businesses focused on ongoing shareholder payouts.
- Dial down portfolio stress by filtering for 228 resilient stocks with low risk scores that score better on balance sheet resilience and business stability metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com