


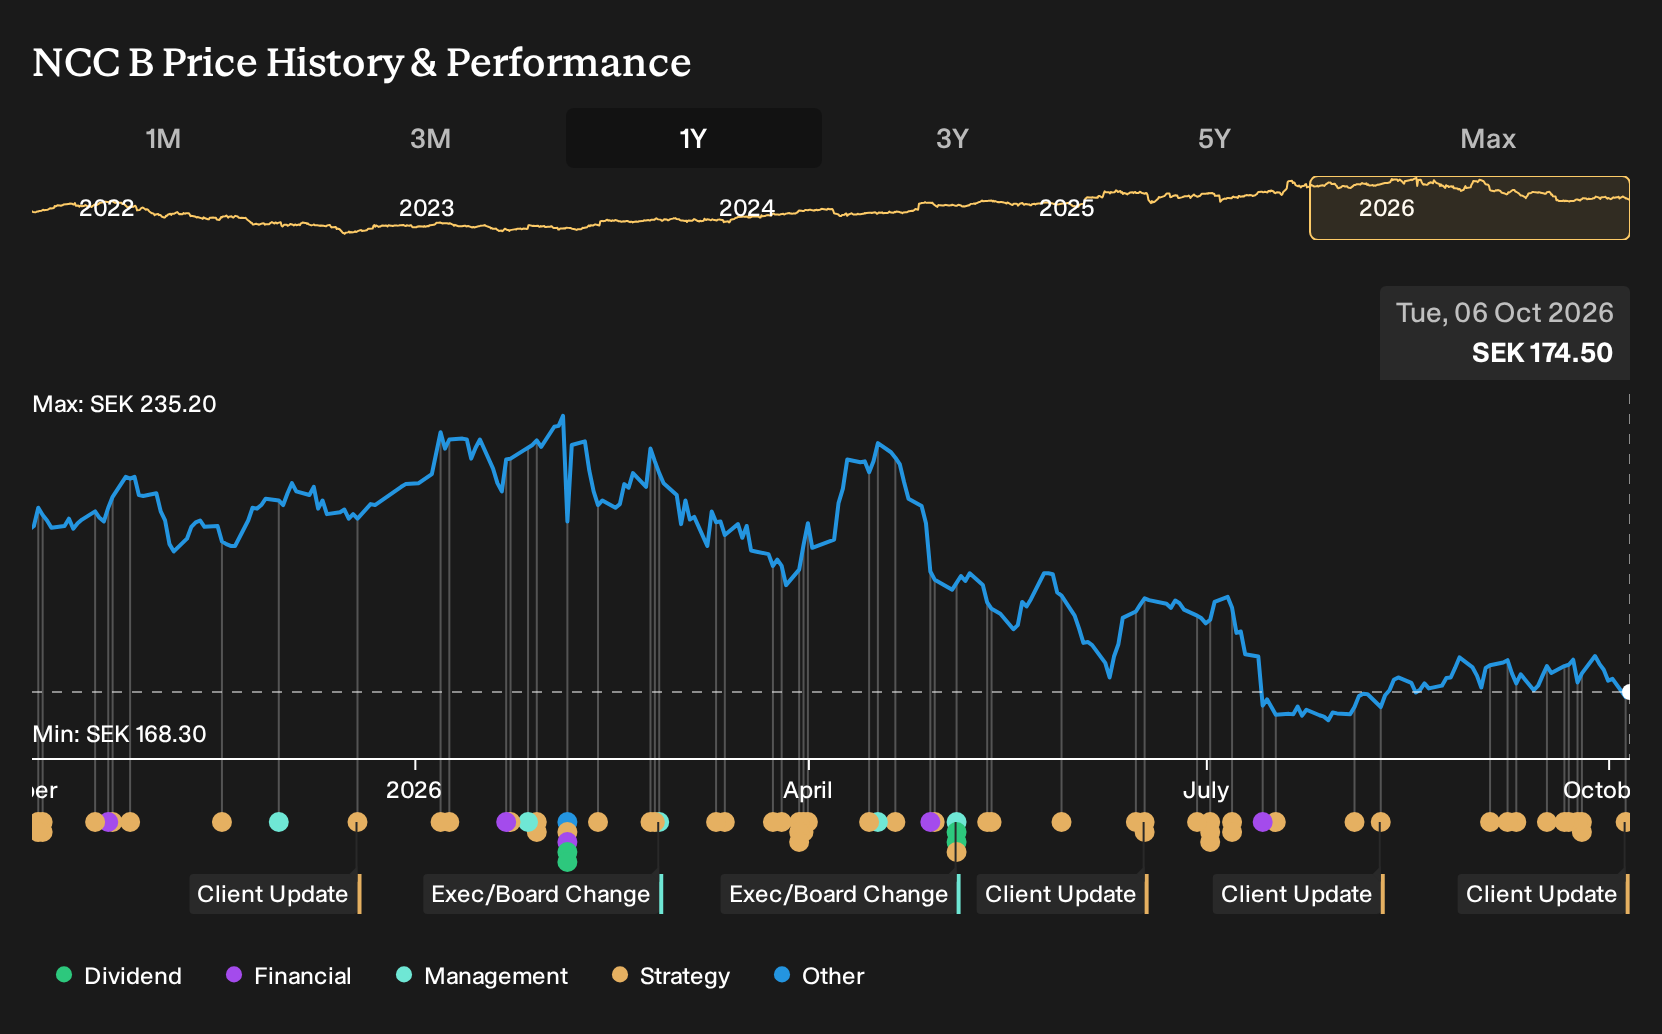
- NCC reported several new commissions, including a SEK 1 b power line contract with Svenska kraftnät and two Turku projects worth about SEK 380 m covering residential conversion and a new nursing home.
- These orders expand NCC's Nordic infrastructure and social property workload, increasing contracted visibility across the Infrastructure and Building Nordics segments.
- We will now see how NCC's investment narrative could be influenced by the SEK 1 b Horred Breared power line contract.
NCC Investment Narrative Recap
To own NCC, you need to believe the construction group can turn a solid Nordic order book into cleaner, more predictable earnings despite thin margins today and a high debt load. The immediate swing factor is execution on existing contracts rather than new headline deals. The fresh power grid and Turku wins support contracted activity, but do not change that near term focus.
The biggest operational risk still sits in low profitability, one off items and a dividend that recent earnings and cash flows have not fully covered. Currency swings, weak property transactions and pricing pressure in Sweden and Finland remain background threats that this latest batch of orders does not materially reduce.
The Horred Breared project with Svenska kraftnät is the clearest link to NCC’s catalyst list around infrastructure and energy related work. A SEK 1 b, 70 km, 400 kV line moving into full scale production gives the Infrastructure segment multi year visibility and directly ties into the grid upgrade theme many investors look for.
For you, the key question is whether management can deliver this complex contract on time and on budget while still managing competitive pressure and balance sheet risk. Any cost overruns or delays would feed into already tight margins. Smooth execution, by contrast, would support the idea that NCC can convert its infrastructure backlog into steadier earnings over the next few years.
NCC's current analyst narrative points to SEK 64.5b revenue and SEK 2.7b earnings by 2029, based on a 6.1% yearly revenue growth rate and an earnings step up of about SEK 2.6b from SEK 78.0m today.
Uncover why NCC's fair value indicates a 16% potential upside to its current price that could close more quickly than many investors expect.
Exploring Other Perspectives
Bearish analysts focus on dispute costs rather than grid and Turku wins, and that gives you a very different NCC story. They were pencilling in SEK 62.8b revenue and SEK 2.0b earnings by 2029, versus the SEK 64.5b and SEK 2.7b consensus view. Both sets of forecasts came before this contract news, so opinions may now shift as you reassess the range.
Explore 2 other NCC fair value estimates, including one that suggests it could be worth just SEK 197.98.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis and judgment.
- A great starting point for your NCC research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for NCC. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NCC's overall financial health at a glance.
Looking For More Investment Ideas Beyond NCC?
If this NCC update has sharpened your thinking but you want a wider field of options, a focused stock screener can help you quickly line up companies that better match your risk tolerance, income needs, or value style.
- If you want potential value opportunities backed by solid fundamentals and cash generation, start with our 181 high quality undervalued stocks that already meet strict quality filters.
- For investors who care most about income resilience, narrow your search to companies in our 165 dividend fortresses that aim to pair higher yields with sturdier balance sheets.
- If capital preservation matters more than chasing every rally, filter for companies in our 228 resilient stocks with low risk scores where business stability and lower risk scores are the priority.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com