


Fresh analyst call puts Engie in focus
Morgan Stanley’s renewed Overweight stance on Engie (ENXTPA:ENGI) has pushed the stock back onto investor watchlists, with earnings momentum and upcoming project updates now under closer scrutiny.
The broker highlighted three focal points for Engie: clearer valuation of French gas networks, progress on the Belgian nuclear agreement, and execution on a multibillion-euro asset disposal program that could reshape the group’s profile.
Engie’s share price has moved to €23.45 after a 2.5% 1-day gain and a 1.9% 7-day share price return. The stock is still down 12.4% on a 90-day view, while the 1-year total shareholder return of 33.4% and 5-year total shareholder return of around 3x suggest that longer term momentum has been much stronger than the recent pullback.
Compare Morgan Stanley’s Engie call with other potential utilities opportunities by scanning our hand picked 44 power grid technology and infrastructure stocks tied to critical energy infrastructure themes.
After a sharp rebound from the recent 90 day slide, Engie now sits closer to the middle of its recent range. Investors may be weighing whether it makes more sense to step in at this level or wait for a potentially cheaper entry as the valuation work unfolds.
Most Popular Narrative: 23% Undervalued
Engie’s most followed valuation story points to a fair value of about €30.54, which sits well above the last close at €23.45, so the current share price is being compared against a narrative that leans on long term energy transition projects and relatively measured risk assumptions.
Strategic expansion in renewables and energy storage, highlighted by nearly 53 GW of installed renewables/BESS capacity and a 118 GW development pipeline diversified across multiple geographies, positions Engie to capture an outsized share of the multi-decade shift to clean energy, supporting sustainable top-line and earnings growth.
See why 97 investors see Engie as 23% undervalued.
Result: Fair Value of €30.54 (UNDERVALUED)
Still, Engie’s story can change quickly if FX pressure in Brazil bites harder or if regulatory shifts delay those big-ticket renewables and hydrogen projects.
Find out about the key risks to this Engie narrative.
Another View On Engie’s Valuation
There is a sharp contrast once the SWS DCF model is brought in. While the popular narrative points to fair value around €30.54 and says Engie looks undervalued, that cash flow model lands closer to €15.15 per share. This result implies the stock could be overpriced. Which perspective do you think matches the level of risk you are willing to take?
Look into how the SWS DCF model arrives at its fair value.
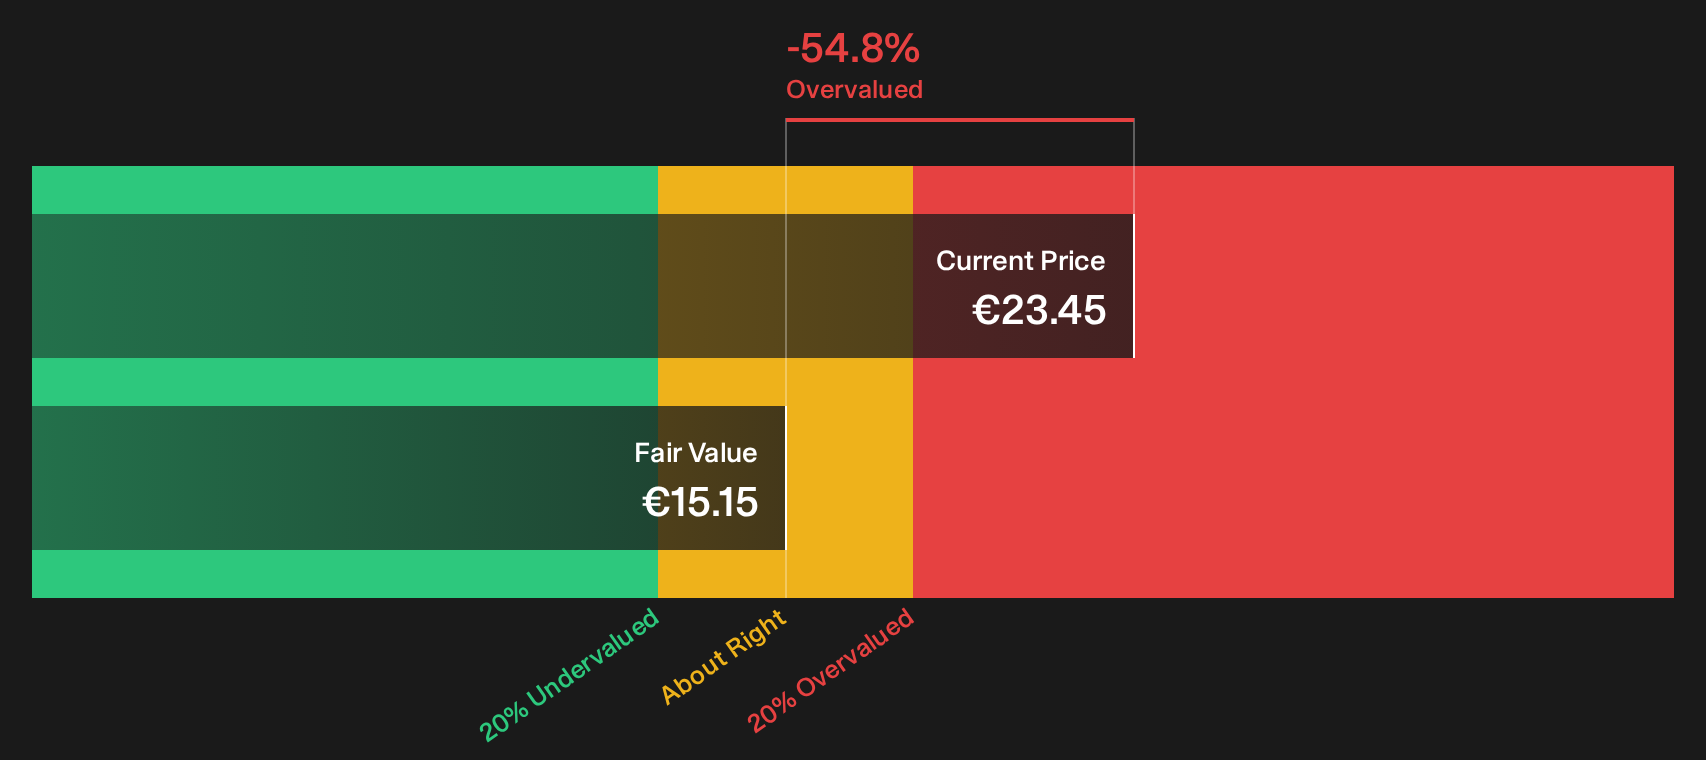
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Engie for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 181 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the split sentiment around Engie leaves you unsure, act promptly, review the evidence yourself, and then weigh the 4 key rewards and 2 important warning signs.
Looking for more Engie sized investment ideas?
Do not stop with Engie. Use the Simply Wall St Screener to surface fresh opportunities that match your risk appetite, time horizon, and income goals.
- Target income resilience by focusing on companies in our 166 dividend fortresses that may help support a steadier stream of cash returns.
- Hunt for quality at a discount by working through the 181 high quality undervalued stocks that combine fundamentals with more appealing prices.
- Dial back portfolio volatility by filtering companies in the 228 resilient stocks with low risk scores so you are not the last to react when conditions change.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com