


AI is now shaping where capital flows, and the IMF is warning that the benefits are concentrating in a small group of winners. Income investors watching this play out may not want to rely only on high yield or cash. A middle path exists. Growing dividend payers with moderate 2% to 5% yields can offer rising income. This article highlights three such stocks from our screener worth a closer look.
The three examples below are only a starting sample from this theme, and the full screen surfaced 49 more income oriented businesses with equally compelling dividend stories that are not covered here. To go directly to the full universe, analyze and refine your own shortlist inside the Growing Dividend Payers with 2-5% yield screener.
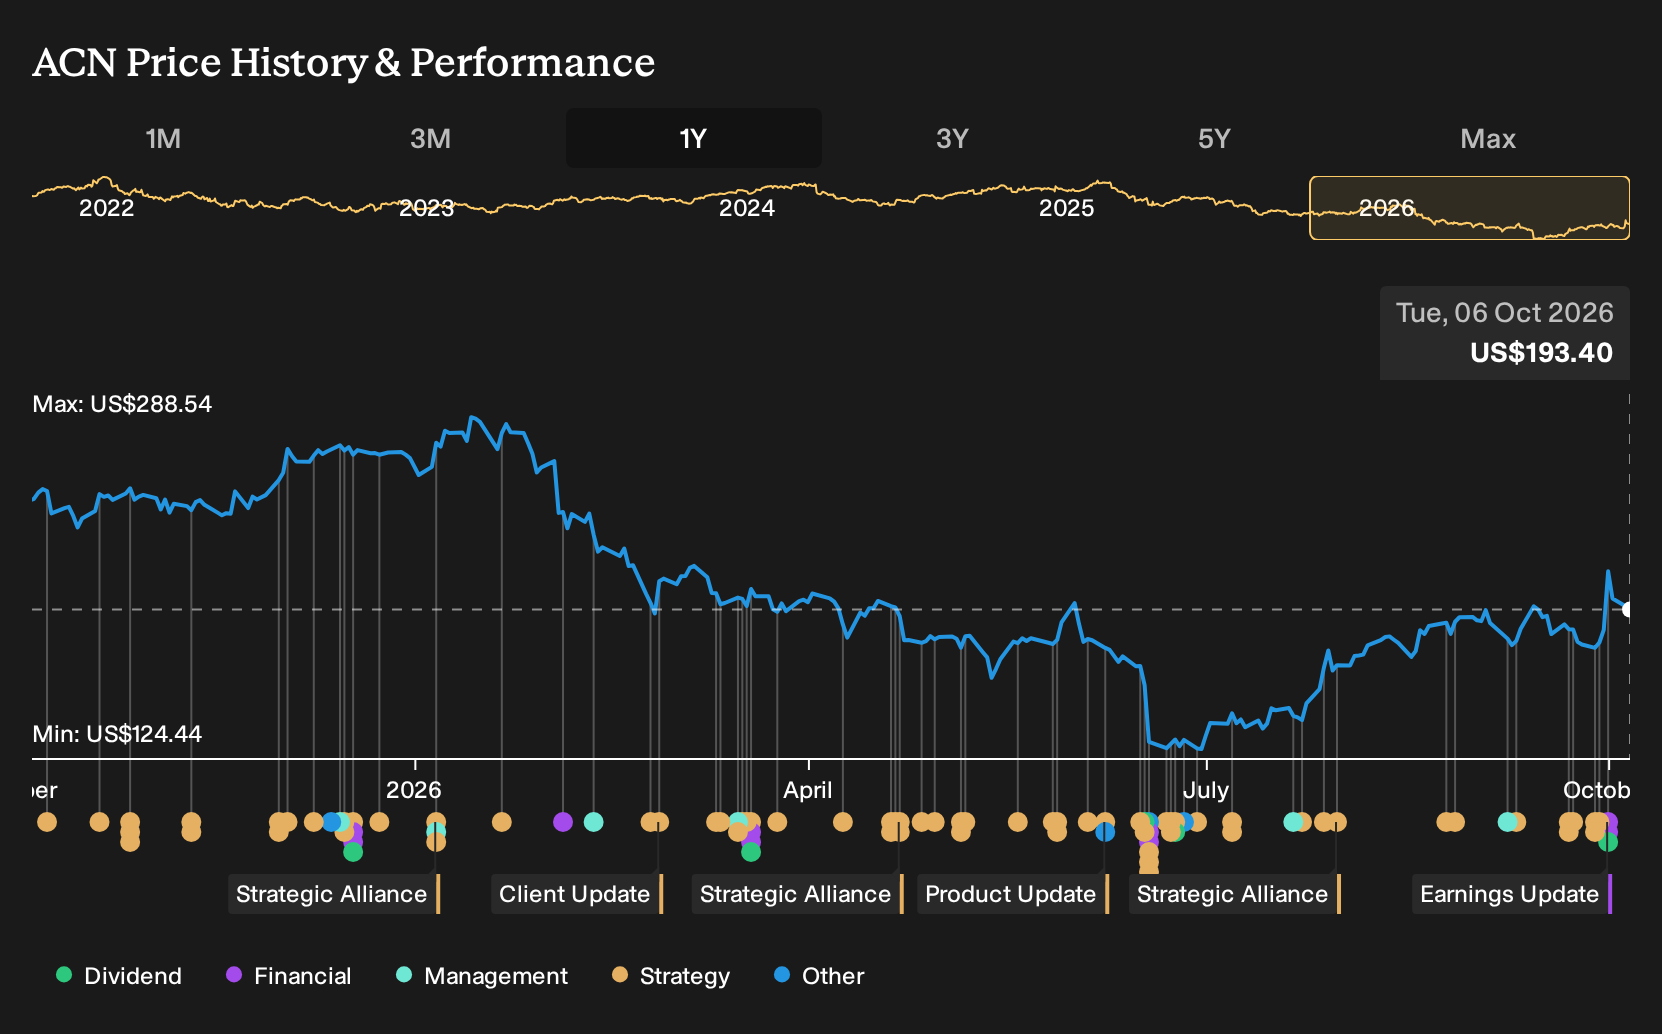
Accenture (ACN)
Accenture plugs directly into this growing dividend payer theme because its core work is helping large clients build and run cloud, AI, and automation systems. This can support steady earnings and room for ongoing payouts rather than chasing very high yields.
"AI could reduce the need for traditional consulting, coding, testing, documentation, support, and outsourcing roles."
What really matters for Accenture is how one quiet shift in where clients spend their technology budgets ends up feeding through to margins.
That quiet budget shift is exactly what sits behind the full narrative for Accenture, where Accenture’s AI risk, pricing power and dividend headroom are pulled together in one accelerating story.
PepsiCo (PEP)
PepsiCo is a global beverages and snacks heavyweight, where brands such as Pepsi, Gatorade, Lay’s and Quaker help power the kind of steady cash generation that fits the “growing dividend payers with 2–5% yield” brief.
PepsiCo runs a broad consumer staples portfolio, with PepsiCo Beverages North America generating about US$29.2b in revenue and PepsiCo Foods North America around US$27.5b, alongside Latin America Foods at roughly US$11.2b, EMEA at US$18.9b, International Beverages Franchise at US$5.2b, and Asia Pacific Foods at US$4.9b, underpinned by a market value near US$171.5b.
For income investors, PepsiCo brings something different to this list. You get an entrenched consumer staples player whose core drinks and snacks already fund a long dividend record. The real intrigue lies in where the next leg of cash flow support might come from.
"The company is pushing into functional and health-focused drinks with the acquisition of Poppi (prebiotic soda), ownership of Bubly (sparkling water), and a partnership with Celsius (including Rockstar energy drinks)."
The real test for PepsiCo’s dividend story may come from how one quiet squeeze on costs and efficiency shapes margins over the next few years.
Those cost decisions are exactly where the story gets interesting, and the full narrative for PepsiCo shows how PepsiCo’s cash engine, capital expenditures, and payout ambitions are really interacting.

Public Storage (PSA)
Public Storage gives this income theme a very different engine, because the self storage REIT model leans on thousands of small, recurring leases that can underpin a 2 to 5% dividend yield while still leaving room for measured payout growth.
Public Storage is a large US REIT that acquires, develops, owns, and operates self storage facilities, with about US$4.5b coming from self storage, US$355 million from ancillary operations, and roughly US$20 million from equity earnings, supported by a market value near US$54.7b.
"Expansion of PS Next and PS4.0 initiatives, such as high digital adoption, AI assisted customer service, and machine learning based staffing that has reduced field labor hours and payroll expense, is expected to support operating efficiency and margin resilience as the platform matures."
What could really reshape the dividend story is how one quiet shift in where operating savings are reinvested feeds through to long term cash generation.
Those reinvestment choices are only part of the picture, and the full narrative for Public Storage shows how Public Storage’s efficiency push could be masking bigger cash flow shifts ahead.

Seeking Fresh Alternatives Before They Fly
Fresh ideas move first, and the strongest themes often show breakout momentum while most investors are still caught watching old stories dropping out of focus. Scan what is still under the radar for now and get in early.
- Target resilient compounders by tapping into the 31 resilient stocks with low risk scores that have been filtered for balance sheet strength and business durability while that edge still matters.
- Hunt for underfollowed opportunities with the 19 high quality undiscovered gems before wider attention arrives and pricing power from early insight starts slipping away.
- Ride structural demand shifts through the 44 power grid technology and infrastructure stocks as capital flows into critical infrastructure plays that may gain momentum before crowd interest accelerates.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com