


Stifel Financial (SF) is hosting its Stifel Virtual Cardiometabolic Forum on 30 September 2026, highlighting the broker’s focus on healthcare and cardiometabolic trends that matter for institutional and wealth management clients.
Recent trading has been tougher for Stifel Financial, with the share price at about $70.12 and down 13.95% over the past month, while a 3-year total shareholder return of 84.55% suggests longer term holders have still seen strong gains.
Scan beyond Stifel Financial and compare it with a hand-picked list of solid balance sheet and fundamentals (25 results) that may also be positioned to benefit from long-term demand for financial advice around complex health themes.
After a sharp 30 day slide and a much softer 1 year return, the question for Stifel Financial now is whether most of the easy upside has already played out, or if valuation still leaves meaningful room ahead.
Price-to-Earnings of 11.6x: Is it justified?
Valuation for Stifel Financial currently leans on a relatively modest P/E of 11.6x, which sits well below many peers even after the recent share price slide to $70.12.
The P/E ratio compares what investors pay today for each dollar of earnings, and for a diversified financial group like Stifel Financial that matters because profit can swing with deal activity, trading volumes, and client sentiment.
Here the market is assigning a lower multiple than both the broader US market on 18x earnings and the Capital Markets industry on 39.7x. Analysts still expect earnings to grow about 11.9% a year, and recent profit growth and margins have been strong. Against an estimated “fair” P/E of 12.9x, the current 11.6x level indicates investors are pricing the business more cautiously than that benchmark. If earnings forecasts hold, there may be scope for the valuation to move closer to that fair ratio.
That gap is also clear when comparing Stifel Financial with peers, where the 11.6x P/E sits under a 15.6x average and even further below the 39.7x industry figure, a strong relative discount that indicates the market is assigning a lower price to its earnings than many competitors.
Explore the SWS fair ratio for Stifel Financial.
Result: Price-to-Earnings of 11.6x (UNDERVALUED)
Still, the recent 1 year share price decline and softer year to date return show how quickly sentiment on Stifel Financial can turn if deal activity or client risk appetite cools.
Find out about the key risks to this Stifel Financial narrative.
Another View on Stifel Financial’s Value
A second lens tells a different story. Our DCF model estimates the future cash flow value of Stifel Financial at about $41.78 per share, which is well below the current $70.12 price. On this measure the stock screens as overvalued, so which signal should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
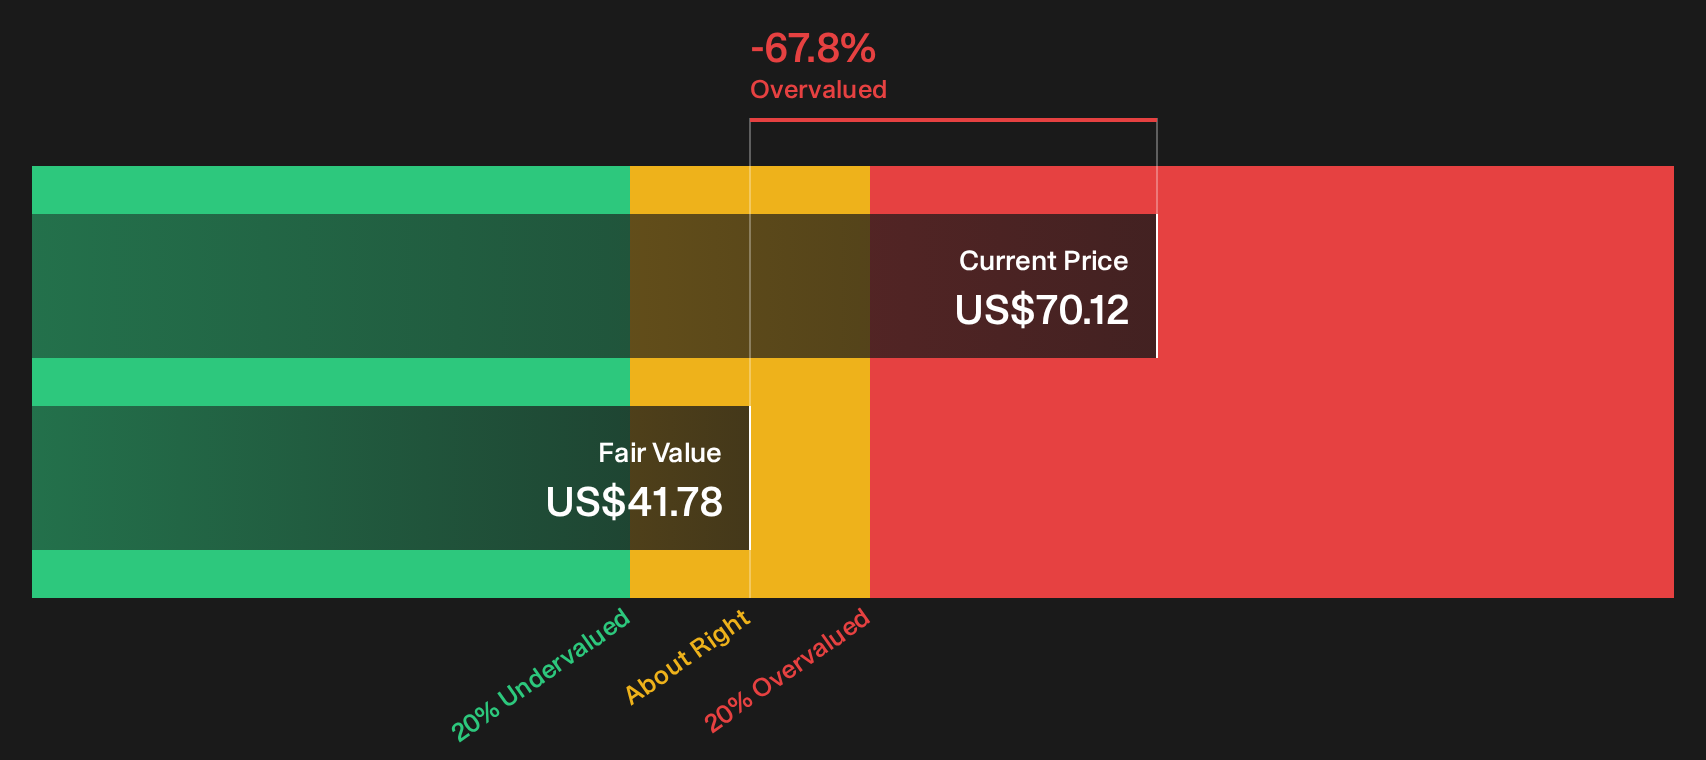
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Stifel Financial for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
See something different in this mix of risks and rewards around Stifel Financial? Act quickly, stress test the data, and then run your own filter over the 5 key rewards.
Looking for more Stifel Financial style investment ideas?
If Stifel Financial has your attention, do not stop here. Broader research through focused stock lists can reveal opportunities that fit your exact risk and return preferences.
- Target potential mispricing and hunt for quality at a discount with the 27 high quality undervalued stocks.
- Strengthen your income stream by scanning for dependable payers through the 8 dividend fortresses.
- Dial down portfolio stress and concentrate on resilience by filtering shares with the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com