


Leadership reshuffle at WSFS Financial
WSFS Financial (WSFS) has announced a series of senior leadership moves, including a new interim Chief Accounting Officer, a permanent Chief Audit Executive, and an expanded role for its top legal executive.
These appointments give investors new information to assess how the bank handles accounting oversight, internal audit, and governance at a time when regulatory expectations for regional lenders remain high.
At a share price of US$75.92, WSFS Financial has delivered a 37.91% year to date share price gain and a 42.41% total shareholder return over the past year. The more modest 0.84% 3 month share price return hints that earlier momentum has cooled, even as recent office expansion in Pennsylvania and this leadership reshuffle keep the story moving.
Spot similar regional banking stories in motion by scanning our curated list of solid balance sheet and fundamentals (25 results), which could appeal if WSFS Financial's governance moves and expansion catch your attention.WSFS Financial now blends long established banking roots with fresh governance moves and expansion into new Pennsylvania markets. The question is whether that mix is already fully reflected in a US$75.92 share price.
Most Popular Narrative: 14.6% Undervalued
On the most followed view of WSFS Financial, a fair value of about $88.92 sits above the recent $75.92 close. This frames this leadership shake up against a story that already bakes in higher long term earnings power than the current price implies.
Continuation of high core ROA and core ROTCE, together with capital levels above the stated CET1 target, provides room for WSFS Financial to keep returning a large portion of earnings through share repurchases, which can lift earnings per share even if overall revenue growth is modest.
See why 0 investors see WSFS Financial as 15% undervalued.
Result: Fair Value of $88.92 (UNDERVALUED)
Still, the WSFS Financial story can unravel if deposit costs rise faster than expected, or if Cash Connect fee income weakens further as rates decline.
Find out about the key risks to this WSFS Financial narrative.
Another view on WSFS Financial's valuation
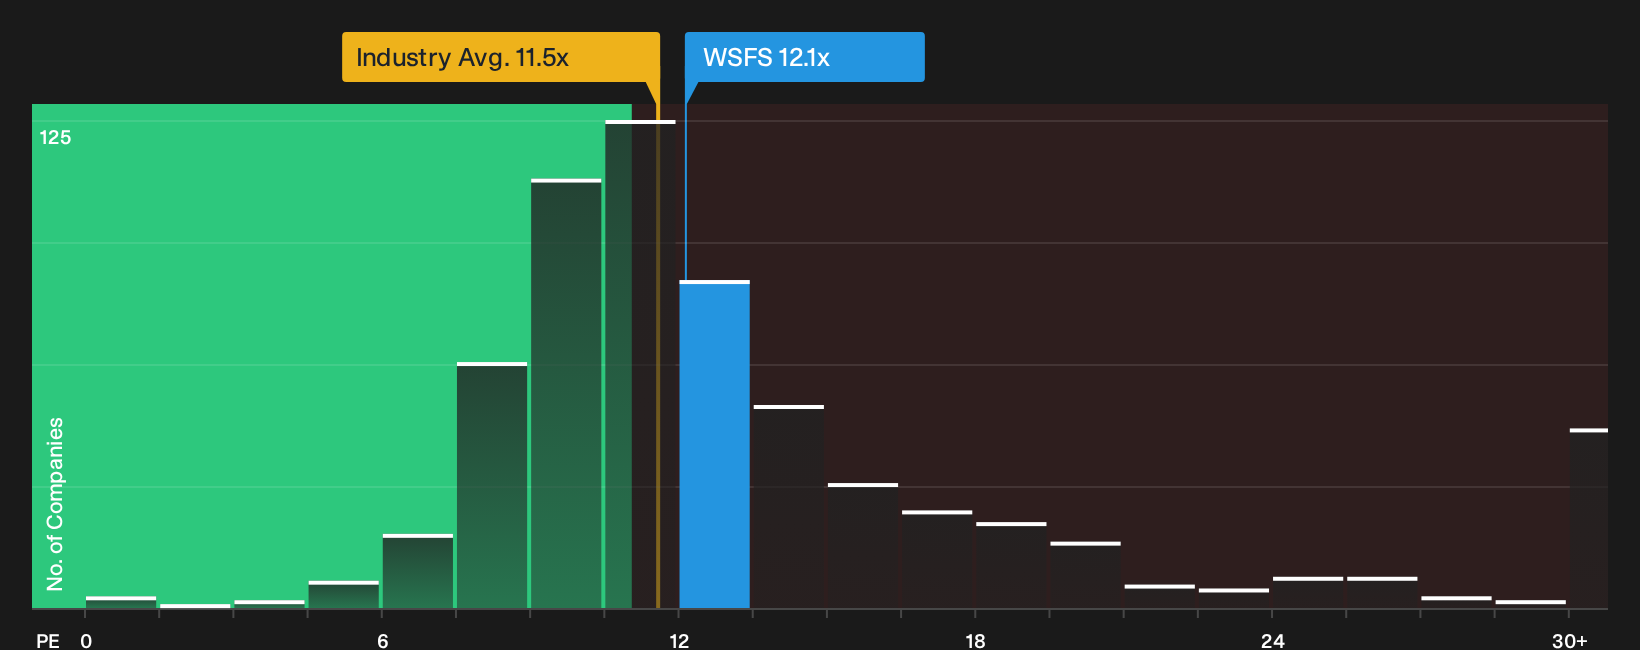
That 14.6% gap to the $88.92 fair value sits uneasily next to how WSFS Financial trades on earnings. The P/E of 12.1x is higher than both the US Banks sector on 11.5x and the internal fair ratio of 10.6x. That richer multiple leans more toward valuation risk than clear upside, so which signal do you trust more right now?
For a closer look at how those earnings multiples stack up, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this WSFS Financial story points in different directions, so move quickly, pull up the numbers yourself, and weigh both the upside and the pressure points captured in 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond WSFS Financial?
If WSFS Financial has you thinking harder about valuation and governance, do not stop here. Broader context from other opportunities can sharpen every decision you make.
- Target potential upside by reviewing a curated 19 high quality undiscovered gems that couples solid fundamentals with businesses many investors may not be watching yet.
- Strengthen your defense by scanning a focused 31 resilient stocks with low risk scores that prioritises resilient balance sheets and lower overall risk scores.
- Lean toward quality by assessing a 8 dividend fortresses that filters for higher yields backed by fundamentals instead of just headline payout numbers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com