


Over the last 7 days, the United States market has risen by 2.2%, contributing to a 14% increase over the past year, with earnings forecasted to grow by 18% annually. In this environment of growth, identifying small-cap stocks that are not only undervalued but also show insider buying can be a promising strategy for investors seeking opportunities in a dynamic market landscape.
Top 10 Undervalued Small Caps With Insider Buying In The United States
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Financial Institutions | 9.5x | 3.2x | 24.33% | ★★★★★☆ |
| Enovis | NA | 0.5x | 44.53% | ★★★★★☆ |
| Union Bankshares | 9.4x | 2.0x | 45.99% | ★★★★☆☆ |
| Bank of the James Financial Group | 10.8x | 2.4x | 27.24% | ★★★★☆☆ |
| Shore Bancshares | 11.4x | 3.3x | 36.20% | ★★★★☆☆ |
| Cardinal Infrastructure Group | NA | 0.9x | 39.31% | ★★★★☆☆ |
| German American Bancorp | 13.0x | 4.9x | 26.53% | ★★★☆☆☆ |
| Bank of Marin Bancorp | NA | 7.3x | 32.28% | ★★★☆☆☆ |
| Five Star Bancorp | 14.8x | 6.3x | 46.60% | ★★★☆☆☆ |
| Orion Group Holdings | 105.2x | 0.4x | 43.36% | ★★★☆☆☆ |
Here's a peek at a few of the choices from the screener.
PROCEPT BioRobotics (PRCT)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: PROCEPT BioRobotics develops and markets surgical and medical equipment, with a market cap of approximately $1.89 billion.
Operations: The company generates revenue primarily from its Surgical & Medical Equipment segment, with recent figures showing $337.34 million. The gross profit margin has shown a notable upward trend, reaching 63.36% in the latest period. Operating expenses are significant, with General & Administrative and R&D being major components at $252.07 million and $78.81 million respectively, contributing to the net loss observed over time.
PE: -9.1x
PROCEPT BioRobotics, a company in the medical device sector, has seen insider confidence with Larry Wood purchasing 23,900 shares for US$498,315. Despite facing legal challenges over alleged sales misrepresentations and experiencing financial losses—US$26.86 million in Q2 2026—the company projects revenue growth between US$390 million to US$410 million for the year. The recent appointment of Dr. Michael Mack to the board may enhance strategic direction amidst these challenges.
- Click here to discover the nuances of PROCEPT BioRobotics with our detailed analytical valuation report.
Understand PROCEPT BioRobotics' track record by examining our Past report.
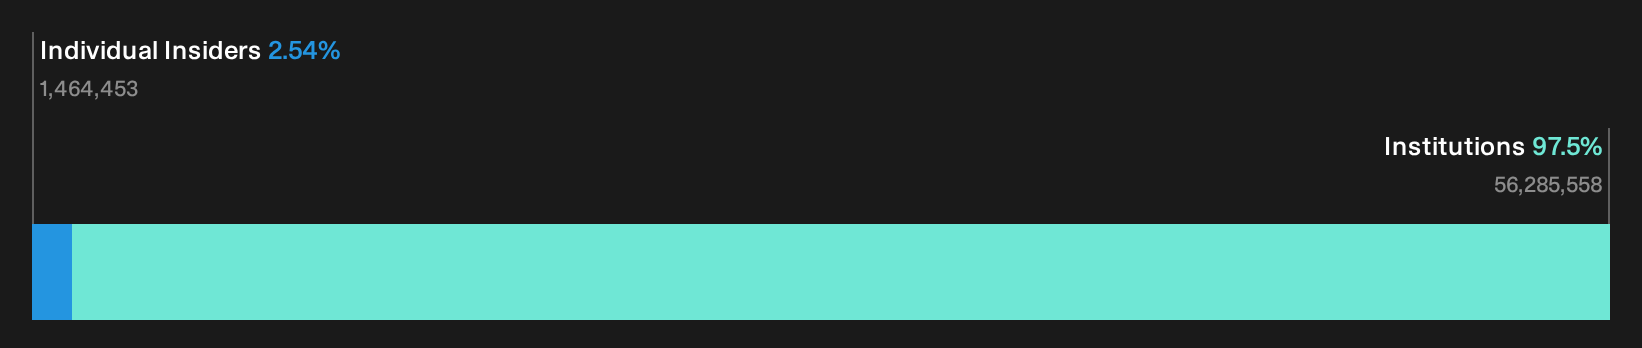
Ameresco (AMRC)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Ameresco is a company that provides energy efficiency and renewable energy solutions across various segments, with operations in Europe, the U.S. Federal sector, Renewable Fuels, and North America Regions, and has a market capitalization of $1.78 billion.
Operations: Ameresco generates revenue primarily from its operations in North America and Europe, with significant contributions from U.S. Federal projects and renewable fuels. The company's cost of goods sold (COGS) is a major expense, impacting its gross profit margins, which have fluctuated between 14.47% and 22.18% over recent periods. Operating expenses include general and administrative costs, which consistently account for a substantial portion of total expenses.
PE: 42.6x
Ameresco is currently drawing attention due to insider confidence, with Brian Cox acquiring 39,700 shares for US$995,279 in August 2026. Despite recent volatility and a decrease in profit margins from 3.3% to 1.4%, the company's strategic partnerships with the U.S. Army for energy projects highlight its role in modernizing critical infrastructure. While earnings forecasts suggest growth at nearly 35% annually, challenges include reliance on external borrowing and insufficient interest coverage from earnings.
- Dive into the specifics of Ameresco here with our thorough valuation report.
Examine Ameresco's past performance report to understand how it has performed in the past.
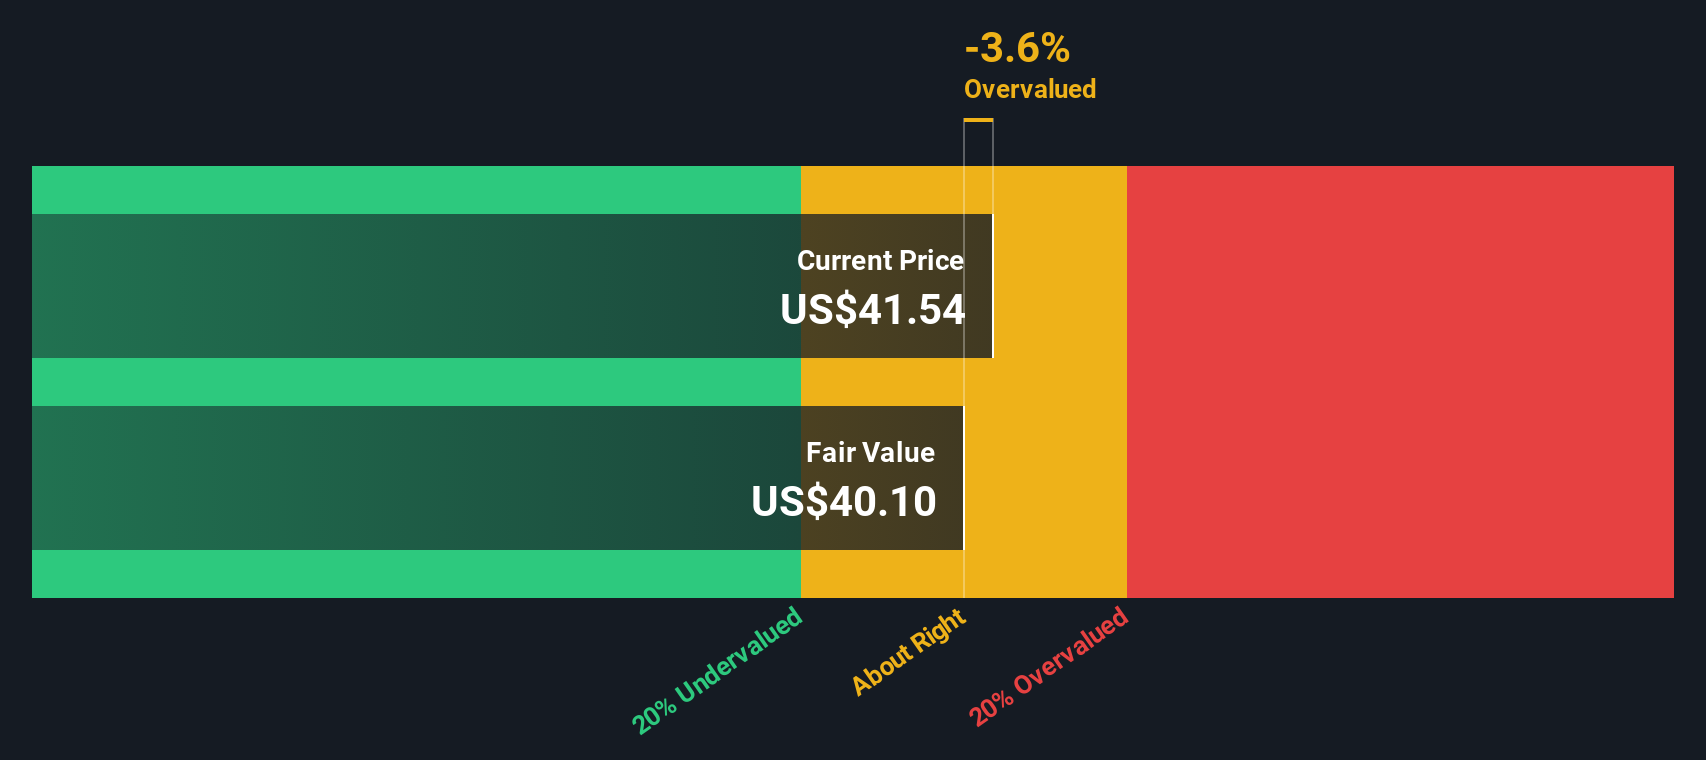
Del Monte (DMC)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Del Monte operates in the food production industry, focusing on bananas, fresh and value-added products, and other related services, with a market capitalization of $1.58 billion.
Operations: Del Monte's revenue streams primarily include Fresh and Value-Added Products, which generated $2.48 billion, and Bananas at $1.44 billion. The company's gross profit margin showed an interesting trend, peaking at 11.50% in December 2016 before experiencing fluctuations over the years, reaching approximately 9.28% by June 2026. Operating expenses have varied but generally remained a significant component of the cost structure across different periods.
PE: 41.2x
Del Monte, a smaller player in the market, is navigating challenging financial waters with its recent strategic moves. Their President & COO, Mohammed Abbas, demonstrated insider confidence by purchasing 12,000 shares in September 2026. Despite a dip in net income to US$21.2 million for Q2 2026 from US$56.8 million the previous year, Del Monte's joint venture with Riverking positions them well in China's expanding fresh-cut fruit market. Additionally, their increased credit facility enhances financial flexibility amidst growing revenue prospects and evolving product lines like fruit-derived extracts for beverages.
- Click here and access our complete valuation analysis report to understand the dynamics of Del Monte.
Explore historical data to track Del Monte's performance over time in our Past section.
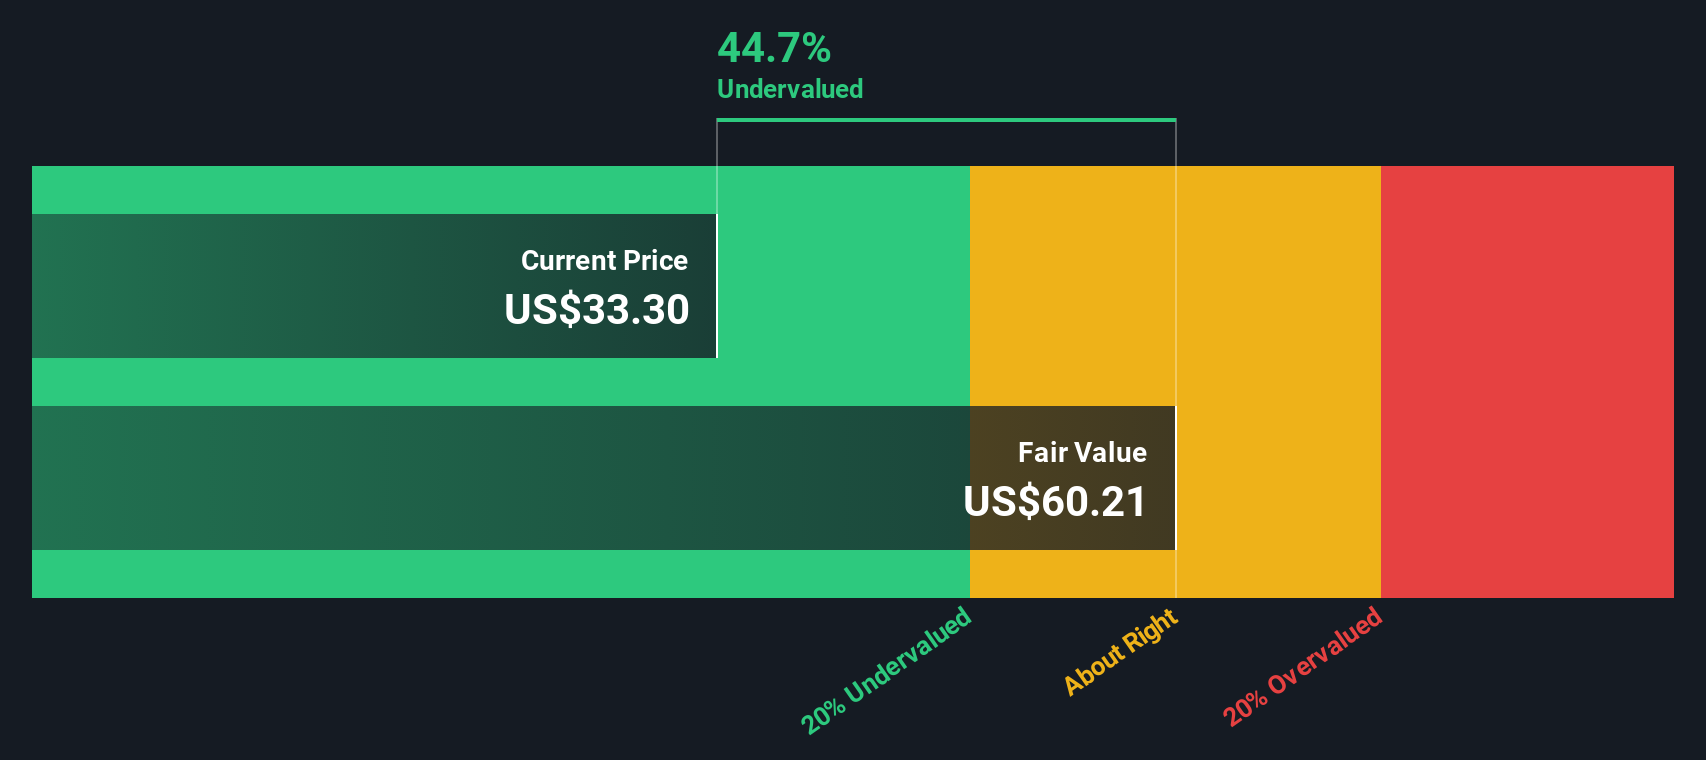
Seize The Opportunity
- Reveal the 64 hidden gems among our Undervalued US Small Caps With Insider Buying screener with a single click here.
- Got skin in the game with these stocks? Elevate how you manage them by using Simply Wall St's portfolio, where intuitive tools await to help optimize your investment outcomes.
- Invest smarter with the free Simply Wall St app providing detailed insights into every stock market around the globe.
Contemplating Other Strategies?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com