


Century Communities (CCS) just rewired its financing, amending a major credit facility to lift total commitments to US$1.2b and push certain maturities to 2030, while simultaneously rolling out new housing projects across several regions.
Despite the new communities and the revamped US$1.2b credit line, Century Communities’ recent trading has been subdued, with a 30-day share price return down 8.71% and a 90-day share price return down 7.43%.
Short-term momentum has cooled. However, the 1-year total shareholder return of 3.35% and 5-year total shareholder return of 3.85% indicate a more muted but still positive overall journey as investors weigh expansion plans against perceived housing cycle risk.
Scan other homebuilders that show similar expansion and financing storylines by reviewing our hand picked list of solid balance sheet and fundamentals (25 results) alongside Century Communities.
The recent pullback at Century Communities now forces a simple test. Are investors reassessing the business after fresh expansion and a larger credit line, or has sentiment simply shifted more quickly than the fundamentals have changed?
Most Popular Narrative: 24.5% Undervalued
On the latest numbers, Century Communities closed at $58.89 while the most followed narrative pins fair value at $78 per share. That frames the recent pullback as a valuation gap rather than a new verdict on the underlying business.
Century Communities has assembled more than 60,000 owned and controlled lots and a record 330 open communities, which management believes can support multi year delivery growth once demand improves and could lift homebuilding revenue if volumes rise against a largely fixed overhead base.
See why 4 investors see Century Communities as 24% undervalued.
Result: Fair Value of $78 (UNDERVALUED)
Still, the narrative around Century Communities can break if heavy buyer incentives keep squeezing margins or if its BB minus credit rating lifts borrowing costs and crimps future projects.
Find out about the key risks to this Century Communities narrative.
Another View on Century Communities’ Valuation
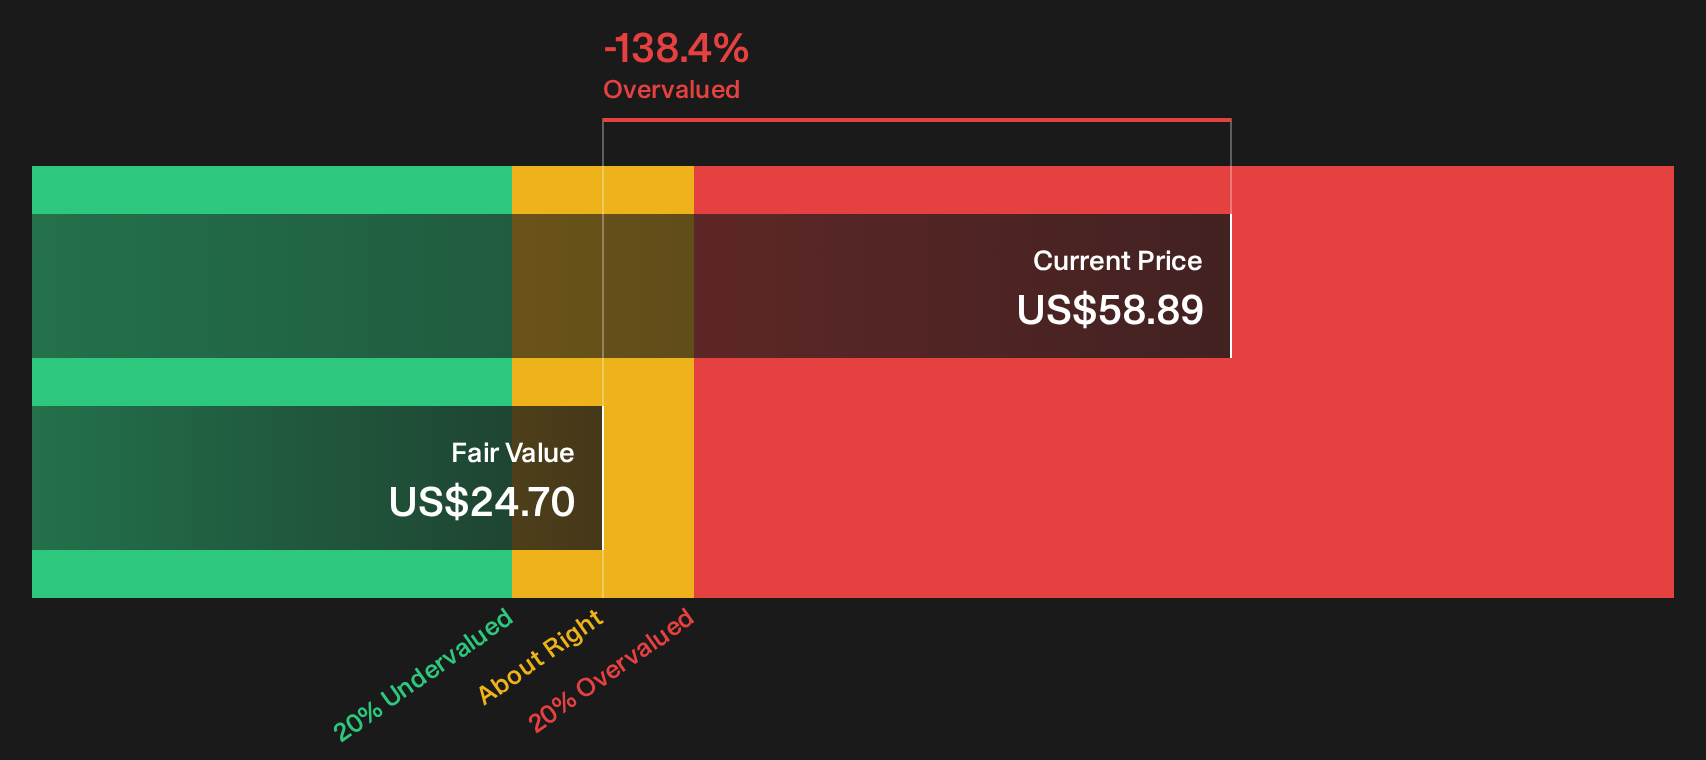
Analysts see Century Communities as undervalued on a fair value per share of $78, yet the SWS DCF model tells a very different story. On that approach, the current price of $58.89 sits well above an estimated future cash flow value of $24.70, which frames the stock as expensive. Which lens do you think better fits your expectations for cash generation?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Century Communities for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Century Communities can create paralysis, yet prices move while investors hesitate. Step back from the noise, review the numbers, and weigh the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Century Communities?
If the story around Century Communities has your attention, do not stop here. Broader opportunities sit just a few clicks away in the wider market.
- Target quality bargains by scanning our hand picked list of 27 high quality undervalued stocks that pair strong fundamentals with compressed valuation multiples.
- Strengthen portfolio resilience by reviewing a curated 31 resilient stocks with low risk scores that score well on financial stability and downside protection.
- Get ahead of the crowd by checking a focused 19 high quality undiscovered gems that combines smaller coverage with solid financial underpinnings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com