


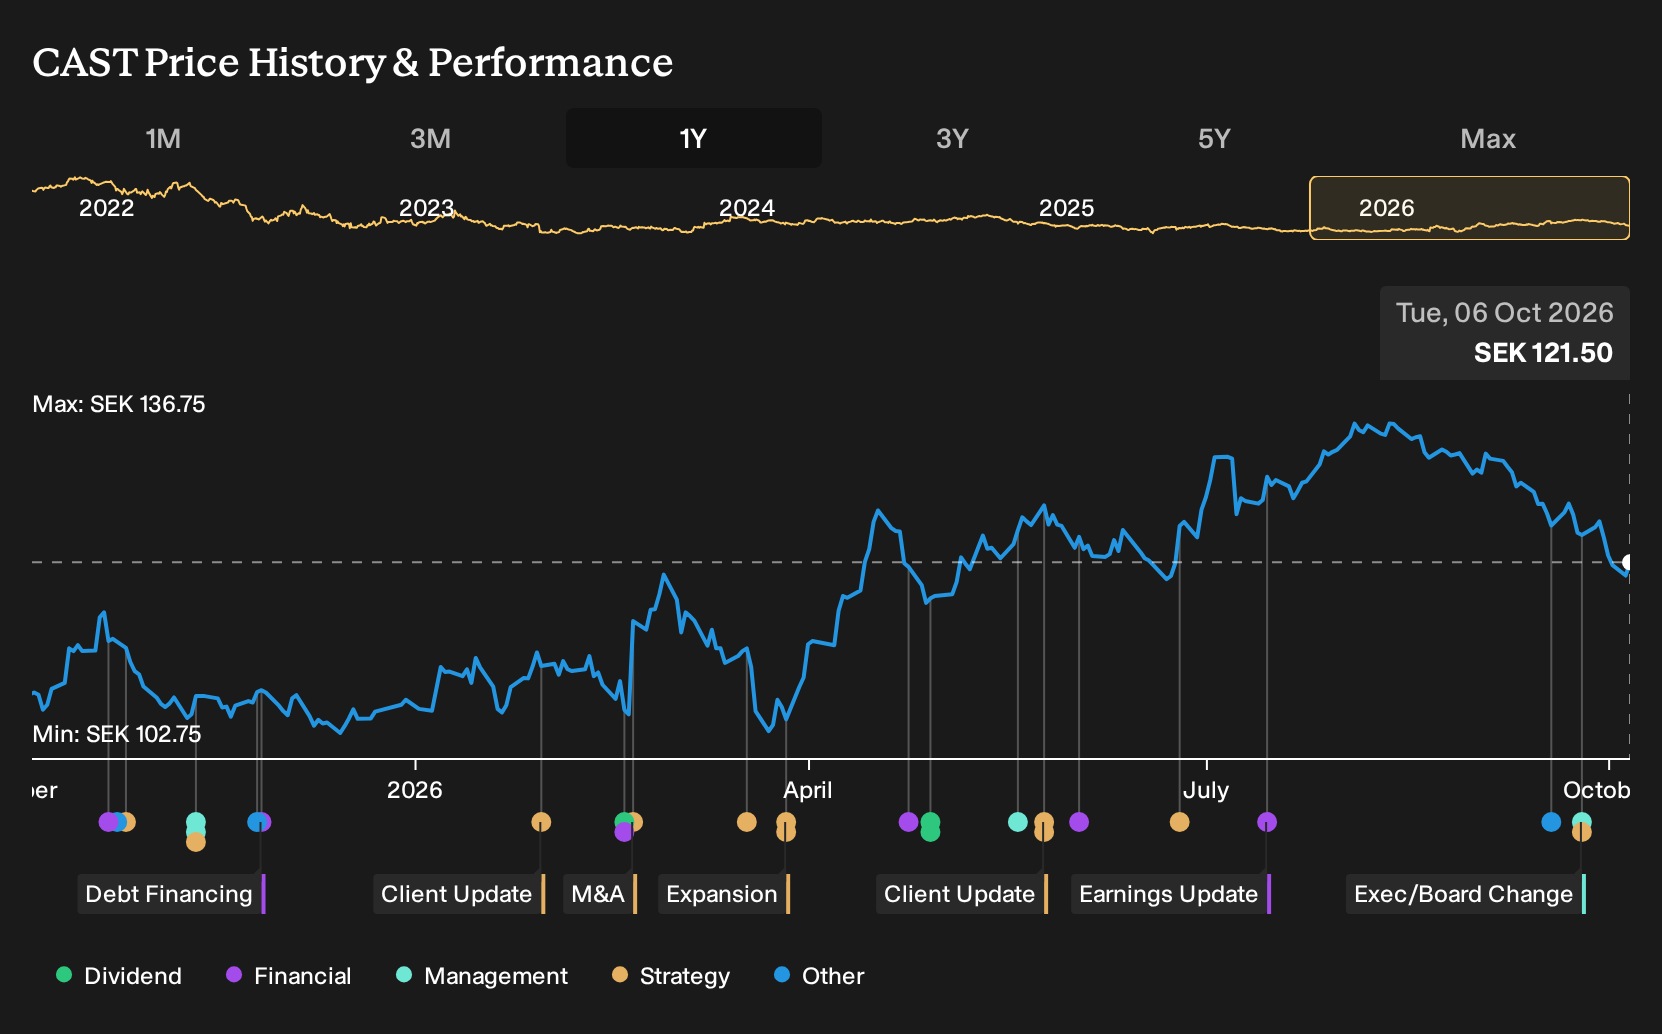
- Castellum has overhauled its structure by moving from four regions to two. Örjan Rystedt has been appointed to lead Region Göta and Per Gawelin to head Region Svea, while several senior executives exit following portfolio sales and the reorganization.
- The planned 15% cut in administrative costs, equal to about SEK 100 million, signals a sharper focus on lean operations and faster decision making across Castellum's Swedish and Danish footprint.
- We will look at how Castellum's investment narrative is affected by the plan to cut administrative costs by about SEK 100 million.
Scan how Castellum's reorganization compares with other property players tightening costs by reviewing our hand picked list of solid balance sheet and fundamentals (206 results).
Castellum Investment Narrative Recap
To own Castellum, you need to believe that a large Nordic commercial landlord can keep its properties working hard while trimming overheads and refocusing its footprint. The move to two regions and a 15% cut in administrative costs points to a leaner structure that could support earnings quality if service levels and leasing activity hold up.
The key short term swing factor remains rental income and occupancy in markets such as Stockholm, Gothenburg and Copenhagen, especially after earlier value write downs and higher vacancies. Execution risk is still tied to development projects without pre signed leases and to debt being less comfortably covered by operating cash flow.
The reorganization sits alongside Castellum’s project pipeline in places such as Hagastaden in Stockholm, where Infinity is intended to tap office demand without pre signed tenants. Cost savings and a simpler hierarchy could make it easier to manage that kind of development risk, since decisions around leasing terms, capex and timing can be taken closer to the assets.
On the flip side, a slimmer head office and regional leadership change place more weight on local execution and risk control. For you, the link between this reworked organizational structure, project delivery, leverage discipline and income from property management is what really needs watching.
Castellum Forecasts, Assumptions And Reorganization Link
Analyst models around Castellum give you a rough map of what the reorganized group would need to deliver for current valuations to make sense. Those projections sit in the background while management cuts administrative costs and reshapes the portfolio, but the numbers still frame how much execution room there is if leasing or asset sales move off script.
Consensus expectations assume revenue will decrease by 7.8% a year over the next three years, even as profit margins are expected to rise from 26.9% today to 58.9% in three years. That combination implies a slimmer, more profitable property base where cost discipline and mix matter more than brute size. It also puts more pressure on the reorganization to keep service quality and occupancy steady while the top line trends lower.
Earnings today are put at SEK 2.7b, with analysts projecting SEK 4.6b by 2029 and some forecasts spread widely either side of that. The step up of SEK 1.9b between those two points is material, so the success or delay of projects like Infinity, as well as the handling of Entra exposure and vacancy, carry extra weight for anyone leaning on these consensus numbers.
Those forecasts feed directly into valuation expectations. To line up with the analyst view, Castellum would need to be earning SEK 4.6b on SEK 7.8b of revenue in 2029 and trade on a P/E of 14.1x, compared with 21.4x today and a cited 10.9x for the wider GB real estate peer group. If you think the new two region structure and SEK 100m in annual administrative savings can support that earnings profile while revenues shrink, the gap between the current share price and the SEK 138.09 target starts to look more understandable.
Castellum's narrative projects SEK 7.8b revenue and SEK 4.6b earnings by 2029. This requires revenue to decrease 7.8% per year and an earnings increase of SEK 1.9b from SEK 2.7b today.
Uncover why Castellum's fair value indicates a 14% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate take on Castellum puts vacancy pressure at the centre of the story. The most bearish analysts were pencilling in revenue of about SEK 6.9b and earnings of SEK 3.2b by 2029, with margins rising more slowly than consensus. That view looks more cautious, and this new two region reorganization could push those forecasts to shift again. Readers are encouraged to weigh both narratives and consider how much risk around occupancy fits their own comfort level.
Explore 3 other Castellum fair value estimates, including one that suggests as much as 56% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Castellum research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Castellum. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Castellum's overall financial health at a glance.
Looking For More Investment Ideas Beyond Castellum?
If Castellum has sharpened your focus on balance sheets, income streams and risk, it can be useful to line it up against other companies facing different pressures. A targeted screener helps you quickly surface stocks that match the type of financial profile you want to research next.
- For investors who like to back underappreciated quality, review a curated 615 high quality undiscovered gems that pair solid fundamentals with less crowded ownership.
- If resilience and capital protection sit at the top of your checklist, scan a 228 resilient stocks with low risk scores that filters for sturdier balance sheets and lower risk scores.
- Income focused readers can compare Castellum's profile with a 169 dividend fortresses that concentrate on companies offering 5%+ yields with a focus on payout strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com