


P/F Bakkafrost (OB:BAKKA) has released third quarter 2026 production figures, reporting harvest volumes of 23,100 tons in the Faroe Islands and 4,500 tons in Scotland, giving investors fresh data on operational output.
P/F Bakkafrost shares trade at NOK436.8, with a 1 day share price return of 1.20% after the production update. The 90 day share price return of 6.17% contrasts with a year to date share price decline of 15.59% and a 1 year total shareholder return decline of 5.96%, signalling recovering momentum after a weaker stretch.
Scan how P/F Bakkafrost compares to other salmon and protein producers by reviewing a curated list of solid balance sheet and fundamentals (206 results) that could handle similar production swings.
P/F Bakkafrost shares have bounced from a weaker year, yet the recent production update and price move still leave a bigger question. Has most of the rebound played out already, or does valuation point to further upside ahead?
Most Popular Narrative: 9% Undervalued
Analysts following P/F Bakkafrost anchor their view on a fair value of NOK482, which sits above the latest NOK436.8 close and frames the production update against a still supportive valuation gap.
The analysts have a consensus price target of NOK482.23 for P/F Bakkafrost based on their expectations of its future earnings growth, profit margins and other risk factors. In order for you to agree with the analysts, you would need to believe that by 2029, revenues will be DKK11.1 billion, earnings will come to DKK1.9 billion, and it would be trading on a PE ratio of 12.6x, assuming you use a discount rate of 6.8%.
See why 4 investors see P/F Bakkafrost as 9% undervalued.
Result: Fair Value of NOK482 (UNDERVALUED)
Still, the P/F Bakkafrost story can break if Scottish biological issues persist, or if weaker salmon prices keep squeezing cash flow and margins.
Find out about the key risks to this P/F Bakkafrost narrative.
Another View on P/F Bakkafrost Valuation
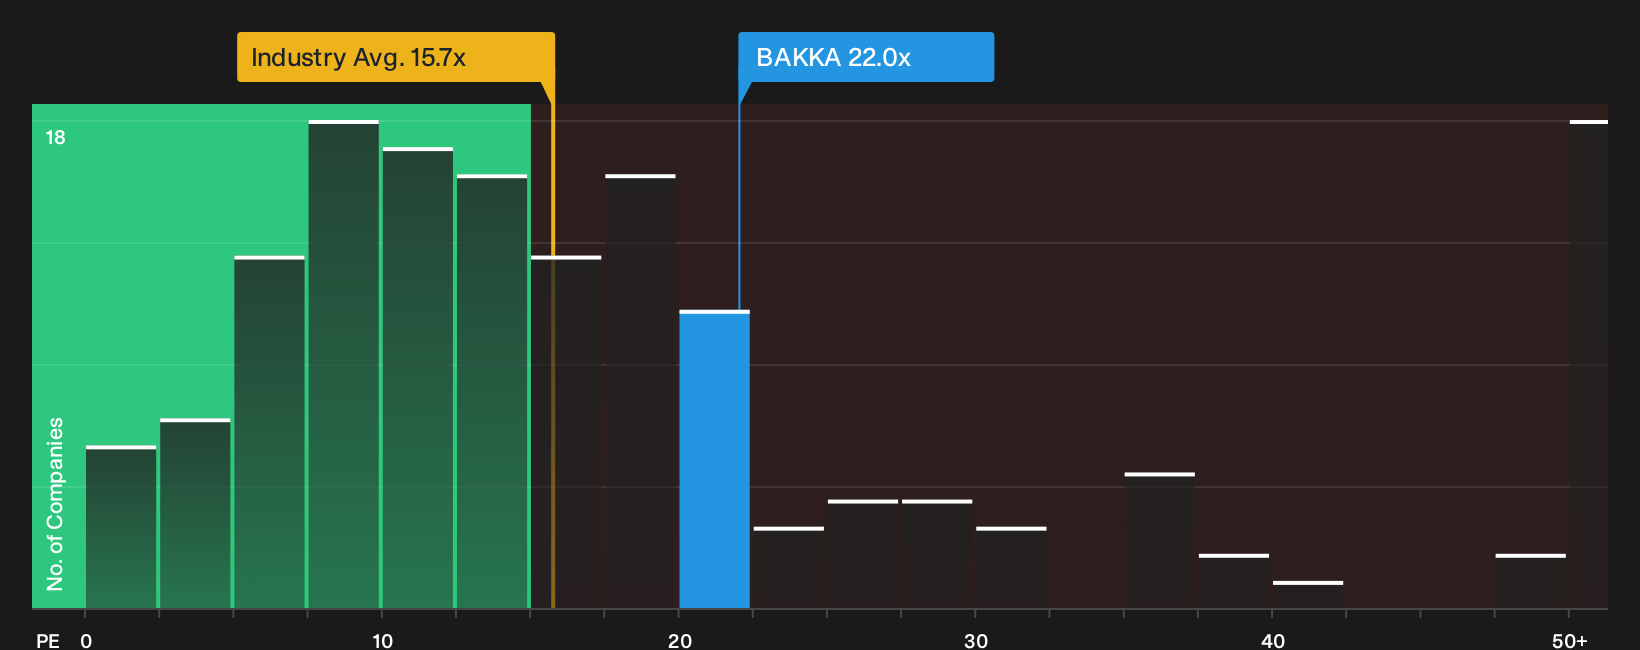
That 9% gap to the NOK482 analyst target tells only one story for P/F Bakkafrost. On P/E, the stock trades at 22x earnings, richer than the European Food sector on 15.7x and slightly above its own fair ratio of 21.4x, which tilts the risk toward overpaying if expectations cool.
For a fuller sense of how this earnings multiple stacks up against peers and the fair ratio the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around P/F Bakkafrost is mixed. Use that as a starting point, move quickly through the numbers, then weigh up the 3 key rewards
Looking for more investment ideas beyond P/F Bakkafrost?
If P/F Bakkafrost has you thinking harder about valuation and risk, broaden your toolkit with other ideas that could sharpen your next move.
- Spot potential mispricing early and review a focused set of 179 high quality undervalued stocks that pair quality fundamentals with more modest expectations.
- Lock in income potential and scan a curated pool of 169 dividend fortresses that aim to keep cash coming in while you hold.
- Sleep easier during rough patches and filter for 228 resilient stocks with low risk scores that score stronger on balance sheet resilience and volatility control.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com