


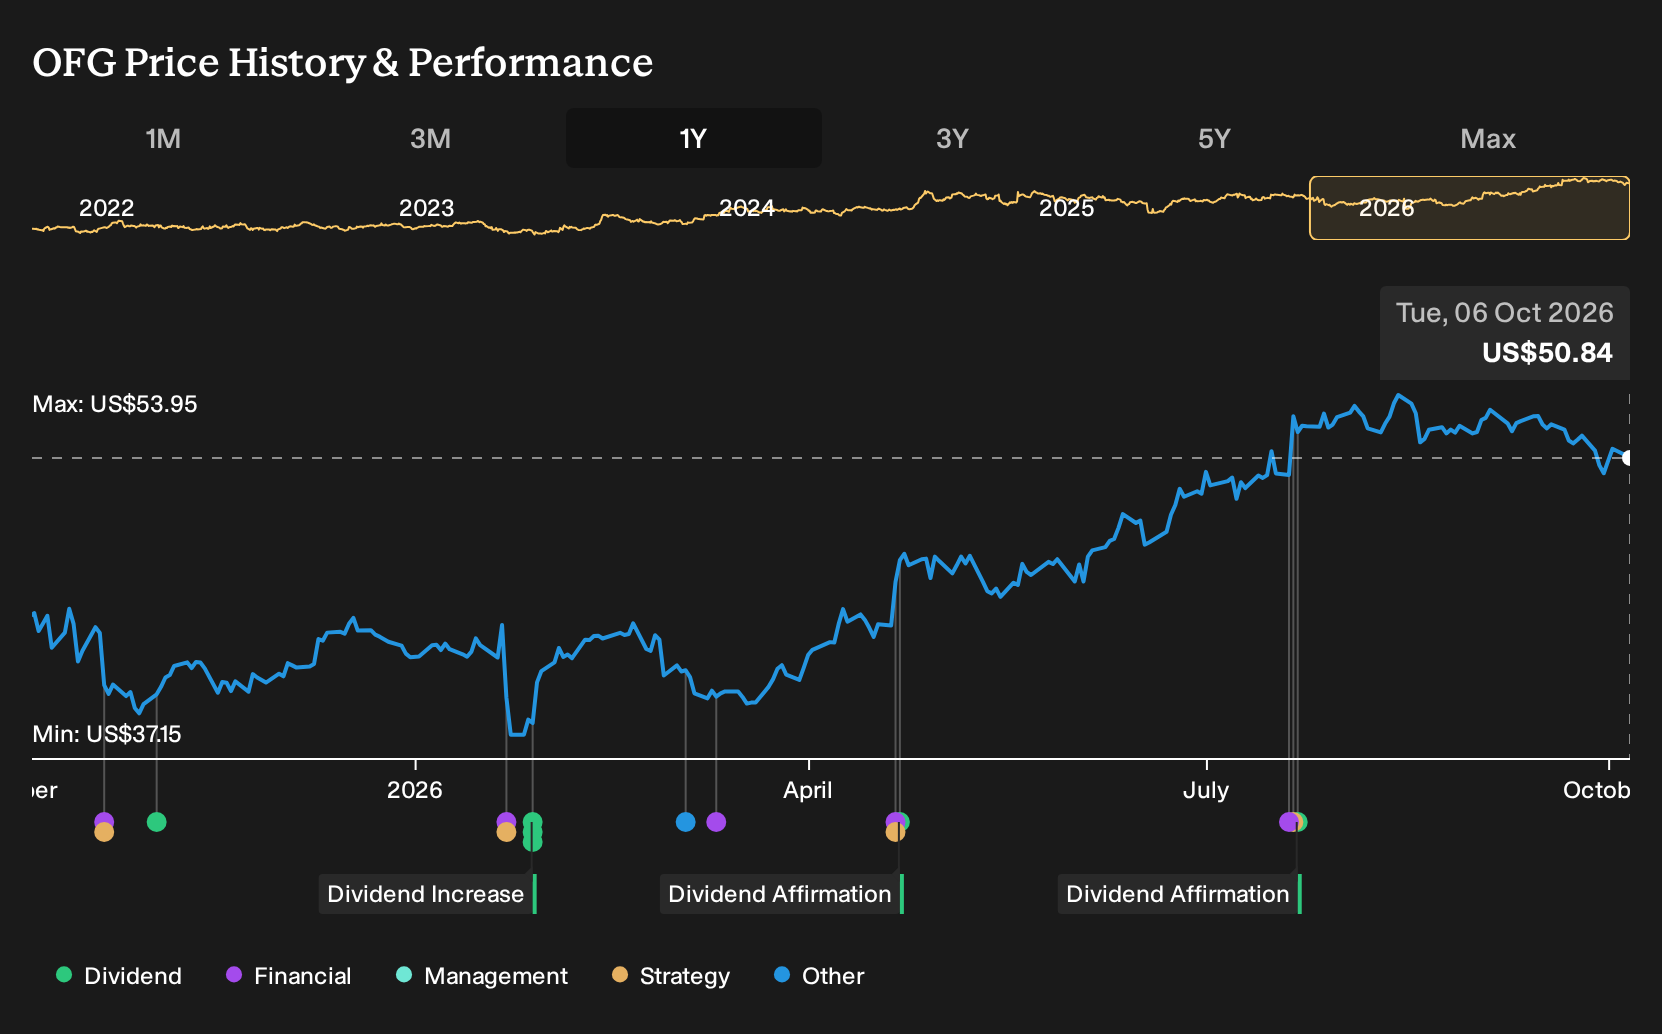
- OFG Bancorp recently reported a quarterly dividend of $0.35 per share, implying a 2.73% yield and an annualized payout that is 16.7% higher than last year, with a five-year average annual dividend increase of 36.7% and a yield above the Banks - Northeast industry level of 2.17%.
- The combination of a higher dividend yield and earnings per share projected at $5.06 for 2026, implying 10.48% year-over-year growth, highlights how OFG Bancorp is leaning on both shareholder returns and profit expansion to support its income-focused appeal.
- We will look at how OFG Bancorp’s investment narrative is affected by this faster dividend growth, given already detailed earnings projections.
OFG Bancorp Investment Narrative Recap
For OFG Bancorp, the core belief for a shareholder is that a focused Puerto Rico and U.S. banking franchise can keep growing loans, defending deposit funding and steadily improving efficiency through its digital first approach. The richer dividend profile fits that story, but does not radically change it. The key near term swing factor remains how well management holds net interest margins while competition lifts funding costs.
The biggest current risk is concentration. A setback in Puerto Rico’s economy, further power grid issues or funding pressure from government and commercial deposit outflows could hit credit quality and liquidity at the same time. The higher dividend slightly tightens flexibility if earnings soften, although current profitability and past revenue progress help offset that concern for now.
The most relevant announcement is the dividend increase to US$0.35 per share, which lifts the indicated yield to 2.73% and puts OFG Bancorp ahead of the Banks, Northeast peer group on income. That reflects management’s view of the strength of current cash generation and links directly to the income angle that many investors care about.
This payout move sits alongside a business for which analysts currently forecast 7.1% annual revenue growth and a modest decline in earnings over the next three years. The key question for investors is whether current profitability, digital efficiency gains and solid net interest income can offset those earnings expectations and the identified risks around funding concentration, competition and Puerto Rico specific shocks, while still supporting this richer dividend level.
OFG Bancorp's narrative projects US$808.2 million in revenue and US$191.2 million in earnings by 2029. This assumes 7.5% yearly revenue growth and an earnings decline of about US$29.2 million from the current US$220.4 million level.
Uncover why OFG Bancorp's fair value signals an 8% potential upside to its current price before that discount gap draws in more attention.
Exploring Other Perspectives
Only two fair value estimates from the Simply Wall St Community currently bracket OFG Bancorp between US$55 and about US$116, a very wide span for such a small sample. You are seeing investors split between much lower and much higher outcomes, while the dividend reset and Puerto Rico specific risks keep the future path open to debate.
Explore another OFG Bancorp fair value estimate, including one that suggests potential upside of as much as 129% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your OFG Bancorp research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for OFG Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate OFG Bancorp's overall financial health at a glance.
Looking For More Ideas Beyond OFG Bancorp?
If the OFG Bancorp story has you thinking about how income, value and balance sheet strength fit together, the next step is to widen the search and see how other businesses stack up on the same themes using the Simply Wall St Screener.
- For investors who care most about getting paid while they wait, compare OFG Bancorp's payout profile with a curated set of high yield opportunities through the 8 dividend fortresses.
- If capital preservation and steadier risk levels matter more to you than chasing maximum upside, filter for companies that score well on stability using the 31 resilient stocks with low risk scores.
- When you want quality that is not already crowded, focus on underfollowed businesses with strong fundamentals and use the 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com