


Teledyne Technologies: Defense Software And Space Sensors In Focus
Teledyne Technologies (TDY) has landed fresh attention after Teledyne Imaging Sensors supplied over 1.3 billion infrared detector pixels for U.S. Space Force programs and Teledyne FLIR OEM launched its Prism A-ISR airborne ISR software module.
Recent headlines around Teledyne Technologies’ space sensors and Prism A-ISR launch have arrived while momentum has been steady rather than euphoric, with a year to date share price return of 19.94% and a 3 year total shareholder return of 51.38%, which suggests that longer term holders have seen stronger gains than those focused on the latest move.
Scan other defense and aerospace plays riding similar AI and sensor themes by reviewing our curated list of 91 AI infrastructure stocks, which is tied to real-world programs like Teledyne Technologies’ latest wins.
Teledyne Technologies looks like a serious defense and imaging powerhouse, but after a near 20% gain this year and healthy multi year returns, are investors now paying too much for that quality or still getting a fair deal?
Most Popular Narrative: 18% Undervalued
Teledyne Technologies closed at $622.22, while the most followed narrative pegs fair value around $758.08. This frames the latest defense and imaging wins against a longer multi year backlog story and capital allocation plan.
The current numbers, including upgraded 2026 guidance and management’s view that the stock has at times been unfairly sold off, suggest a share price that may not fully reflect the company’s record backlog, expanding defense and healthcare exposure, and balance sheet capacity for further mergers and acquisitions and share repurchases.
See why 13 investors see Teledyne Technologies as 18% undervalued.
Result: Fair Value of $758.08 (UNDERVALUED)
Still, Teledyne Technologies relies heavily on the smooth integration of deals like Varex Imaging and on supply chains that could tighten, both of which could challenge the current upside narrative.
Find out about the key risks to this Teledyne Technologies narrative.
Another View: SWS DCF Flags Less Upside
While the analyst narrative frames Teledyne Technologies as about 18% undervalued at a fair value of $758.08, the Simply Wall St DCF model tells a cooler story. On that math, TDY at $622.22 sits above an intrinsic value of $586.52, which points to mild overvaluation instead. Which lens do you find more convincing when real cash flows are the anchor?
Look into how the SWS DCF model arrives at its fair value.
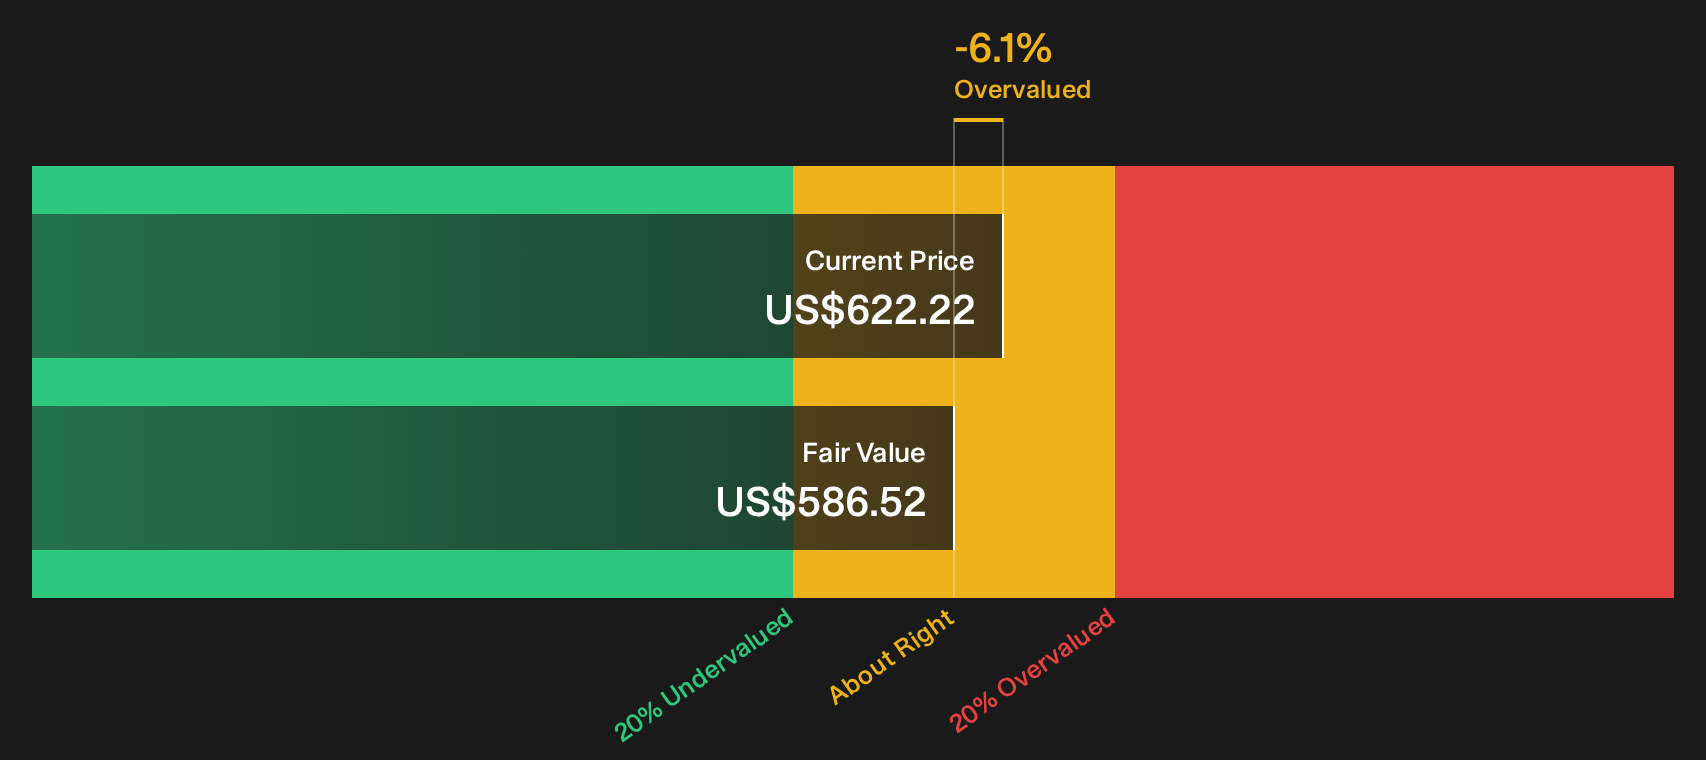
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Teledyne Technologies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Teledyne Technologies can create noise. Move quickly, review the full data set, and weigh both sides of the story with 4 key rewards and 1 important warning sign.
Hunting For More Ideas Beyond Teledyne Technologies?
If Teledyne Technologies has you thinking bigger about your portfolio, broaden the search and let data rich stock screens surface ideas you might otherwise miss.
- Target resilient balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (25 results) that filters for financial strength before hype.
- Spot potential mispricings early by reviewing a focused set of 27 high quality undervalued stocks that pair quality metrics with compressed valuations.
- Unearth less crowded opportunities by checking a tailored pool of 19 high quality undiscovered gems where strong business foundations have yet to draw broad attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com