


ACS Actividades de Construcción y Servicios (BME:ACS) is seeing its project pipeline swell as global demand for data centers and high tech infrastructure accelerates, drawing investor attention to its revenue outlook and funding pressures.
ACS Actividades de Construcción y Servicios has seen strong momentum over the past few years, with a 1 year total shareholder return of 38.76% and a 5 year total shareholder return of 428.01%. However, the 90 day share price return is down 18.79% and near term volatility has picked up around its €96.15 share price as investors weigh the expanding project pipeline against funding costs.
Scan the digital infrastructure theme beyond ACS Actividades de Construcción y Servicios by reviewing our curated list of 91 AI infrastructure stocks that could benefit from similar project momentum.
ACS Actividades de Construcción y Servicios now trades well below the average analyst target, yet above some intrinsic value estimates. After that sharp pullback, where does a reasonable fair value range actually sit?
Most Popular Narrative: 29% Undervalued
On the most followed view, ACS Actividades de Construcción y Servicios screens as undervalued, with a fair value of about €134.71 against the recent €96.15 close. This raises a clear question about whether the current selloff aligns with its long term project and earnings profile.
The surge in global demand for digital infrastructure including data centers, AI, and advanced technology facilities is resulting in robust order growth and a significant pipeline of large projects for ACS, especially in North America and Europe, positioning the company for strong top-line revenue expansion.
ACS is seeing high momentum in sectors driven by demographic and societal changes, such as healthcare, biopharma, and social infrastructure, with expectations of further growth tied to population increases and urbanization, supporting future revenue streams and order backlog growth.
See why 19 investors see ACS Actividades de Construcción y Servicios as 29% undervalued.
Result: Fair Value of €134.71 (UNDERVALUED)
Still, ACS Actividades de Construcción y Servicios is leaning into capital intensive data centers and highly leveraged concessions, so weaker demand or tighter funding could quickly pressure earnings.
Find out about the key risks to this ACS Actividades de Construcción y Servicios narrative.
Another View: ACS Actividades de Construcción y Servicios Through Cash Flows
There is a different lens on ACS Actividades de Construcción y Servicios. Our DCF model points to a future cash flow value of about €83.51 per share, which sits below the current €96.15 price and implies the stock screens as overvalued on this approach.
That gap reflects a simple question for you as an investor. Are the analyst growth and margin assumptions generous enough to justify paying well above what the SWS DCF model suggests is reasonable today, or does the cash flow view deserve more weight in your process?
Look into how the SWS DCF model arrives at its fair value.
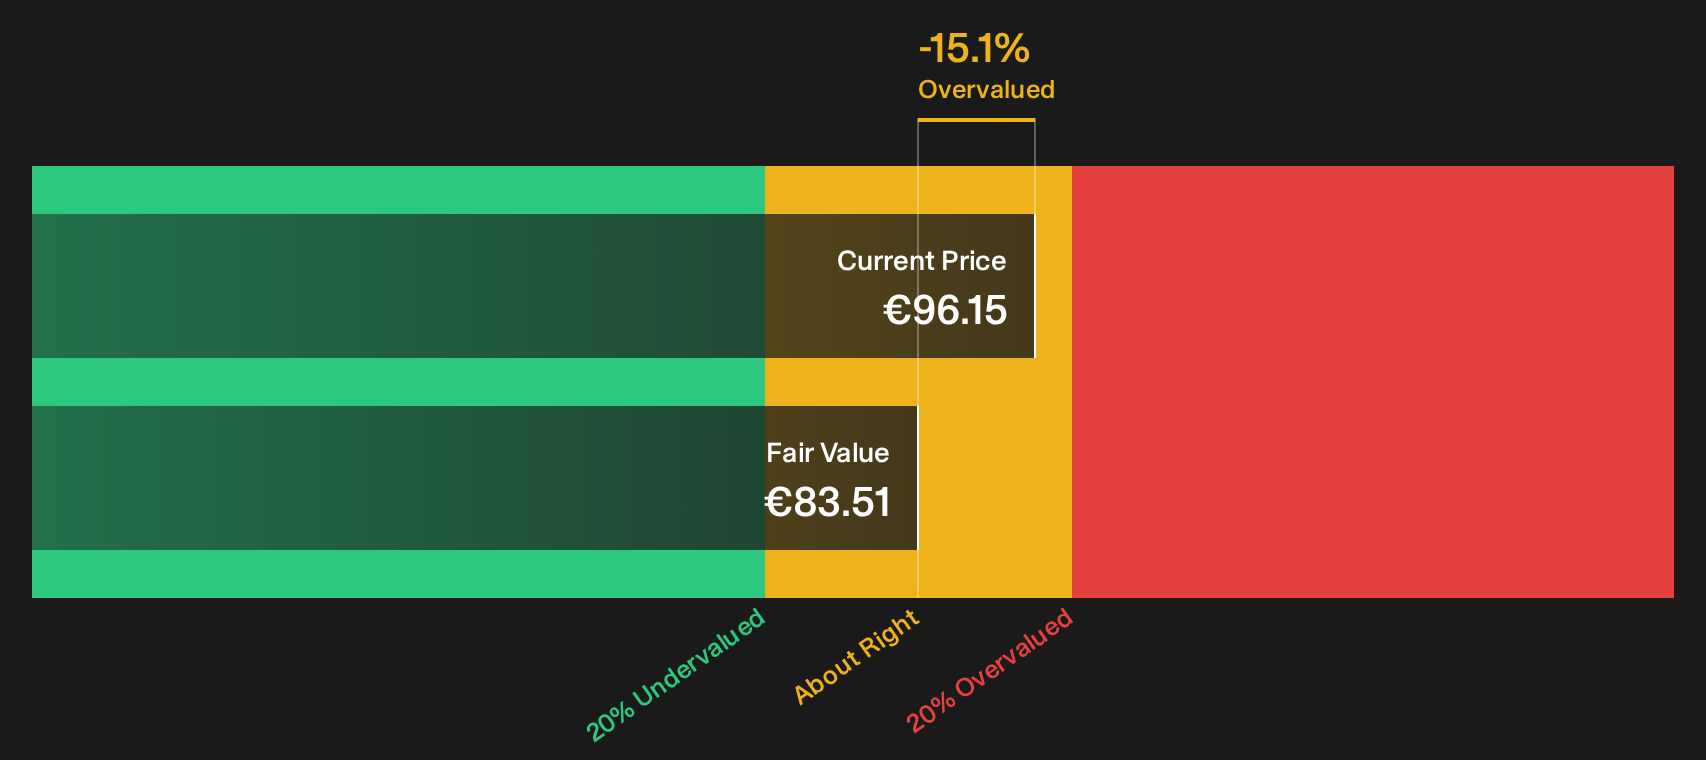
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ACS Actividades de Construcción y Servicios for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 179 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals like these often split opinion. Move quickly, review the full data set, and weigh the 3 key rewards and 2 important warning signs for yourself.
Looking for more ACS Actividades de Construcción y Servicios style ideas?
If you rely only on ACS Actividades de Construcción y Servicios, you could miss other compelling setups, so put the Simply Wall Street Screener to work as your idea engine.
- Target long term compounding by scanning a curated 179 high quality undervalued stocks list that combines quality fundamentals with prices that may not fully reflect their underlying strength.
- Prioritise resilience and sleep better at night by focusing on a list of solid balance sheet and fundamentals (206 results) group where debt burdens and refinancing risk are kept in tighter check.
- Get ahead of the crowd by filtering for 617 high quality undiscovered gems that pair robust financials with relatively limited market attention today.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com