


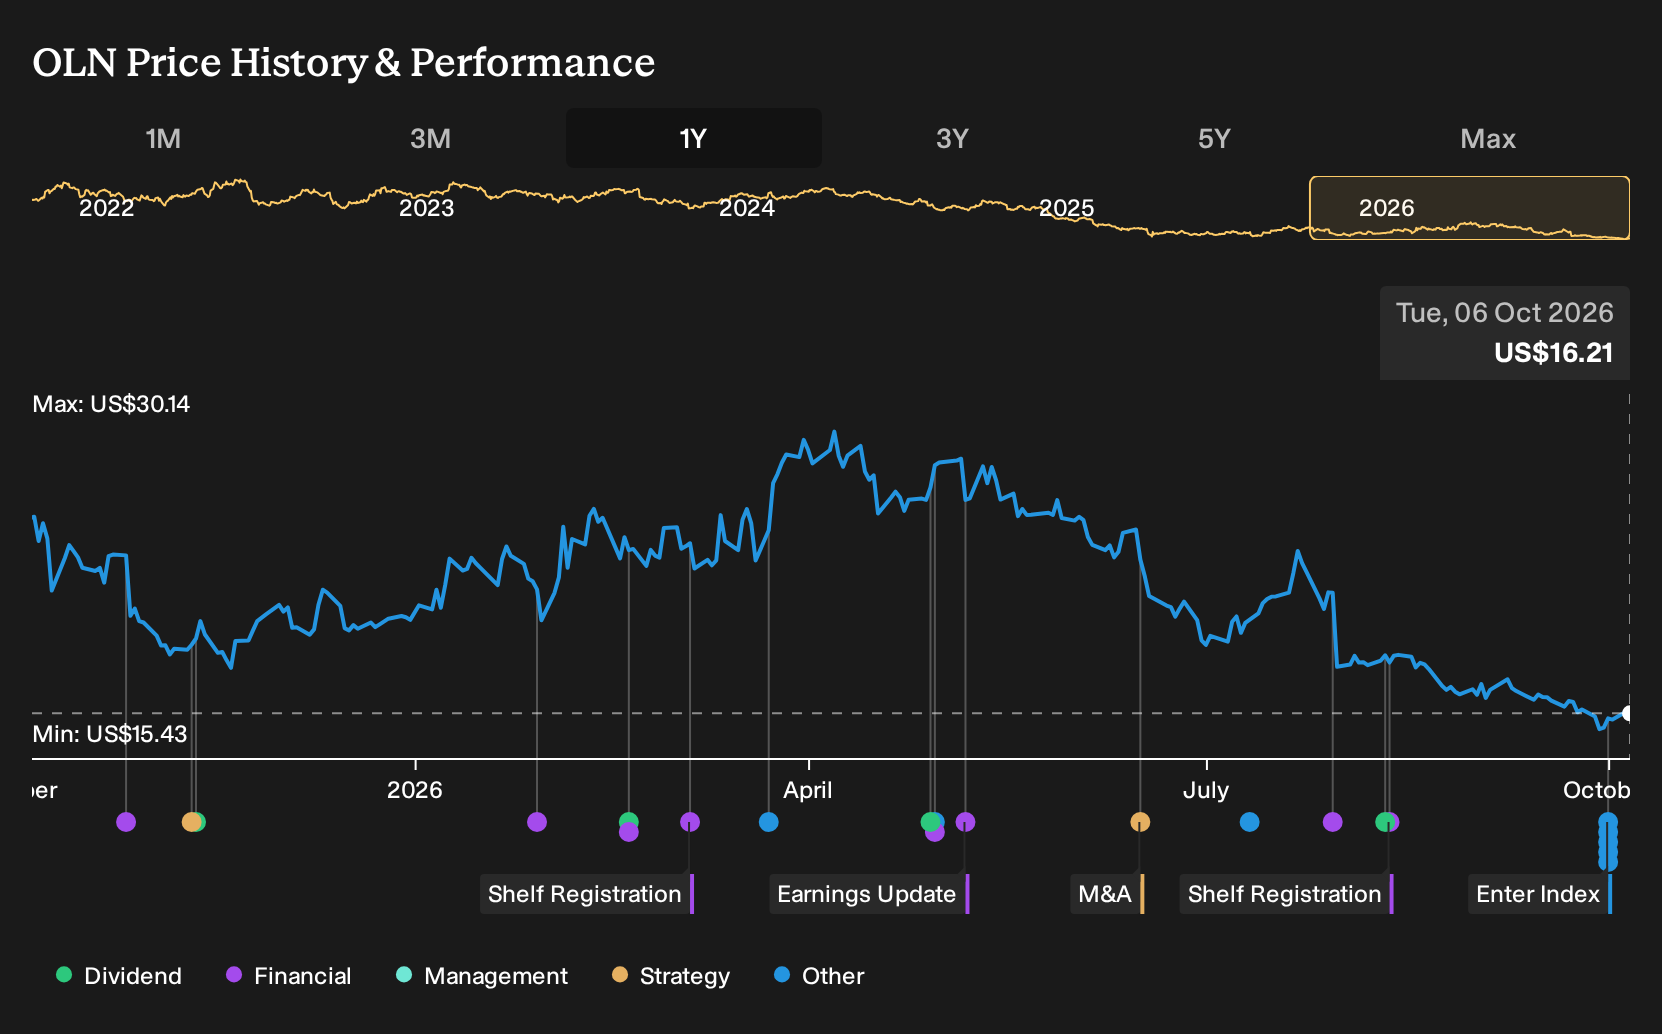
- Olin Corporation was removed from the S&P 400 and its Materials sector index and added to the S&P 600 and S&P 600 Materials and Commodity Chemicals indices on 1 October 2026, shifting it into a smaller company benchmark group.
- The move into the S&P 600 reshapes which index funds and benchmarked portfolios may hold Olin Corporation, potentially altering trading liquidity, investor mix, and how the chemicals business is compared with smaller peers.
- Next, the focus shifts to how Olin Corporation's move from the S&P 400 to the S&P 600 could reshape its investment narrative.
Olin Investment Narrative Recap
For you to own Olin, you need to be comfortable with a chemicals and ammunition group that is currently loss making but focused on cost cuts and mix improvement. The key near term swing factor is whether chlor alkali, vinyls and epoxy pricing and volumes can support those efficiency efforts enough to lift margins from current pressure points.
The biggest operational risk is that global overcapacity in ethylene dichloride and weak construction and housing activity keep margins under strain, while Winchester ammunition stays under earnings pressure. The shift from the S&P 400 to the S&P 600 mostly affects which funds hold Olin and does not meaningfully change these core business drivers.
The move into the S&P 600 and its Materials and Commodity Chemicals indices is the clearest recent announcement tied to this story. That change mainly affects index ownership, liquidity patterns and which peer group investors use when they compare Olin against other listed chemical producers.
For catalysts, the index switch could matter at the margin if smaller cap focused funds increase or reduce exposure. This may influence short term trading in Olin stock around existing operational news. The more important test remains execution on cost reduction in chlor alkali and epoxy, and the ability to protect cash generation while the Winchester segment manages weaker demand and higher input costs.
Olin earnings and revenue assumptions
Olin's current earnings are a loss of US$196.9 million, with analysts expecting earnings of US$232.3 million by 2029 on forecast revenue of US$7.8b. That path assumes revenue growth of 5.0% each year and an earnings swing of roughly US$429 million from today's loss to the 2029 consensus figure.
Uncover why Olin's fair value indicates a 30% potential upside to its current price that may narrow quickly.
Exploring Other Perspectives
For a very different read on Olin Corporation, look at how the lowest analysts lean on sustainability risk. They were already pencilling in slower revenue of about US$7.5b and earnings of roughly US$254.3 million by 2029. Those pre news estimates reflect a tighter, more cautious story that could shift as the index move sinks in.
Explore 3 other Olin fair value estimates, including one that suggests it could be worth just $21.00.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Olin research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Olin. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Olin's overall financial health at a glance.
Looking for more Olin style investment ideas?
If the Olin story has you thinking about what else might be mispriced or overlooked, the Simply Wall St Screener can help you sort through the wider market quickly and on your own terms.
- For investors hunting for quality at a reasonable entry point, scan our list of 27 high quality undervalued stocks that pair stronger fundamentals with more modest expectations.
- If capital protection and steadier profiles are your priority, focus on 31 resilient stocks with low risk scores that rate well on our risk scoring framework.
- When you want a cleaner balance sheet behind the earnings story, narrow your search using the list of solid balance sheet and fundamentals (25 results) and see which candidates merit a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com