


The United States and China may be fierce competitors in many fields, with AI being the latest addition to these battlegrounds. Yet that hasn't deterred semiconductor company Qualcomm (QCOM) from forging a multi-year patent alliance with Chinese tech giant Huawei. Touted as a cross-licensing agreement where each company will have access to the other's patents, the agreement covers AI, computing, 5G, and networking technologies. Additionally, Qualcomm will also acquire some of Huawei's US patents.
The deal is subject to regulatory approvals. Unlike most other deals, this is an important caveat for this one, as Huawei remains on the U.S. Commerce Department's Entity List, and the applicable rules impose stringent licensing requirements on exports and transfers to Huawei and specified affiliates.
Talking about the deal with Seeking Alpha, a Qualcomm spokesperson said, “Qualcomm and Huawei entered into a multi-year, broad patent license agreement that includes cross-licenses across a range of technology fields. The terms are confidential, but reports characterizing Qualcomm as a net payor on the license agreement are incorrect. In addition, assertions that the agreement is related to LogicFold are not accurate. Separately, Qualcomm has agreed to purchase certain Huawei non-cellular U.S. patents across multiple technology areas.”
About Qualcomm
Founded in 1985, Qualcomm is both a semiconductor company and an intellectual-property/licensing company. Its historical strength comes from inventing foundational wireless technologies and licensing them broadly, while its current strategy is to use that technology base to expand from smartphones into other areas.
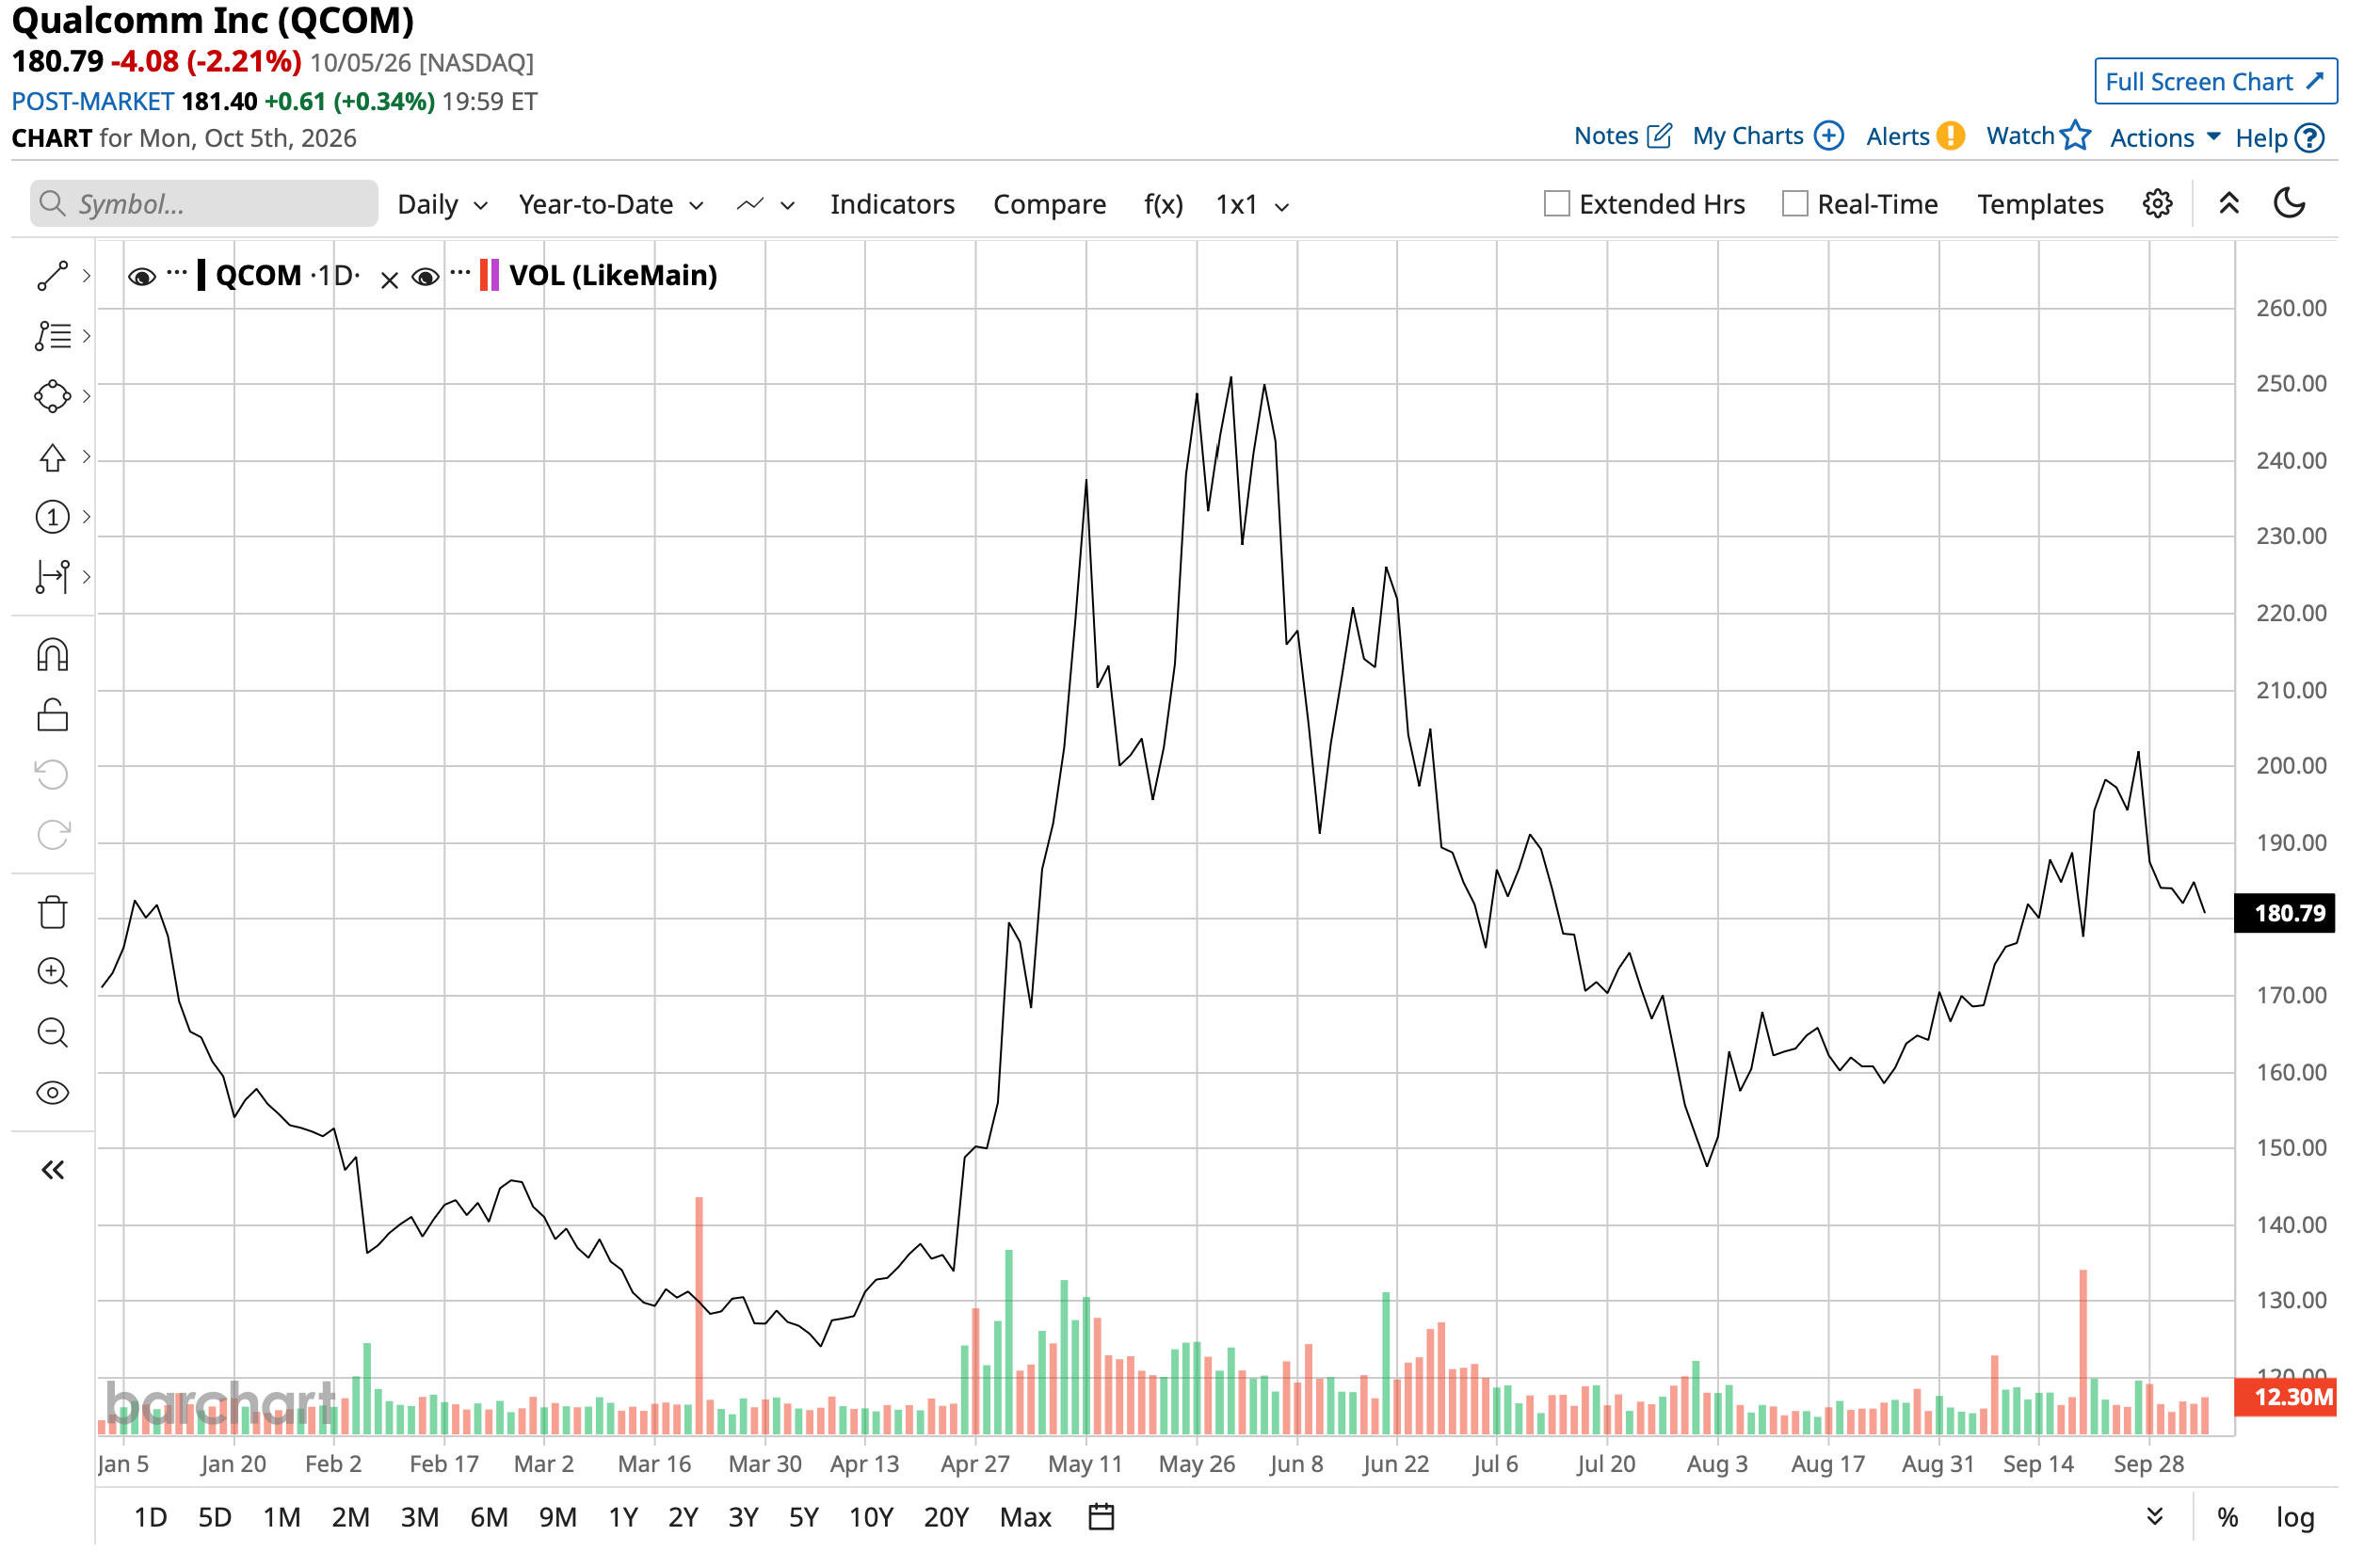
Valued at a market capitalization of $194.2 billion, QCOM stock is up 5.7% on a year-to-date (YTD) basis. The stock also offers a dividend yield of 2.02%, with the company on the verge of becoming a “Dividend Aristocrat,” having raised its dividend for the past 23 consecutive years.
So, can this licensing agreement turn out to be a material one for Qualcomm? Let's analyze.
QTL Boost
Qualcomm's move on AI inference has been the headline-grabber, with the company expecting revenues exceeding $15 billion by FY 2029 from data centers. However, with a pre-tax profit margin that is 2.65 times higher than the company's traditional semiconductor business (69% vs 26%), licensing, or the QTL segment of the company, is an essential cash engine. Thus, this deal with Huawei will be a shot in the arm for the company in that regard.
Here, if Qualcomm gains access to Huawei's polar codes technology, that could be a significant win for the company. Polar codes are a method of protecting data from transmission errors, as an example of their contribution to mobile communications. Patents around such communications methods are relevant to a broad 5G agreement. However, neither Qualcomm nor Huawei has identified polar code patents as one Qualcomm is purchasing, and the announcement does not say Qualcomm can collect royalties from other manufacturers for Huawei’s polar code inventions. Access to Huawei’s rights could help Qualcomm sell its chips and settle licensing terms with Huawei, which is different from adding those patents to QTL’s portfolio for licensing to third parties.
Q3 Dichotomy
Qualcomm’s third quarter fiscal 2026 results showed declines in both revenue and earnings. However, revenue still exceeded Wall Street expectations, even as elevated memory prices weighed on overall operations.
Total revenue decreased 4% year over year to $9.9 billion. The core handset segment experienced a steeper drop of 20% to $5.1 billion. Licensing revenue declined more moderately, falling 3% year over year to $1.3 billion. Earnings per share dropped 20% to $2.21, coming in slightly below the consensus estimate of $2.23.
Looking ahead to the fourth quarter, Qualcomm guided for earnings per share in the range of $2.05 to $2.25. The midpoint of this outlook implies a 28% year-over-year decline from the $3 per share reported in the fourth quarter of 2025. Chip revenue is expected to fall between $8.4 billion and $9 billion, while licensing revenue is projected in the range of $1.2 billion to $1.4 billion.
Gross margins contracted to 53% from 56% in the year-earlier period. Net cash from operating activities for the nine months ended June 28 totaled $8.4 billion, down from $10 billion in the comparable prior year period. Qualcomm closed the quarter with $4.5 billion in cash, which exceeded its short-term debt balance of approximately $2.5 billion.
The relatively subdued performance of the stock this year has brought Qualcomm’s valuation multiples to more moderate levels. The forward P/E and P/CF of 17.63 and 15.85 times, respectively, sit below the sector median. However, the forward P/S of 4.60 is just above the sector median of 3.51.
Analyst Opinion on QCOM Stock
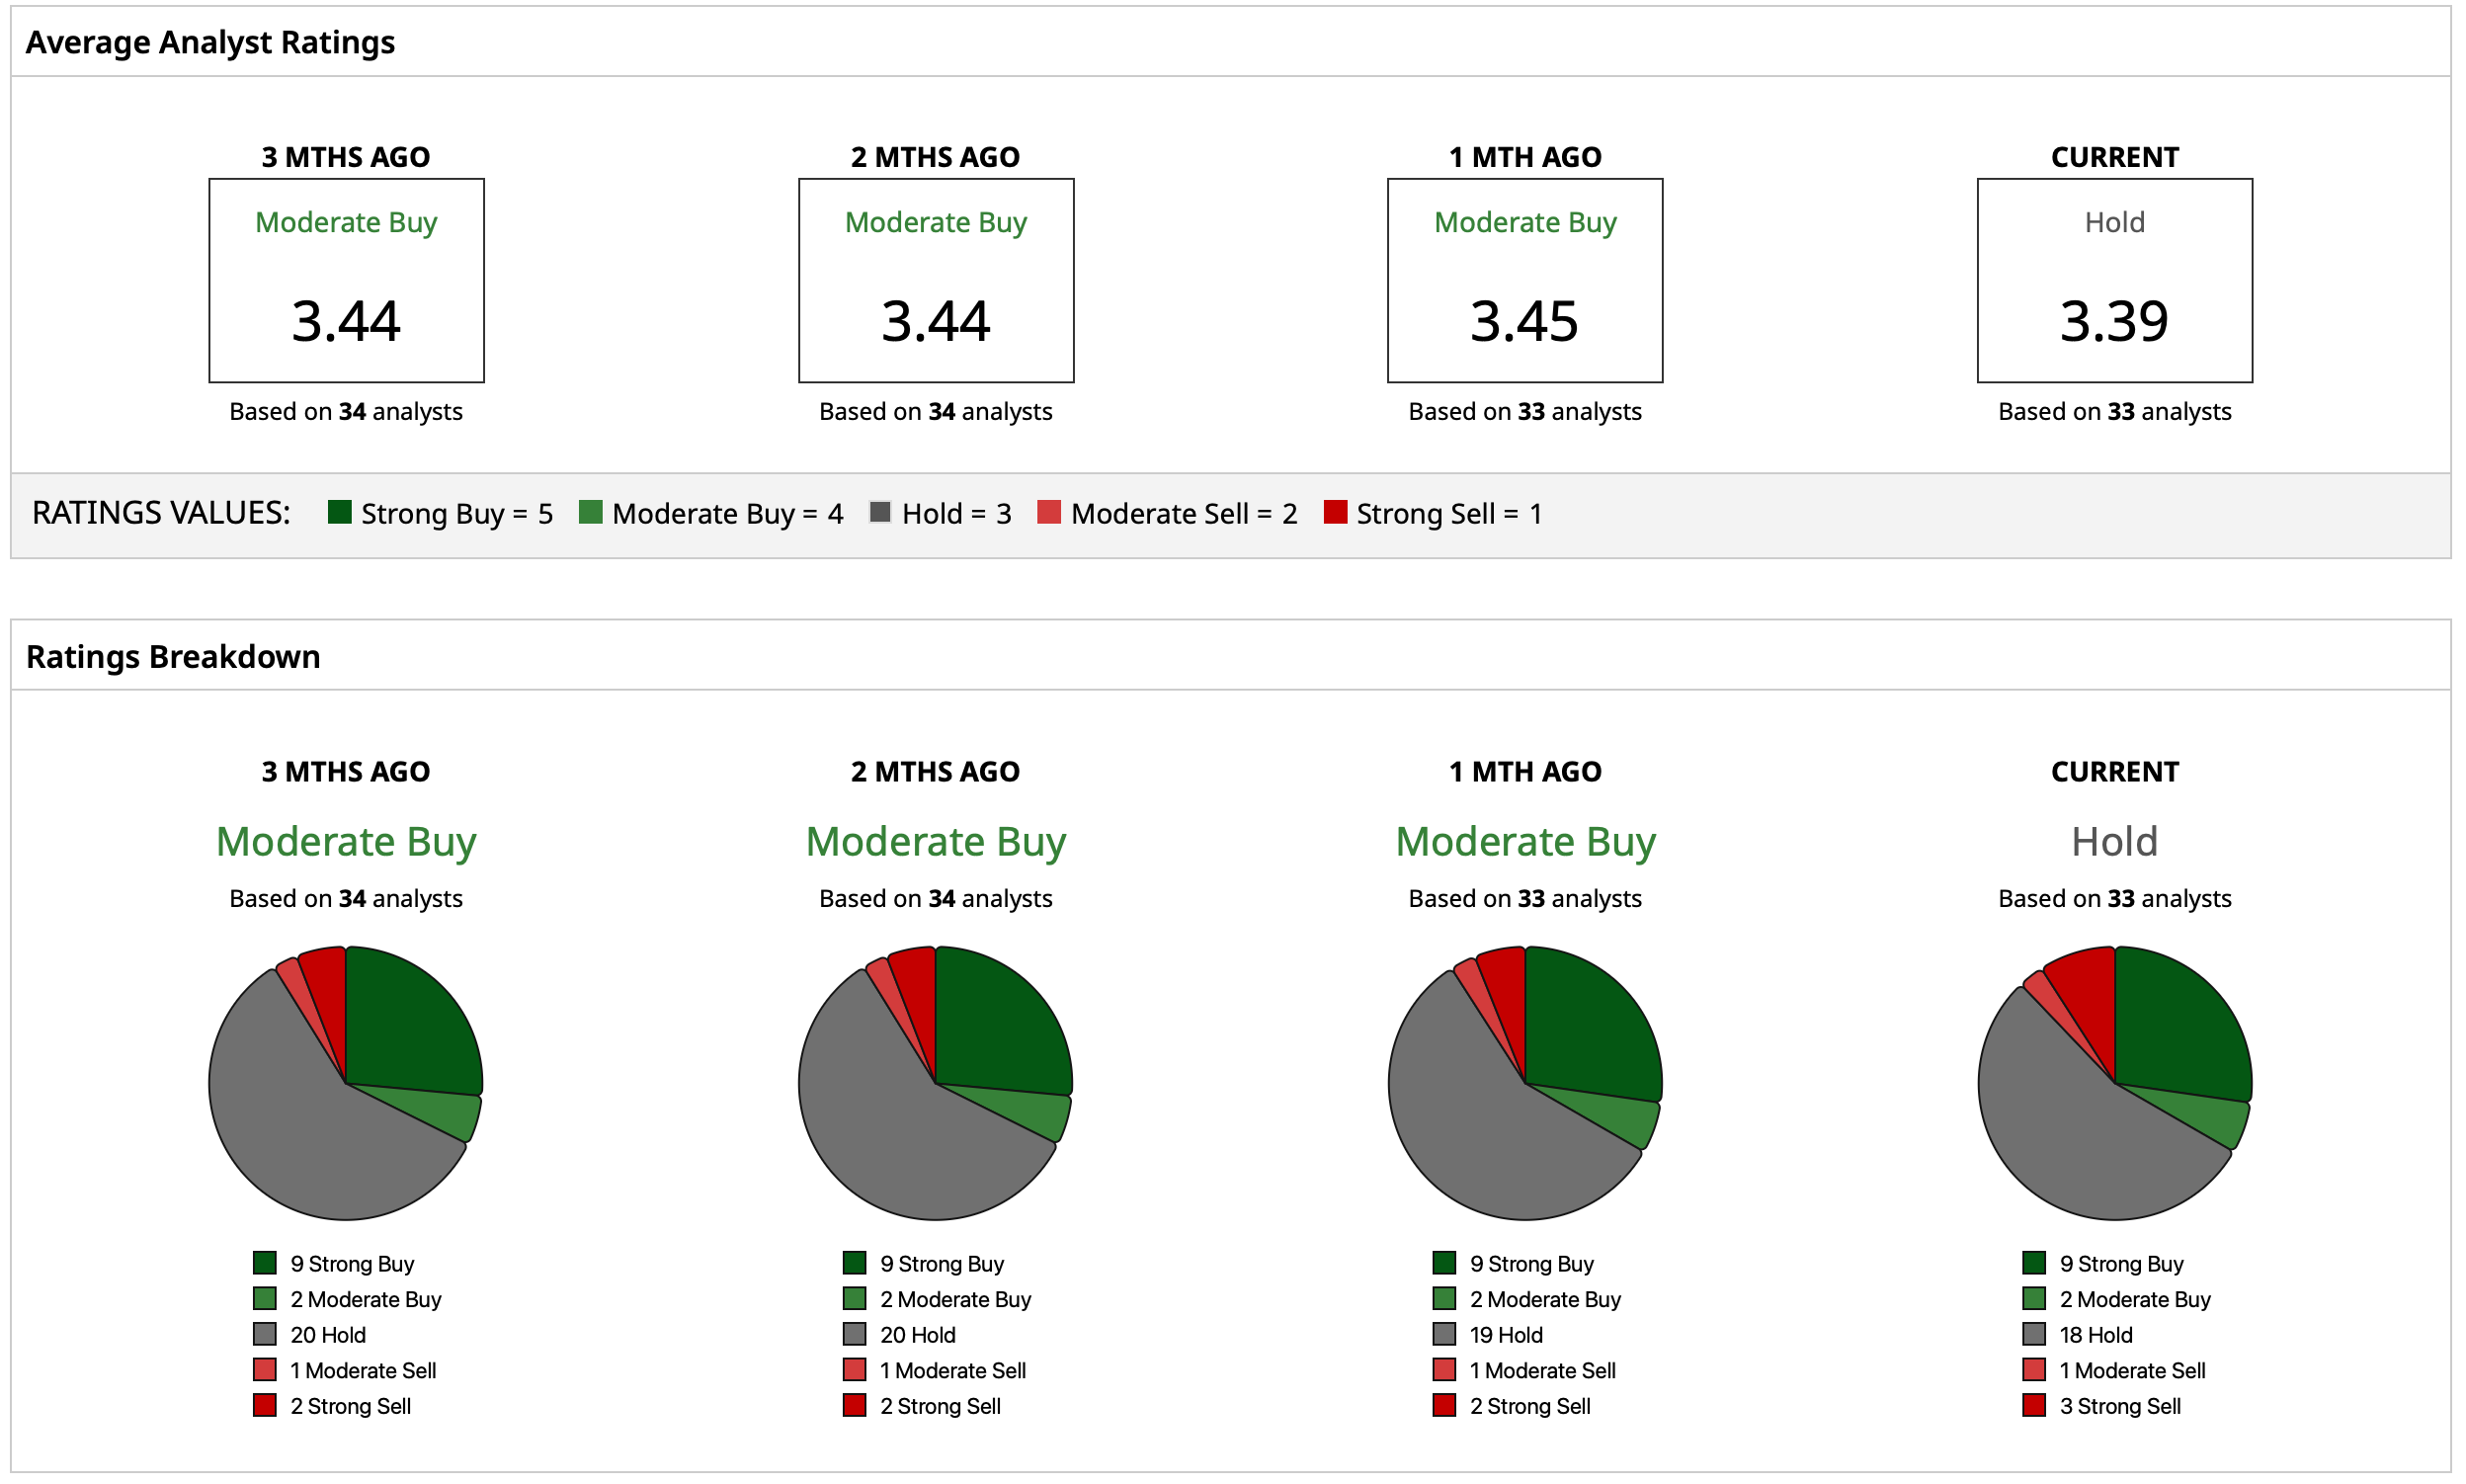
Considering all this, analysts have deemed QCOM stock to be a “Hold.” The mean target price of $198.31 indicates a potential upside of 9.7% from current levels. Out of 33 analysts covering the stock, nine have a “Strong Buy” rating, two have a “Moderate Buy” rating, 18 have a “Hold” rating, one has a “Moderate Sell” rating, and three have a “Strong Sell” rating.
On the date of publication, Pathikrit Bose did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.