


Seagate Technology Holdings plc (STX), headquartered in Singapore, is a global data storage company specializing in mass-capacity storage solutions, with a market capitalization of approximately $183.2 billion. The company develops hard drives and advanced storage platforms for consumer, cloud, enterprise and edge markets, helping organizations manage growing data volumes fueled by AI adoption and digital transformation.
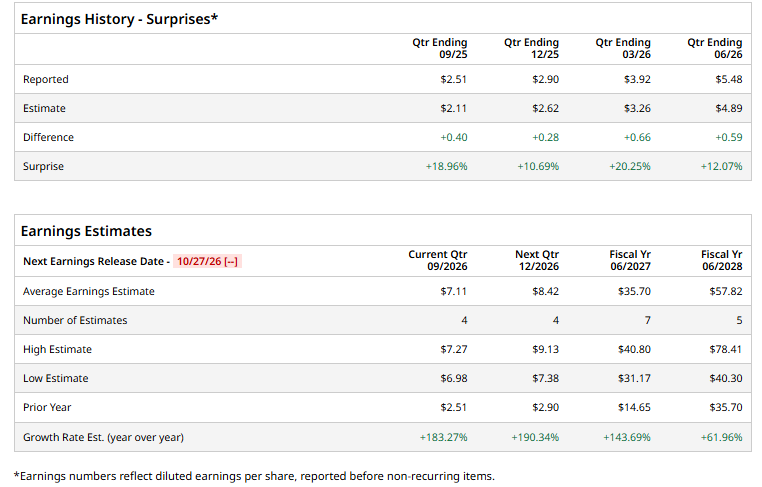
STX is set to report its Q1 earnings soon. Ahead of the release, analysts expect the company to report diluted EPS of $7.11, up a staggering 183.3% from $2.51 in the year-ago quarter. Moreover, STX has exceeded Wall Street’s EPS estimates in each of the past four quarters, highlighting its consistent earnings performance.
For fiscal 2026, analysts expect STX to report EPS of $35.70, reflecting a substantial 143.7% increase from $14.65 in fiscal 2025. EPS is projected to increase another 62% year over year to $57.82 in fiscal 2027.
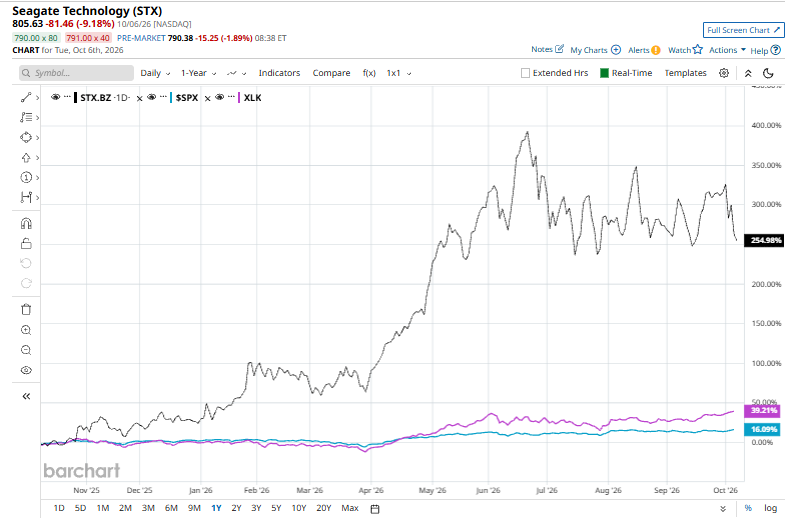
STX stock has surged 231.8% over the past 52 weeks, significantly outperforming the S&P 500 Index ($SPX), which returned 16%, as well as the State Street Technology Select Sector SPDR ETF (XLK), which gained 40.5% over the same period.
Seagate’s stock has delivered a remarkable run, supported by rapid business growth, market share gains and improving profitability. Revenue grew 36.4% annually over the past two years, while its operating margin expanded by 16.8 percentage points and free cash flow margin improved by 14.5 percentage points over the past five years, highlighting stronger efficiency and cash generation.
Analysts remain strongly bullish on STX, with the stock carrying a consensus “Strong Buy” rating. Of the 26 analysts covering the stock, 21 recommend a “Strong Buy,” one rates it a “Moderate Buy,” and four suggest a “Hold.” Meanwhile, the average analyst price target of $1,143.48 implies potential upside of 41.9% from the current share price.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.