


Systemair (OM:SYSR) has moved to shut production at its Waalwijk facility in the Netherlands, a restructuring plan that affects about 70 employees and introduces a sizeable one off charge.
The restructuring news comes after a mixed period for the stock. Systemair’s share price is up 10.18% over 90 days but down 2.81% over 30 days, while its 1-year total shareholder return of 11.88% suggests steadier long-term momentum.
Scan how Systemair compares with other industrials undergoing footprint reshuffles by reviewing the hand picked list of solid balance sheet and fundamentals (206 results) that may better balance resilience and operational change.
Systemair is absorbing a sizeable one off charge today in exchange for planned cost savings tomorrow. Does that trade off still leave the risk reward tilted toward buyers at the current price, or not?
Preferred P/E of 22.6x on Systemair: Is it justified?
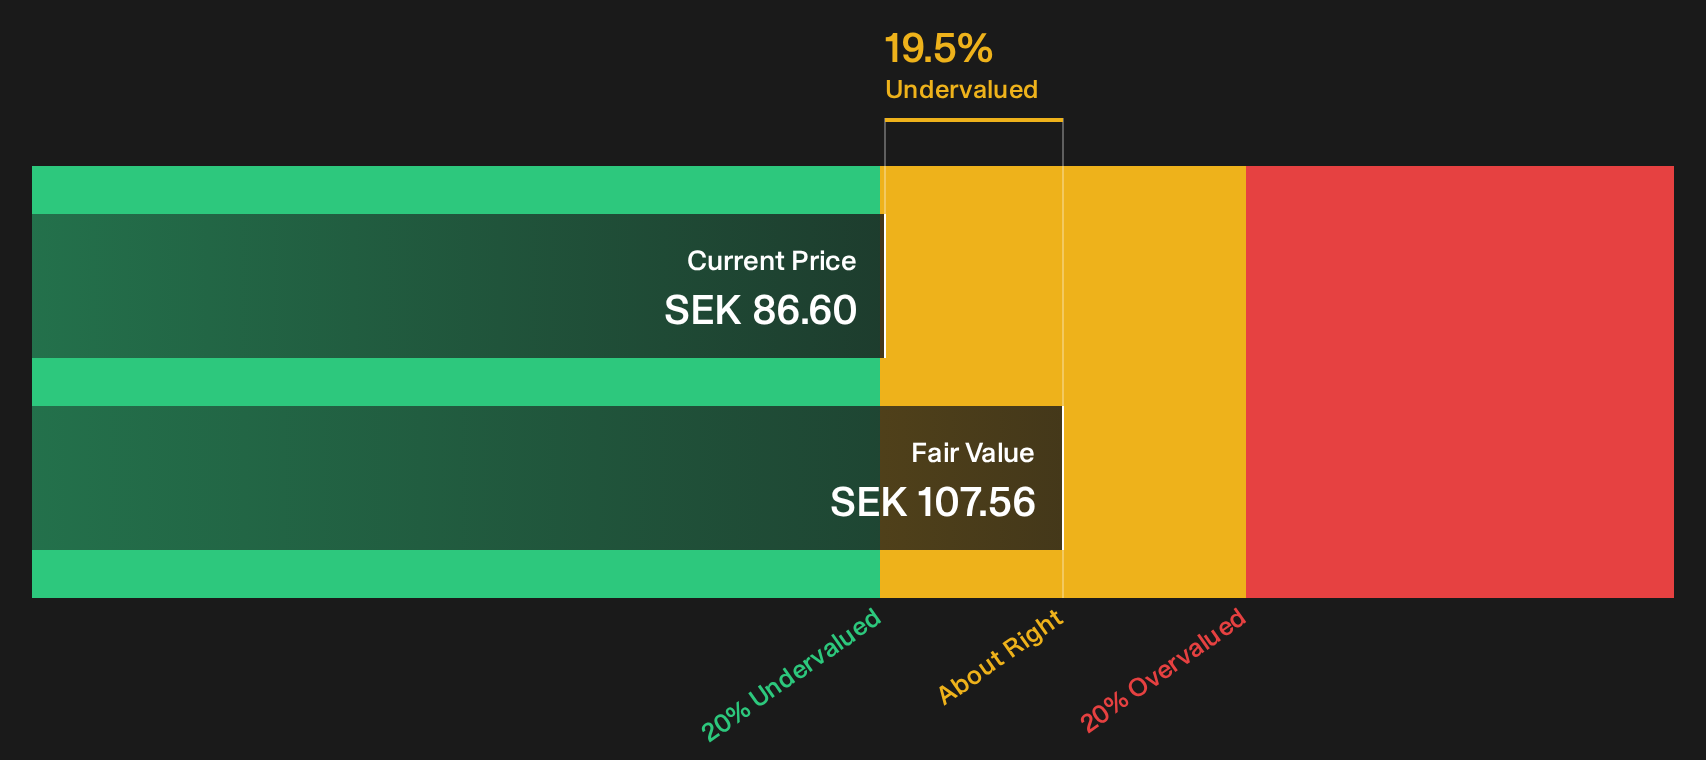
Valuation on Systemair right now hinges on a P/E of 22.6x at a last close of SEK86.60, with our fair P/E estimate sitting slightly lower at 21x, and a separate cash flow model indicating the shares trade about 19.5% below an estimated fair value of SEK107.56.
The P/E ratio compares the current share price with earnings per share. For a ventilation and climate control specialist like Systemair, it tells you how much investors are paying for each unit of current profit in a sector where cash flows matter at least as much as headline revenue.
On the cash flow side, the SWS DCF model projects future free cash flows and then discounts them back to today using a required rate of return. That produces an estimated value of SEK107.56 per share, which is above the current market level and implies the present price may not fully reflect those projected cash flows if the assumptions hold.
At the same time, the earnings multiple sits in an interesting middle ground. Systemair trades on a P/E of 22.6x, which looks cheaper than both the European Building industry average on 24.6x and a peer group average at 28.3x. Against the fair P/E of 21x, that same ratio looks a touch expensive, a level the market could move toward if sentiment or earnings expectations cool.
Explore the SWS fair ratio for Systemair.
Result: Price-to-earnings of 22.6x (ABOUT RIGHT)
Still, Systemair faces clear risks if the Waalwijk shutdown delivers slower cost savings than expected, or if ventilation demand softens in key European markets.
Find out about the key risks to this Systemair narrative.
Another view on Systemair’s value
The P/E work paints Systemair as roughly fairly priced, yet the SWS DCF model points to a different story. At SEK86.60 the shares sit about 19.5% below an estimated cash flow value of SEK107.56. If cash generation follows those forecasts, is the market leaving a gap open for long term investors?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Systemair for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 178 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Systemair’s valuation and restructuring impact only matter if they help you act. Take a few minutes to test the numbers yourself, then weigh those potential positives by digging into the 3 key rewards.
Looking for more investment ideas beyond Systemair?
If Systemair has sharpened your focus on valuation and risk, broaden your watchlist now. Fresh opportunities rarely wait around for investors who hesitate.
- Target potential mispricing by scanning a 178 high quality undervalued stocks that filters for quality businesses where fundamentals and price appear out of sync.
- Prioritise sleep at night resilience with a 228 resilient stocks with low risk scores built to surface companies that score well on financial strength and volatility.
- Spot early stage potential through a 122 elite penny stocks with strong financials that zeroes in on smaller stocks with stronger balance sheets and cleaner numbers than the crowd expects.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com