


JEOL launches HAXIS semiconductor failure analysis platform
JEOL (TSE:6951) has introduced its HAXIS low angle ion milling scanning electron microscope, a new semiconductor failure analysis system that combines LIM delayering, SEM imaging, and passive voltage contrast to refine defect localization.
Momentum around JEOL has been strong, with a 30-day share price return of 17.10% and a year-to-date share price return of 64.27%. Meanwhile, the 1-year total shareholder return of 61.96% and 3-year total shareholder return of 89.08% suggest investors have already priced in meaningful expectations around its broader instrumentation and semiconductor exposure.
Scan a handpicked group of semiconductor and chip-tool suppliers showing similar momentum and product catalysts to JEOL through the 91 AI infrastructure stocks.
JEOL now trades only modestly below analyst targets after a sharp run, so the central question is whether that small discount reflects market caution or a misread of its semiconductor opportunity.
Preferred P/E of 25.6x for JEOL: Is it justified?
JEOL closed at ¥8,271, trades on a P/E of 25.6x, and screens as expensive relative to both the broader JP Electronic industry and its own fair ratio benchmark.
The P/E ratio compares the share price with earnings per share and, for a business like JEOL that already generates profit, it gives a quick read on how much investors are willing to pay for each unit of current earnings.
Here, the market is applying a richer multiple than the JP Electronic industry average of 16.8x. This suggests buyers are willing to pay a premium for JEOL's exposure to scientific instruments, semiconductor equipment, and medical systems as well as forecast earnings growth that analysts expect to be 21.5% per year.
Yet the same P/E of 25.6x sits above an estimated fair P/E of 22.8x. As a result, current pricing looks stretched both against the sector and against the level that regression analysis suggests the market could move toward if sentiment cools or expectations reset.
Explore the SWS fair ratio for JEOL.
Result: Price-to-earnings of 25.6x (OVERVALUED)
Still, any stumble in JEOL's semiconductor tools or a slowdown in key markets like China and North America could quickly puncture the current valuation premium.
Find out about the key risks to this JEOL narrative.
Another view on JEOL's value
A different lens tells a sharper story. The SWS DCF model estimates JEOL's future cash flow value at ¥3,608.57 per share, compared with the current ¥8,271 price. That points to a stock trading well above this model's fair value. Which signal should matter more to you: earnings multiple or cash flow math?
Look into how the SWS DCF model arrives at its fair value.
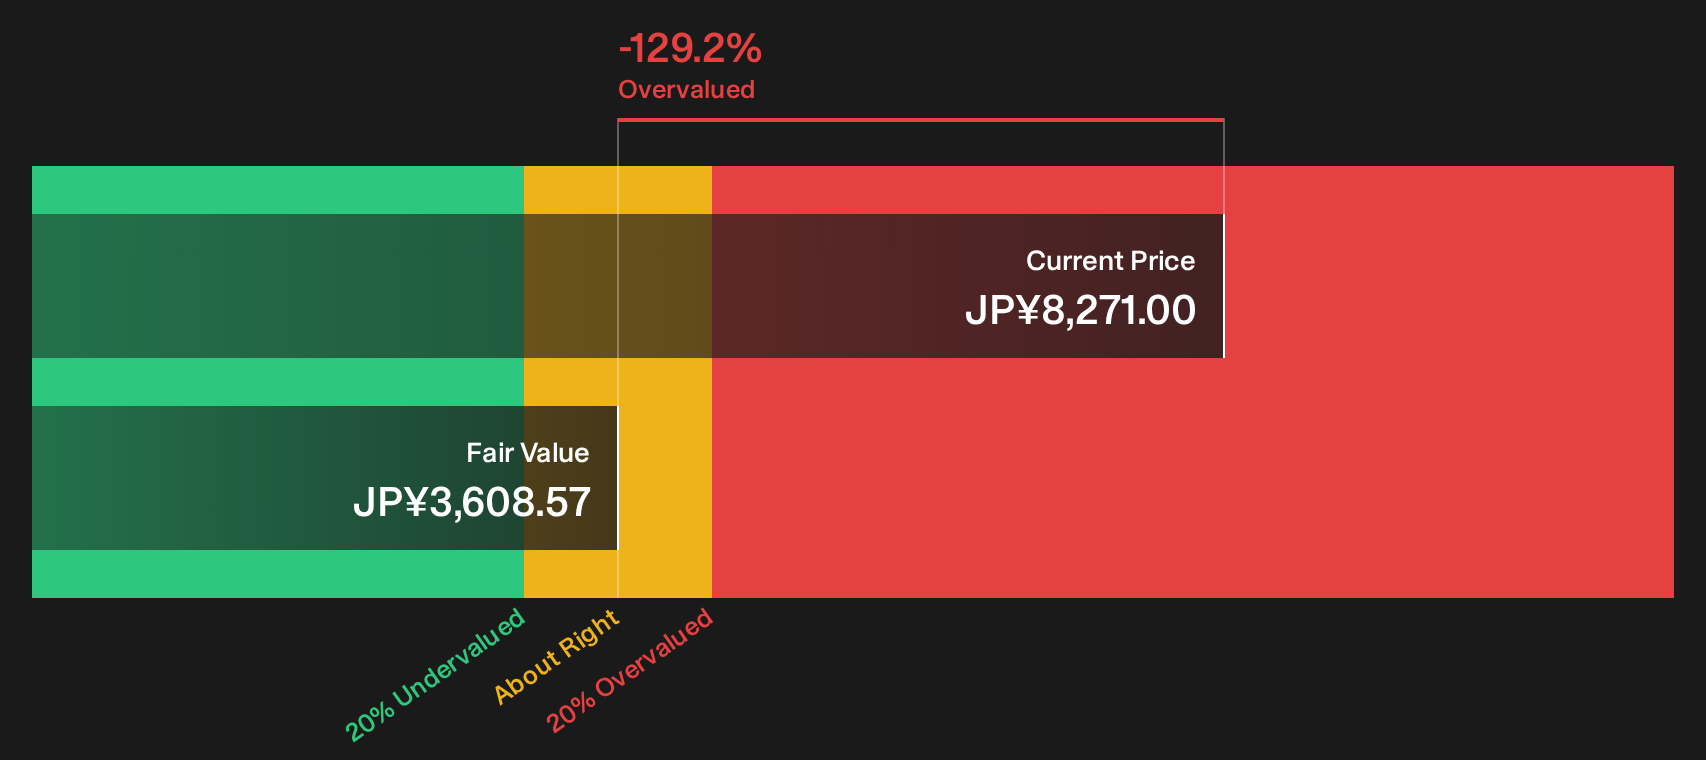
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out JEOL for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
JEOL's setup looks finely balanced between excitement and concern, so it helps to move fast and weigh the data with your own lens. To see both sides laid out clearly, review the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond JEOL?
If JEOL has sharpened your focus on opportunities, do not stop here. Fresh ideas often come from comparing leaders with overlooked or differently positioned peers.
- Target steady compounding by scanning companies that combine quality with attractive pricing using the 14 high quality undervalued stocks.
- Protect your downside by reviewing stocks that score well on resilience and risk using the 22 resilient stocks with low risk scores.
- Spot future contenders early by checking a curated 75 high quality undiscovered gems before wider attention catches up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com