


Sandisk stock reacts to AI driven surge and fresh product plans
Sandisk (SNDK) has been triggered back into focus after a very large 2026 share price gain linked to AI related demand, new High Bandwidth Flash development and long term data center supply deals.
After an intense run that has left the 1 year total shareholder return above 10x, Sandisk has hit a softer patch, with the share price down over the past week and month even as enthusiasm around AI infrastructure, index inclusion and data center contracts keeps the broader story in focus.
Seize the AI memory story around Sandisk by scanning a hand picked set of 91 AI infrastructure stocks that are also tied to data center build outs and infrastructure spending.Sandisk now trades after a very large AI driven climb and a fresh pullback. Are you paying for durable NAND cash flows, or for sentiment that just swung too far in both directions?
Most Popular Narrative: 66% Overvalued
Sandisk last closed at $1,660.46, while the most followed narrative anchors fair value at $1,000. This frames today’s price as rich against those long range expectations and puts the focus squarely on how much AI memory demand can really deliver.
Management is planning bit supply growth in line with a mid to high teens demand compound annual growth rate. Any easing in AI driven exabyte demand or faster industry wide wafer and node additions could pressure NAND pricing, which would weigh directly on revenue and gross margin progression.
See why 9 investors see Sandisk as 66% overvalued.
Result: Fair Value of $1,000 (OVERVALUED)
Still, a sustained supply-constrained backdrop or faster adoption of BiCS8 and BiCS10 could keep Sandisk pricing and margins firmer than this cautious narrative assumes.
Find out about the key risks to this Sandisk narrative.
Another View on Sandisk valuation
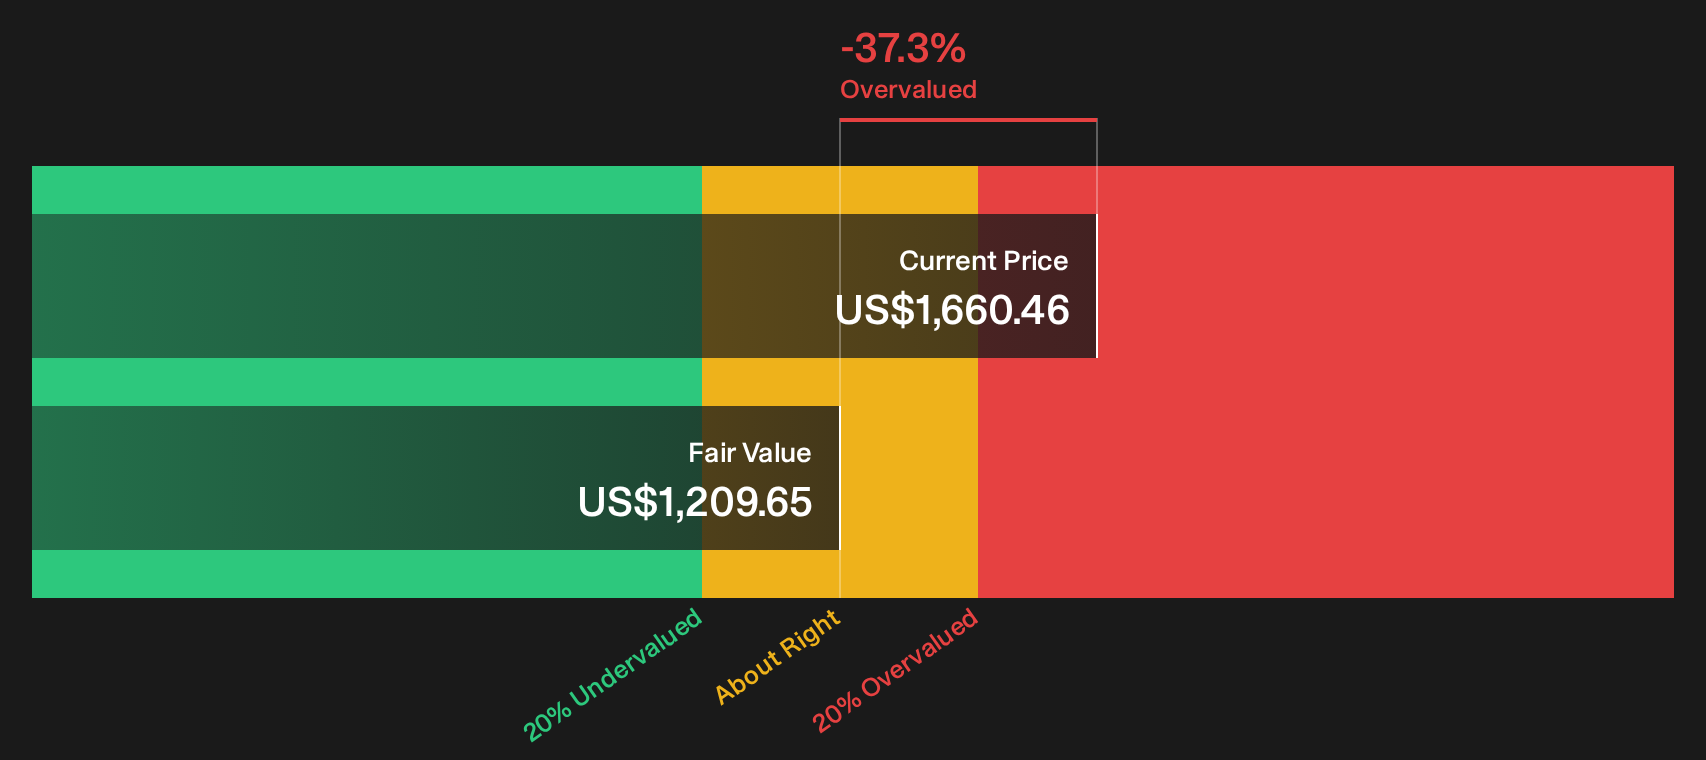
The first narrative pins Sandisk at $1,000 based on long term earnings forecasts, yet the current share price of $1,660.46 implies investors are already paying above that modeled fair value. Our DCF model points to a future cash flow value of $1,209.65, which still sits below today’s price. Which yardstick do you trust more when expectations are this stretched?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment around Sandisk is split, with some investors focused on stretched pricing and others pointing to AI memory tailwinds and solid fundamentals. Act quickly, review the data, and weigh both sides by starting with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Sandisk?
If Sandisk feels fully priced to you, broaden your watchlist now with other focused opportunities that could fit your risk tolerance and return goals.
- Target resilient cash generators by reviewing a 27 high quality undervalued stocks that combine quality fundamentals with pricing that still leaves room for upside.
- Strengthen your income stream by scanning 8 dividend fortresses that aim to pair higher yields with more robust balance sheets.
- Prioritize stability under pressure by assessing 31 resilient stocks with low risk scores that rate well on financial health and business risk factors.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com